Roseville, CA · NMLS 281056 · Licensed CA, TN, TX (916) 705-2557 adebusk@loandepot.com

Mortgage Made Easy · One step at a time

Boost Your Credit

A stronger start for the home you want.

Your credit tells part of your financial story. It does not tell me everything about you, your goals, or what may be possible next.

Whether you are preparing for your first home, coming back after a difficult season, or planning a refinance, let's make credit easier to understand. Small, consistent steps can help you build healthier habits and prepare for a more informed mortgage conversation.

Amy DeBusk smiling in her office
Clear guidance. A plan built around your next chapter.

Start where you are

You do not need perfect credit to start a conversation.

I'm Amy DeBusk, your Branch Manager & Mortgage Advisor with loanDepot. I help you understand how your credit fits alongside income, debts, savings, and the home you want to finance. We can identify questions to resolve, documents to gather, and options worth exploring.

Sometimes the next step is a mortgage review. Sometimes it is giving yourself time to prepare. You deserve to understand the choices without feeling judged or rushed. No one can promise a particular score increase or an approval from a few general tips.

A woman reviewing her spending plan at a sunlit kitchen table
A little time to plan today. More confidence for your next chapter.

There may be more possibilities than you think

Credit score starting points for loan options.

A score is one part of the conversation. Here are options we can explore, subject to the selected program's requirements and review of your complete application.

Requirements and availability can change. Meeting a minimum score does not establish approval. I will confirm the applicable requirements for your loan. See CalHFA's government-loan handbook for its program-specific rules.

A little progress at a time

Small steps. More breathing room.

You don't have to tackle everything today. Let's start with a few habits that support the home and life you want.

Know what is on your reports.

Review your credit reports for unfamiliar accounts, incorrect balances, or payment-history errors. Request your reports through AnnualCreditReport.com. Checking your own reports does not lower your score.

Start here

Set aside a few minutes to review one report and note your questions.

Make on-time payments easier.

Use reminders or automatic payments that fit your cash flow. Check that payments actually go through and that funds are available. If a payment is becoming difficult, contact the creditor early to discuss options.

Start here

Choose a payment reminder that fits your routine.

Give card balances some attention.

Balances relative to credit limits can affect credit scores. Work toward lower balances without losing sight of money needed for essentials and your home purchase. You do not need to carry interest-bearing debt to build credit.

Start here

Write down your card balances and limits for your review.

Correct information that is wrong.

Dispute inaccurate information with the reporting company and the business that supplied it. Keep copies of supporting records. The CFPB explains the dispute steps.

Start here

Save the records that support the correction you want to request.

Plan account changes thoughtfully.

Opening several accounts or closing a card can affect your credit picture. If a home purchase or refinance is approaching, talk with me before adding a new payment or making account changes solely to influence your score.

Start here

Check in with me before making changes while preparing for a mortgage.

Don't close a card just because the balance is zero.

Paying it off is a positive step. Closing the account can reduce your available credit and, if you have balances on other cards, increase the share of credit you are using. In some circumstances, that may lower your score.

Fees, spending temptations, and your overall finances matter too. Before closing an account solely to improve your credit, let's talk through how it fits your homebuying plans. Read FICO's explanation.

Start here

Keep your paid-off card open and ask me before deciding to close it.

Credit Karma
Credit Karma

Keep an eye on your credit.

Make credit monitoring part of your routine.

I recommend monitoring your credit so you can notice changes and ask questions early. Credit Karma offers free monitoring of your Equifax and TransUnion reports. Turn on alerts and review changes you do not recognize.

The scores you see in the app may differ from the scores used for a mortgage. Bring your questions to us so we can help put the information in context.

Learn about Credit Karma's free monitoring → · Review your reports with our team →

Learn more from the CFPB's credit-building guidance. Results and timing depend on your individual credit history.

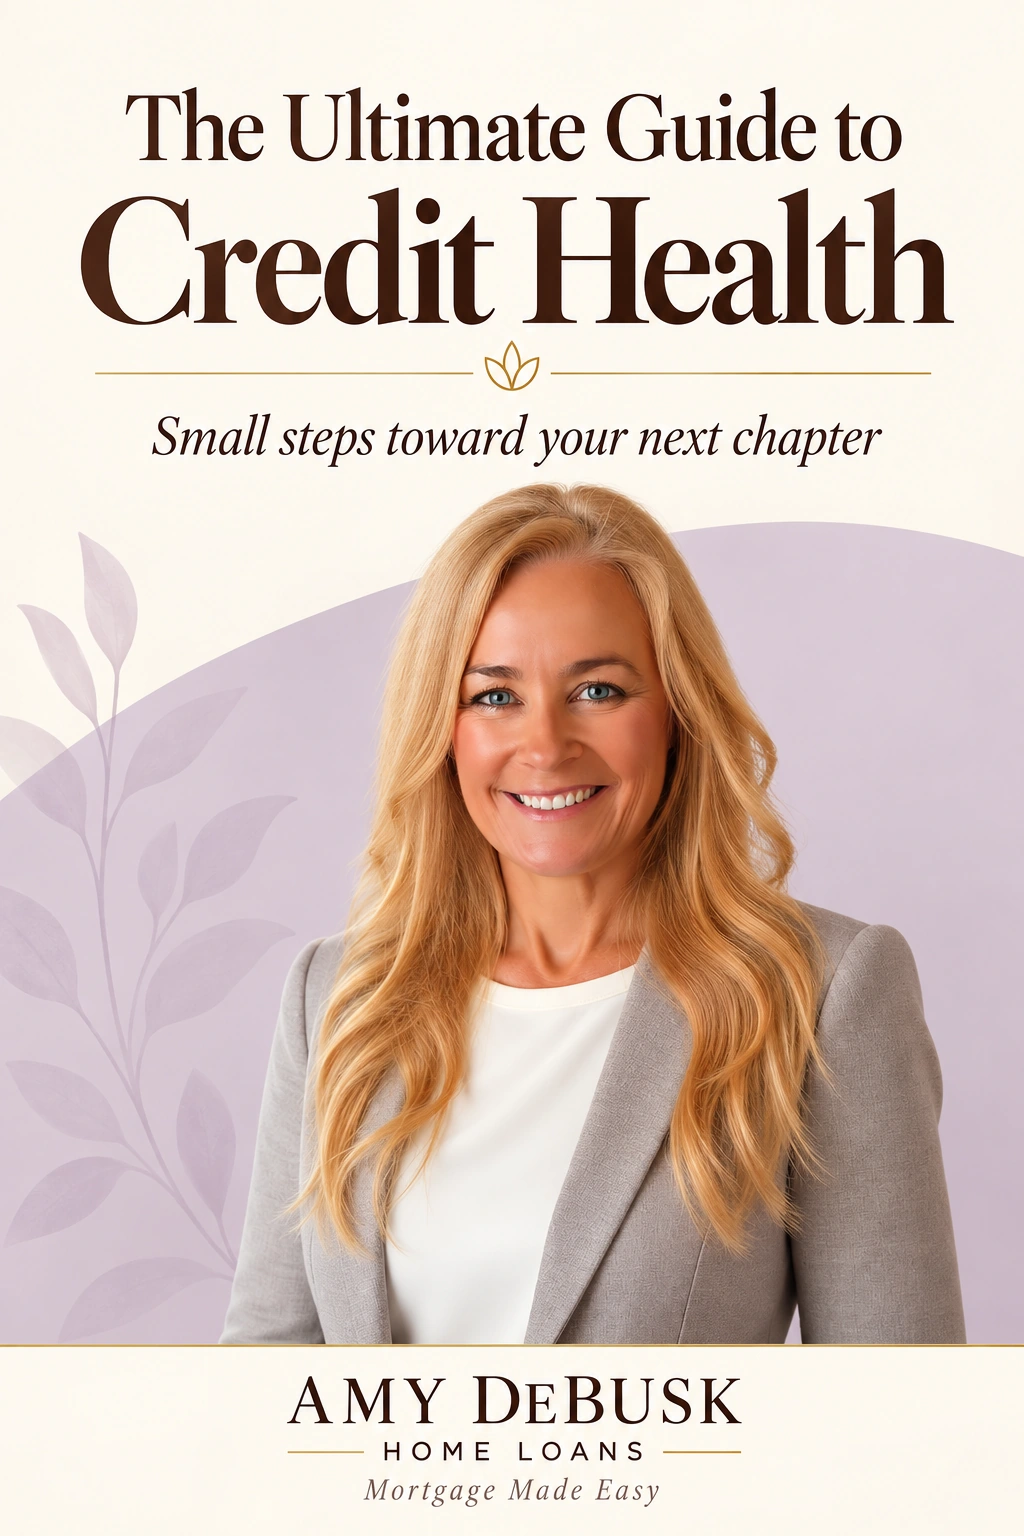
The Ultimate Guide to Credit Health, presented by Amy DeBusk

Complimentary 7-page PDF

The Ultimate Guide to Credit Health

Keep a helpful starting point close by. My guide introduces credit-score factors, common reasons scores change, credit myths, and the connection between credit and mortgage pricing.

Read it at your own pace, make a note of your questions, and bring them to our conversation.

Download Your Free Guide

Preview the PDF →

The guide's score and savings examples are illustrations, not current loan pricing or promised results. We will review current requirements for your situation.

Let's connect your credit to your home plans.

If you have a purchase or refinance in mind, tell me your preferred timing and what concerns you. We can discuss how a mortgage credit review works and what information to prepare. The score in a consumer app may differ from one used for a mortgage because the model or information date can differ.

If you are already applying for a mortgage, keep me informed about new debts, account changes, or disputes. You still have the right to correct errors; communication helps us account for those changes in your mortgage review. Use our secure process for financial documents rather than emailing account numbers or full reports.

Do I need a specific score before I contact you?
You can begin with questions. Requirements vary by loan and the rest of your application. I can help you understand what needs review without assuming one number answers everything. See the credit-score starting points above, or ask me about the complimentary credit analysis offered when you apply.
How quickly will my score improve?
There is no single timeline or guaranteed point increase. Your history, the information reported, and the scoring model all matter. Focus on accurate information and sustainable habits.
Should I close a card I no longer use?
I don't recommend closing credit cards, even when the balance is zero. Keeping the account open preserves available credit. Closing it can increase the percentage of available credit you are using and may negatively affect your score. Before closing a card, especially while preparing to buy or refinance, talk with me so we can review your situation together.
Do you provide credit-repair services?
When you apply for a home loan with me, we offer a complimentary credit analysis using our simulator to identify recommendations that may help improve your score. This is part of our mortgage guidance, not a credit-repair service or a promise to remove accurate information. I will help you understand the recommendations and your next steps.

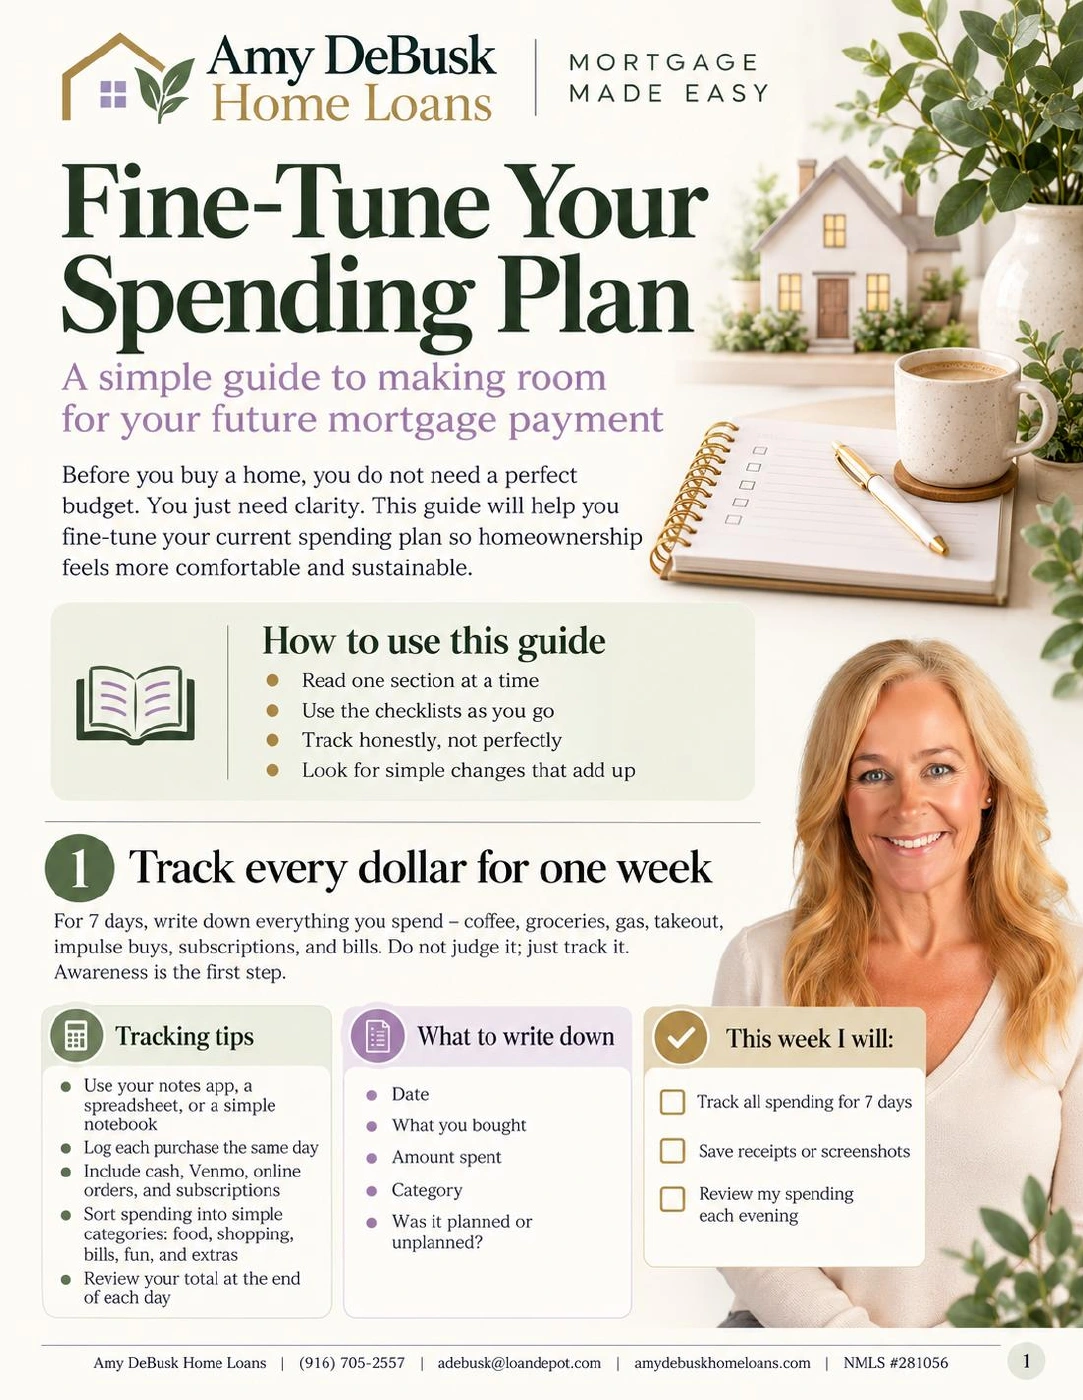
Healthier credit. A spending plan that supports your life.

Credit health and everyday money habits often grow together. A spending plan can help you make room for on-time payments, work toward lower balances, and build a cushion for unexpected expenses. It is about giving your money a purpose, not taking the joy out of your life.

Not every credit challenge comes from spending. Errors, illness, lost income, and other life changes can play a part. Whatever brought you here, we can start with where you are today and choose manageable next steps.

Guidance at your pace

Let's look at your credit together.

Not ready to apply? Start with the reports you have.

My team and I are happy to go over your Credit Karma reports or the free credit reports you receive from AnnualCreditReport.com. We can help you understand what you are seeing, talk through your questions, and connect your next steps to your home goals. You do not have to be ready to apply to start that conversation.

Contact us to arrange your review and a secure way to share your reports. Please do not email account numbers, passwords, or full credit reports.

Your complimentary credit analysis when you apply.

When you apply for a home loan with me, we offer a free credit analysis. We use our credit simulator to explore recommendations that may help increase your credit score, then walk through what those recommendations could mean for your home financing plans.

You do not have to interpret the results alone. I'll help you understand the suggested steps, consider your available funds and timing, and connect the credit picture to the loan options we are reviewing. A simulation is an estimate, not a guaranteed score change or loan approval.
Your next chapter can start with one question.

You don't have to sort through every credit tip online to know where to begin. Tell me what you hope to do, and let's talk about a practical next step.