
Above the county limit
For a one-unit home in 2026, the baseline conforming limit is $832,750. In designated high-cost counties, it can be as high as $1,249,125. The property address and unit count determine the actual line.
For the home you have been working toward
A larger home purchase deserves more than a quick estimate. Amy DeBusk helps you build a clear mortgage strategy around the home, the payment and the life you want to enjoy there.
2026 jumbo loan guidelines
Jumbo lending has more moving pieces than a standard mortgage, but the basics are straightforward. These ranges come from Amy’s complete Jumbo Loan Guide and give you a useful place to start before we review your exact home, income, assets, and goals.
For a one-unit home in 2026, the baseline conforming limit is $832,750. In designated high-cost counties, it can be as high as $1,249,125. The property address and unit count determine the actual line.
Qualified primary-residence buyers may find a full-documentation option beginning around 10% down. That option has its own lower, program-specific loan-amount cap, so it is not available at every jumbo balance. Many purchases land in the 15%-25% range; second homes, condos, investment properties, or larger loans may need 20%-30% or more.
Many jumbo programs start in the 660-680 range. Higher-leverage or larger loan amounts may call for 700+. Payment history, balances, recent inquiries, and major credit events matter alongside the score.
Standard jumbo options can reach $3 million. Select Super Jumbo programs may go as high as $6 million, subject to the current investor program, property, credit, equity, and reserve requirements.
Some strong applications can go as high as 49.99%. Higher ratios generally need meaningful compensating strengths such as excellent credit, stable income, larger equity, and solid reserves.
Reserves are eligible funds left after your down payment and closing costs. Jumbo lenders commonly measure them against your total monthly housing payment and often look for 6-12 months. The exact amount depends on the loan product, loan amount, loan-to-value, and overall borrower profile.
Before you make an offer
Before you make an offer, we will review the insurance side of the home and help you get a quote for the specific property. Together with taxes, HOA dues and the mortgage payment, it gives you a more useful view of the economics before you decide to move forward.
These are planning ranges, not a loan offer or approval. Loan programs, maximums, pricing, and underwriting guidelines can change; Amy will confirm the current option that fits your actual scenario.
For the home you have pictured for years
A Jumbo loan is for more than a higher price point. It can be the bridge to the home you have been working toward: more room for family, a view you have always wanted, a custom space to gather, or a place that simply feels like home.
My job is to help you bring the dream and the numbers together before you make an offer. We will look at the payment, cash to close, assets, income, the home itself and the room you want your budget to have after closing.
A conversation built around your next chapter
Buying a higher-priced home deserves a plan that reflects the home you love, your finances and the life you want after closing. We will talk through your options together, answer your questions clearly and choose the next step that feels right for you.
Book your complimentary 30-minute consultation
What we will look at early
Income, assets, down payment and reserves can all matter in a jumbo review. We will organize the documents and questions early, so there are fewer surprises later.
Unique homes, acreage, guest spaces, views and custom finishes can make a property harder to compare. We will talk through the home’s details before you get too far ahead.
It is about more than qualifying. We will consider principal and interest, property taxes, insurance, HOA costs when applicable, and the goals you want to keep funding after you move.
For eligible veterans and service members
Many buyers do not realize that a VA-backed purchase loan can finance a home above a local conforming loan amount. With full VA entitlement, the VA does not set a county loan limit, although lender approval, the appraisal and the borrower’s ability to repay still matter.
If you are using remaining entitlement because you have another VA loan or entitlement has not been restored, a down payment may be needed. The amount depends on your remaining entitlement, loan amount, purchase price or appraised value, and lender guidelines. We will review your Certificate of Eligibility and the exact home before you decide which direction fits.
Explore VA Home LoansYou should never assume a high price automatically rules VA out. We can compare a VA path with other financing choices based on your benefit, goals and the home you are considering.
Explore related loan options
The right path depends on the home, your timeline and what you are building next. These are three helpful places to continue the conversation.
Explore select financing options for qualifying loan amounts above the standard jumbo range.
Explore Super Jumbo Loans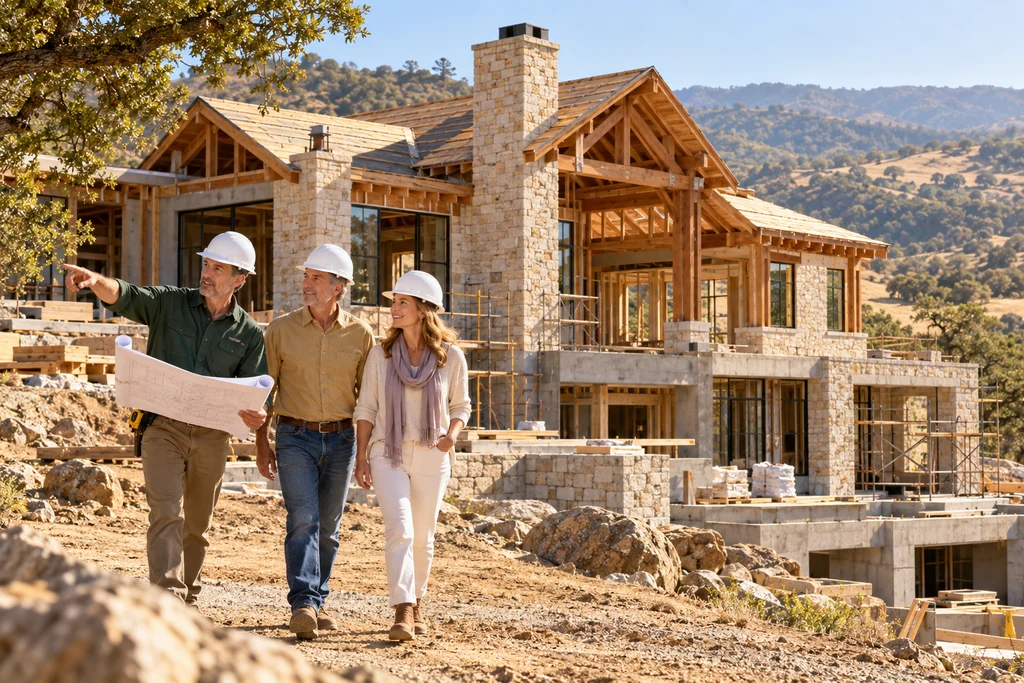
Bring your build, land and permanent financing questions into one thoughtful plan.
Explore Construction Loans
See how a clear lending strategy can support the next chapter you have been working toward.
Visit the Dream Homebuyer HubA thoughtful place to begin
Bring your questions, your home ideas, and the details that matter most to you. In a relaxed phone conversation, we will talk through the financing possibilities and choose a clear next step for your California home purchase.
Explore the places you are considering
Every property and financing plan is different, but these are three places where higher-price home conversations frequently begin. Explore the local guide, then bring your home goals to Amy for a personalized mortgage plan.
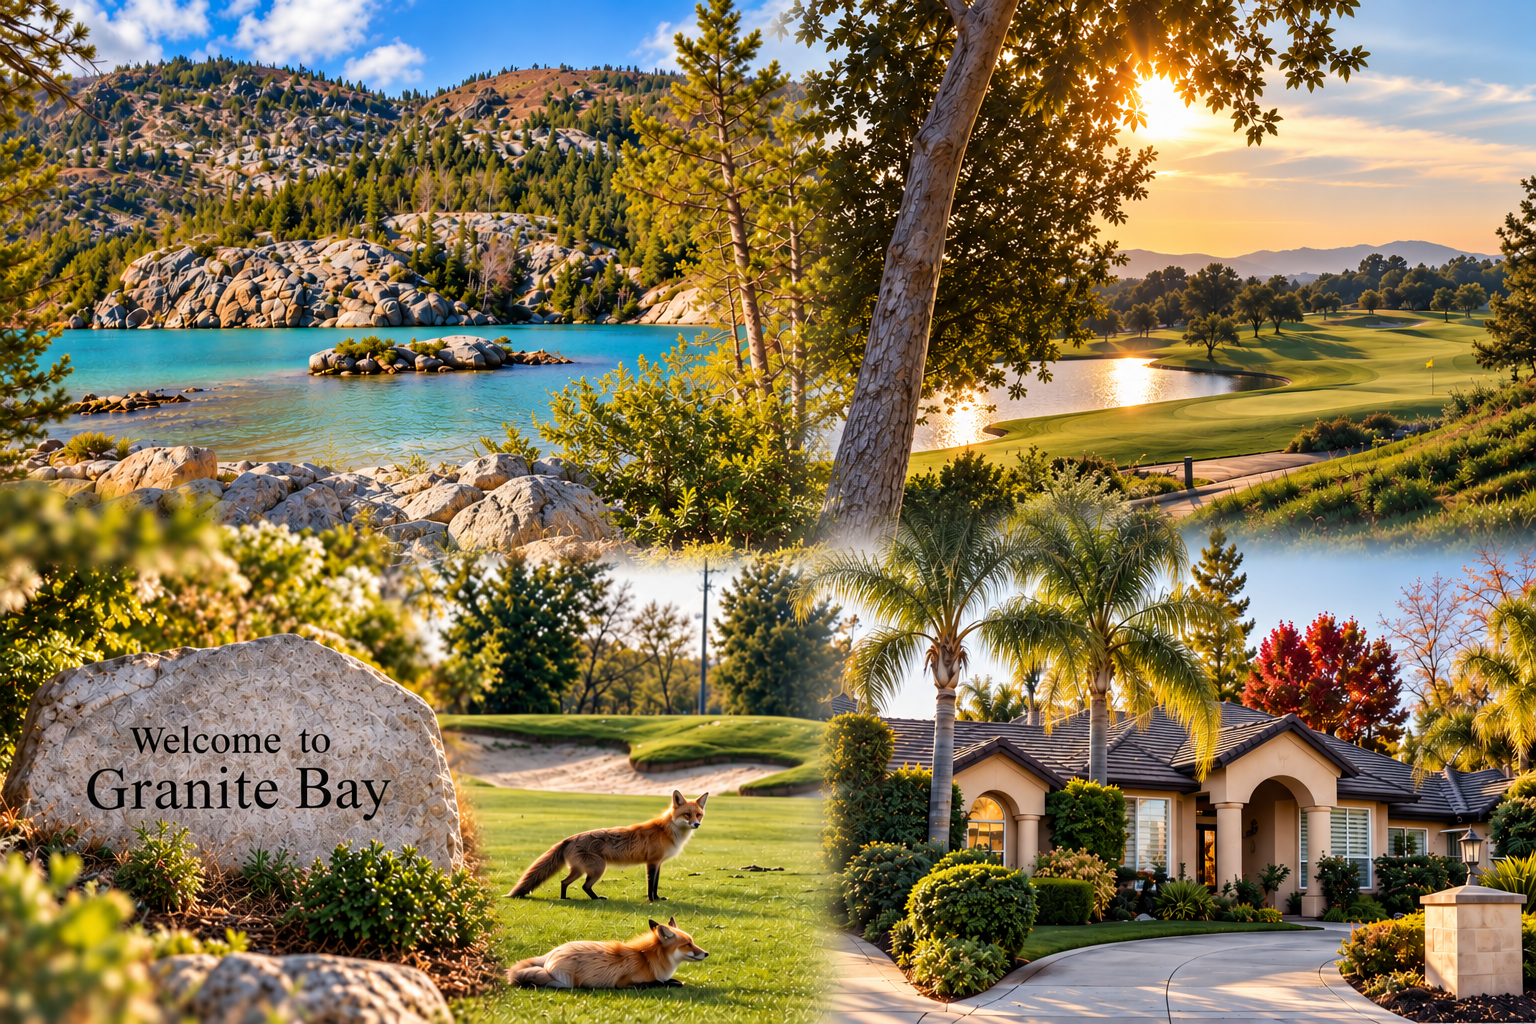
Established homes, larger lots and lake-adjacent living can make a thoughtful financing plan especially important.
Explore Granite Bay home loans
From Silicon Valley to the Peninsula and beyond, a move here often starts with a clear strategy for a higher-priced home.
Explore Bay Area home loans
Primary homes, second homes and Tahoe properties can come with their own questions about the home and how you will use it.
Explore South Lake Tahoe home loansQuestions are welcome
Loan limits depend on the property county, number of units and the current conforming limits. I will review the live limits and your plan with you instead of relying on an old number online.
Down-payment expectations vary by program, property, credit, income, assets and the overall loan profile. We will explore the options available for your specific purchase.
Many self-employed buyers can. The right approach depends on how your income is documented and how the rest of your financial picture comes together. Explore Bank Statement Loans, then we can start with a clear review of your documents and goals.
Reserves are eligible funds you still have after paying your down payment and closing costs. They are usually measured in months of your total housing payment. For many jumbo loans, plan on 6 to 12 months of reserves, although the requirement varies with the program, loan amount, loan-to-value, property, and borrower profile.
Possibly. A VA-backed loan can finance above local conforming levels. Full entitlement, remaining entitlement, lender guidelines, the appraisal and your ability to repay all help determine the right structure.