
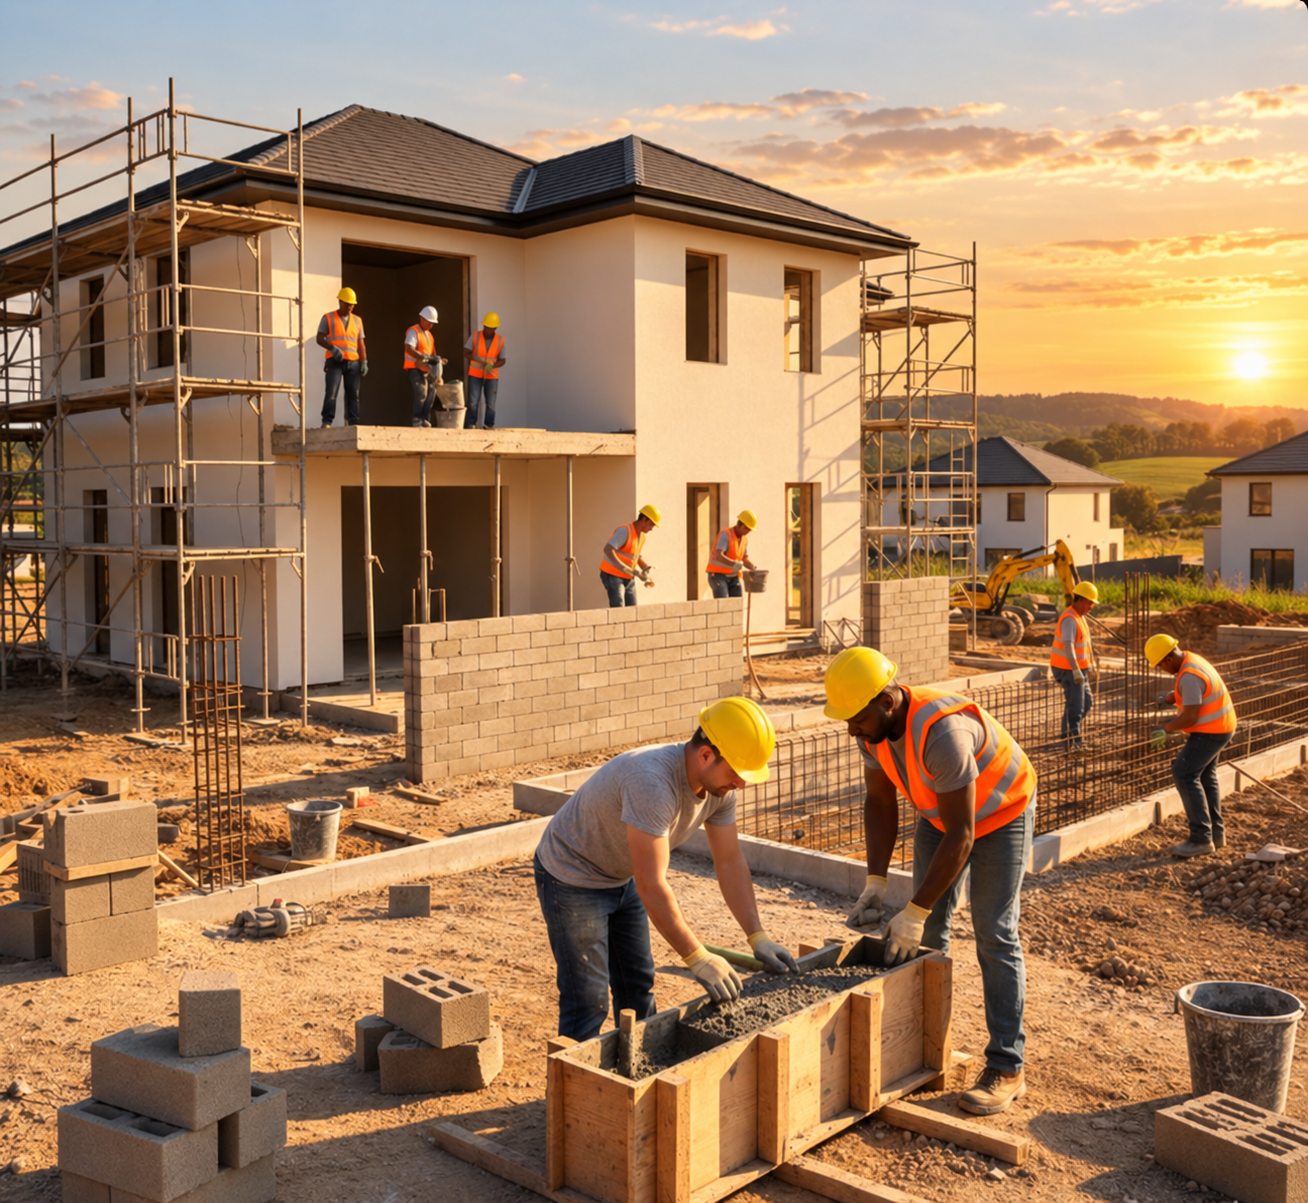
You have a vision for the property. Let us talk through the financing.
You may have been building for years or completed projects using your own funds. Now you are considering how financing could support your next start while leaving room for the responsibilities you already have.
Let’s start with the project, not a loan label.
The site, proposed costs, construction schedule and plan to sell or rent all shape the financing conversation. I can help identify the loan questions to resolve before you build your schedule around funding.
Amy DeBusk | Branch Manager & Mortgage Advisor
Amy DeBusk Home Loans, powered by loanDepot
I want to understand the project you are planning, the experience you bring, and what you want your business to make possible for your family. That gives us a useful starting point for discussing financing options and the questions that need a closer review.
Start with the kind of project you are building
A home built for sale or rental calls for a different financing conversation from a custom home you intend to live in. Explore ground-up construction financing for investors for your next new build. If you are improving an existing property for resale, visit our fix-and-flip loan page.
If this is your own future residence, our custom home construction page is the more relevant place to start. Being clear about the intended use helps us focus on the right questions from the beginning.
Look beyond the amount you can borrow
Available cash, costs during construction, the funding process, and the time needed to complete and sell a home all affect how a loan fits your project. A financing option needs to make sense alongside the work already underway.
Before committing, ask for a clear explanation of the proposed draw process. What work must be completed before a request? Are inspections required? What costs would you cover before reimbursement? How much time should you allow between requesting funds and paying trades?
We can review those questions together. Draw terms and timing need to be confirmed for the specific financing offered; you should not plan around a promised schedule that has not been established.
A closer look at the construction conversation
Watch this short video, then bring your questions about the project, the timing, and the financing details you want to understand.
Plan for more than the best-case timeline
A project can take longer than expected, and a finished home may need more time to sell. Consider what additional carrying costs would mean for your available cash and any other projects. Ask about the loan's maturity date, potential extension terms, and what happens if your original exit plan changes.
If keeping the home as a rental is a possibility, explore our investor hub. Future rental financing needs its own review. It should be evaluated as a possibility, not assumed to be available when construction ends.
Bring the information you already have
Your first conversation does not need a polished presentation. Start with the property or lot, intended use, ownership details, estimated costs, plans, permit status, and expected schedule. Your construction experience, current projects, and available funds will help frame the next questions.
As we review an option, ask about documentation, fees, guarantees, collateral, and cash you would need to contribute. Your legal and tax advisors can help you understand the business and personal implications before you agree to terms.
Your construction financing planning checklist
These are general questions to bring to our conversation. They are not a lender’s application requirements or a promise about a particular draw process.
I'll use those details to help you compare financing structures and identify what still needs confirmation before you plan around a loan. Bring the project team you already work with; my team can coordinate the lender's documentation questions with the appropriate people.
- Property and purpose: What do you own or plan to buy? Will you sell, rent, or occupy the finished home? What zoning, access, utilities, and permit questions remain?
- Scope and cost: What do the plans, contractor estimates, site work, professional fees, and contingency include? What costs might fall outside the loan?
- Your funds: How much cash is needed at closing, during construction, and for reserves? Would other active projects compete for that cash?
- Draws: How are funds requested and released? What work must be complete? Are deposits or stored materials eligible? Who covers costs between payment and reimbursement?
- Inspections and changes: Who orders inspections, what do they cost, and what is needed for a draw? How are changes, delays, cost overruns, and lien documentation handled?
- Timeline: What are the permit, construction, loan maturity, and possible extension dates? What happens if the schedule changes?
- Exit plan: How would the loan be repaid? What if the property takes longer to sell or a future refinance is unavailable? What funds and alternatives could support that situation?
- Terms to review: Ask about interest, fees, collateral, guarantees, prepayment provisions, extension terms, and the conditions required for approval.
Bring what you already know and leave the unknowns as questions. We can identify the specific program details to confirm with the financing review.
Keep your larger goals in the conversation
Growing your business may be one goal. Keeping money available for family needs, avoiding too many overlapping projects, or preparing for retirement may matter just as much. Those priorities deserve a place in the financing conversation.
Visit our investor guides for additional planning resources, or explore private-money financing to understand another option that may be worth discussing. Availability and terms must be reviewed for your particular project.
Questions you may be asking
Is a spec-home loan the same as financing my own custom home?
They serve different purposes. Start by explaining whether you intend to sell, rent, or live in the completed home so we can review the appropriate financing options.
Can we discuss more than one project?
Yes. Bring an overview of your current and proposed projects. Financing availability will need to be reviewed rather than assumed to carry over from one property to another.
What should I ask about construction draws?
Ask how requests, inspections, payments, and upfront costs are handled. Confirm the actual process and timing for the proposed loan before building your schedule around it.