Roseville, CA · NMLS 281056 · Licensed CA, TN, TX (916) 705-2557 adebusk@loandepot.com

Dream Home & Luxury Home Financing

Your dream home. The lifestyle you've worked for.

You've spent years working hard and imagining what comes next. A beautiful backyard oasis. Weekends by the pool. A kitchen made for gathering and thoughtful amenities that make everyday life feel a little more luxurious, with the places you love close by.

Now let's explore how to make that home yours. Whether you're buying a luxury home or building a custom retreat, I'll help you bring the financing together around your vision, your equity, and the life you want to enjoy.

Complimentary 30-minute discovery call

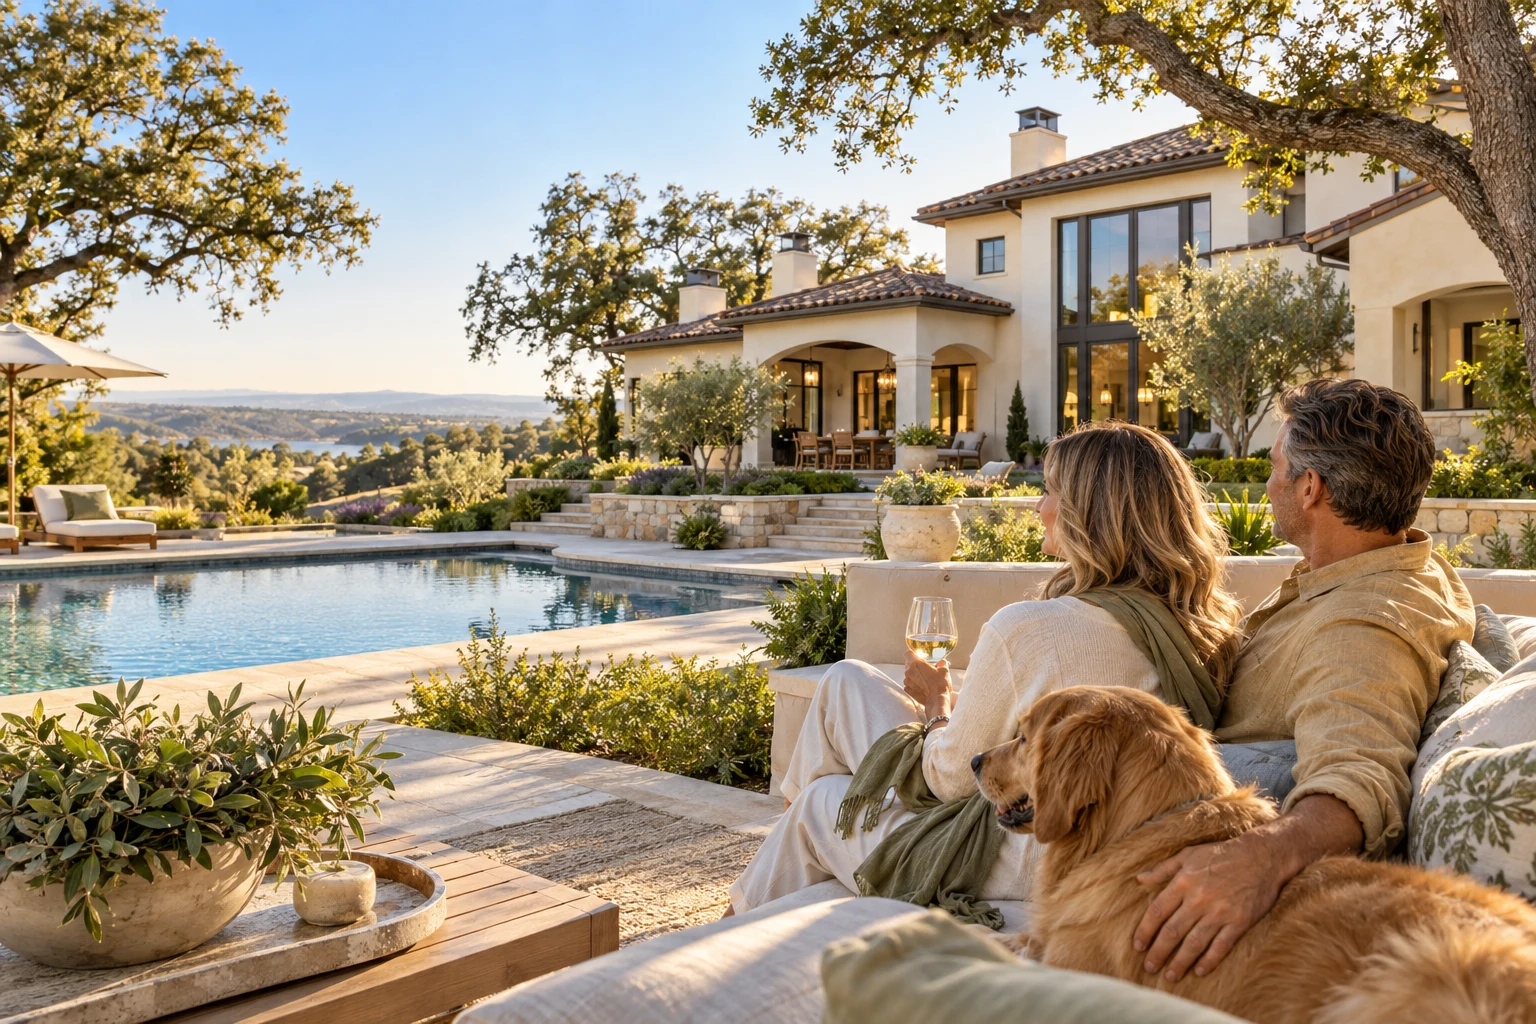
A couple and their golden retriever enjoying a sunny patio beside a pool and a luxury custom home

You don't have to have it all figured out

Looking for a bigger home for a growing family, relocating for a new opportunity, or choosing less upkeep? Those paths may be a more personal starting point. You do not need a luxury purchase to plan a meaningful next home.

Where are you in your next-home journey?

Maybe you're saving pictures of outdoor kitchens and imagining evenings beside your own pool. Maybe you're wondering where you want to live, or how you could buy the home you love when you still have a house to sell. You can begin here, whether your move is months away or you're ready to take the next step.

Still picturing the home you want?

You do not need a finished wish list. Tell me what you own today and what you want your next home to offer. I can help you understand the financing and sale timing before you commit.

Amy DeBusk | Branch Manager & Mortgage Advisor
Amy DeBusk Home Loans, powered by loanDepot

Before we talk about a loan, let's talk about your life. What do you want more of: privacy, space to entertain, beautiful surroundings, nearby amenities, or simply a home that makes everyday living feel easier?

I'm still dreaming

Picture the life, then the home.

You may know the feeling you want before you know the address. Imagine how you would spend an ordinary morning, host the people you love, or unwind at the end of the day. Then sort the must-haves from the beautiful extras.

A covered patio, a pool, a guest suite, a spacious kitchen, or less time spent on upkeep: your priorities are the starting point.

Start with your complimentary planner →

I'm exploring communities

Find where your next chapter belongs.

A dream-home move can be across the state or just a few miles away. A nearby community can bring a different daily rhythm, different amenities, and a new sense of home.

Think about the places you visit often, the people you want close by, your commute, and the activities you enjoy. Visit at different times of day and picture your everyday routine there.

Explore your next community →

I'm ready to plan the sale

Connect the home you own with the one you want.

You may be ready to list but unsure what happens if your home sells before you find the next one. Or perhaps you've found the right home and need to understand how to move before selling.

I'll help you review your equity, estimated sale proceeds, comfortable payment, and timing. Together with your real estate agent, we can compare buying first, selling first, and planning for a temporary overlap.

Explore buying and selling timing →
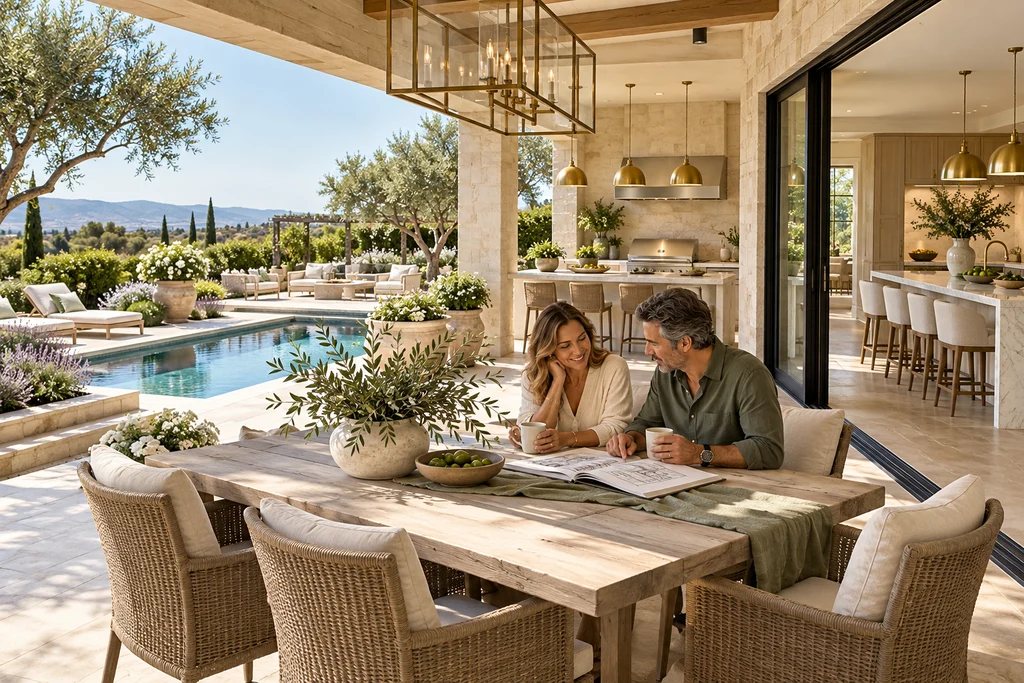
Sunlit luxury home with a covered outdoor kitchen, pool, and inviting patio for everyday living

Luxury is personal

What would make coming home feel extraordinary?

It might be opening your doors to a backyard oasis, having room for everyone around the table, or living closer to dining, recreation, and the people you love. The details that matter to you should guide the search.

You don't need to be ready to make an offer to start a conversation with me. We can begin with your ideas and work toward a plan at your pace.

Let's Talk About Your Next Chapter
Cover of the Dream Home Planner presented by Amy DeBusk

Your complimentary guide

Make space for your dream on paper.

Use my Dream Home Planner to turn the ideas you've been collecting into a clear picture of your next home. Think through how you want to live, what matters most, and the questions you want to bring to our conversation.

Complete it on your own or with the people who will share the home. Bring your wish list, your must-haves, and your questions. I'll help you connect them with your financing options.

Download Your Complimentary Dream Home Planner

PDF · 10 pages · No sign-up required

When you are ready to explore financing

The right financing starts with the way you want to move.

Once we understand your vision, preferred community, and plans for your current home, we can compare the financing that fits. You do not need to choose a loan first. I'll help you connect the options below to your timing, equity, and monthly spending plan.

I'll help you compare the options around your current home, available cash, payment comfort, and how long you expect to keep the next loan. We can work alongside your real estate professional or builder and help you find appropriate connections if your next-home team is not in place yet.

A couple exploring a luxury home while planning their next move

One goal, more than one way to get there

Three ways to buy your next home before you sell.

You've found the home with the backyard, the views, or the community you've been imagining. But your equity is still in the home you own. Does that mean you have to let this one go? Not necessarily. There is more than one way to arrange the purchase, and a dedicated Buy Before You Sell program is only one of them.

I'll help you compare how much cash you have available now, how much equity you expect from your sale, and which payments you can comfortably carry during the transition. Then we can choose the sequence that fits your life.

Option 1 · Purchase now, pay down later

Finance more of the new home, then recast after your sale.

If you have enough eligible funds for the required down payment and closing costs, and can qualify for the new mortgage while still owning your current home, you may be able to buy with a smaller initial down payment. That means financing a larger share of the purchase now rather than waiting to use all your sale proceeds.

After your current home sells, you can apply a portion of the net proceeds to the new loan and request a recast, if the mortgage and servicer allow it. The smaller balance can then produce a lower required monthly principal-and-interest payment, without replacing the loan.

What makes this different: You are using your purchase mortgage and available funds, rather than adding a separate bridge loan or enrolling in a dedicated buy-before-selling program. You still need to meet the down payment, reserve, and qualification requirements for the larger initial mortgage.

What we plan for: The initial payment will be based on the larger balance, and the applicable payments on your current home must be addressed in qualification. A smaller down payment can affect pricing or mortgage insurance. I'll confirm recast eligibility, timing, minimum principal reduction, and fees before we rely on this strategy. Recasting does not automatically remove mortgage insurance.

Option 2 · A coordinated purchase-and-sale program

Use a Buy Before You Sell program.

A dedicated Buy Before You Sell program may help you use existing home equity and arrange the purchase before your home sells. Depending on its structure, it may support an offer without a home-sale contingency or provide a backup purchase arrangement for your departing home.

What makes this different: The program adds a defined process for the home you are selling. Some structures may allow the departing home's mortgage payment to be excluded when qualifying for the new loan, when their requirements are met. That feature is not universal, and I will confirm it for your specific transaction.

What we plan for: Program fees, how much equity is available, the deadline to sell, and what happens if the home has not sold by that deadline. If there is a backup purchase arrangement, we will review how its price is determined and which costs or advances come out of your proceeds. This can be useful when you want a coordinated path into the next home and are comfortable with the program's sale terms.

Option 3 · Temporary financing between homes

Use a bridge loan to access equity before you sell.

A bridge loan is short-term financing secured by real estate that can help provide funds for your next purchase. Depending on the structure, it may access equity behind an existing mortgage or pay off that mortgage as part of the transaction. Your eventual sale proceeds are commonly used to repay the bridge loan.

What makes this different: The bridge loan provides temporary funds, with its own repayment terms, alongside the plan for your new home. It may offer a different sale window than a dedicated Buy Before You Sell program. The key comparison is the actual loan term and costs, not simply the product name. Some buy-before-selling programs also use bridge financing, so these categories can overlap.

What we plan for: Interest, closing costs, equity requirements, the maturity date, and how payments are handled. Some structures require monthly payments; others may use reserves or accrue interest, which still has to be repaid. We will also review how existing debts are treated when qualifying and the options if your sale takes longer than expected. A bridge loan gives you a defined financing window, not unlimited time to sell.

Which path feels right for your move?

Available cash and qualifying income? Buying with a larger mortgage and recasting later may be worth comparing first.

Need a coordinated solution for the departing home? Let's review the Buy Before You Sell program's features, fees, and sale terms.

Need access to equity for the next purchase? We can compare a bridge loan's available funds, carrying costs, and repayment timeline.

I'll put the options side by side using your numbers: cash needed before the sale, payments during the overlap, total costs, and what your mortgage could look like afterward. We'll also compare selling first if that would give you more comfort or leave more equity available for your next chapter.

Let's Compare Your Buying and Selling Options

Read my full guide and real client stories about buying before selling →

After your current home sells

Could a mortgage recast lower your new payment?

If you buy your next home before selling, you may want to put some of the sale proceeds toward your new mortgage afterward. With an eligible loan, a recast lets you make a substantial principal payment and ask the servicer to recalculate the monthly principal-and-interest payment using the smaller balance.

1. Apply the proceeds

You choose how much to put toward the loan after allowing for selling costs, required payoffs, and the cash you want to keep.

2. Request the recast

The servicer reviews eligibility, minimum payment requirements, timing, and any fee. Paying extra principal alone does not automatically reduce the scheduled payment.

3. Reset the payment

An approved recast uses your current interest rate and remaining loan term. Taxes, insurance, and other escrow charges are separate and may change.

A recast is not a refinance and does not lower your interest rate. Not every loan allows it, so I want to check availability before you choose your mortgage. If your goal is a different rate or loan term, we can compare refinancing instead.

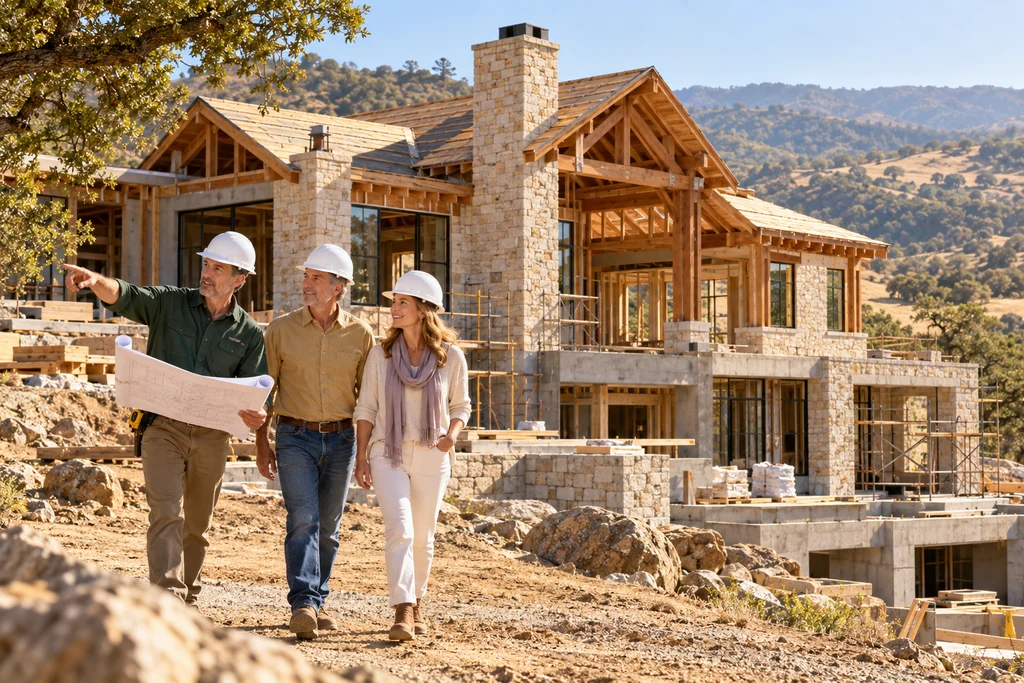
A middle-aged couple and their contractor wearing hard hats and reviewing plans beside their partially built luxury home in the foothills

Designed around you

Build your dream home with a construction-to-permanent loan.

Maybe your dream is a kitchen that opens to the garden, a multigenerational layout, or a home designed for the views. Custom construction financing can help turn a buildable lot and an approved plan into your primary home.

A construction-to-permanent loan finances eligible construction and then transitions to long-term mortgage financing once the home is completed and the required conditions are met. Some structures use one closing; others require separate construction and permanent loans.

Explore Custom Construction Financing

In my jumbo home loan guide, I share a Folsom family’s plan to build in Serrano after a long search. Their example describes a construction and sale strategy they were planning, not a promised or completed outcome.

We plan for the whole project, not just the house.

The review includes your qualifications, the land, approved builder, plans, permits, contract, total project costs, and an appraisal based on the proposed completed home. Funds are generally released in stages as work progresses and inspections are completed.

Site preparation, utility connections, contingency funds, interest during construction, and where you will live while building all belong in the spending plan. If you already own the lot, we'll review whether eligible land equity can contribute to the transaction. If you are still looking, let's discuss financing before you commit to a parcel.

Read my step-by-step custom home construction guide →

Financing a higher-priced home

Jumbo loans give your vision more room.

A jumbo loan is a mortgage above the conforming loan limit for the property's county and number of units. It may be an option when the home you want requires a larger loan than conventional conforming financing permits.

Your down payment, credit, documented income, available reserves, and property all shape the options. I'll compare the total payment and cash needed rather than assume every luxury purchase requires the same down payment.

A fixed-rate jumbo loan offers a stable principal-and-interest payment. Adjustable-rate and interest-only structures may also be available for qualifying borrowers, with different payment risks. Interest-only payments do not reduce principal during that period, and payments can rise substantially when principal repayment begins.

Explore Jumbo Home Loans

Understand the numbers

What is a 7/6 adjustable-rate mortgage?

The 7 means the interest rate is fixed for the first seven years. The 6 means that after the initial period, the rate can adjust every six months. It does not mean the loan is paid off in seven years.

A 7/6 ARM may be worth comparing when the initial terms fit your plans, particularly if you expect to move or pay down the loan within several years. A lower starting rate is not guaranteed. We will compare the available fixed-rate option, closing costs, and how long you expect to keep the loan.

After the fixed period, the rate is generally calculated using an index plus a margin, subject to the loan's adjustment caps and any floor. Your payment can increase. I'll walk you through the first-adjustment, periodic, and lifetime limits and a higher-payment scenario so you understand the commitment beyond year seven.

We should choose a loan you can live with even if plans change. A future refinance depends on qualification, property value, and available rates; it should not be the only way the payment works. Ask me about available conforming or jumbo 7/6 ARM options for your purchase.

Watch at your own pace

Jumbo home loans: how to buy your dream home.

Join me for a closer look at jumbo financing and the questions to consider when buying a higher-priced home. I'll help you connect the concepts in this video to the options available for your purchase today.

Open on YouTube if the player is unavailable

Picture your next address

Dreaming of Los Lagos, Serrano, or your own custom retreat?

Maybe you've pictured a home in Los Lagos in Granite Bay or Serrano in El Dorado Hills. Maybe your vision is a private lot where you can build something entirely your own. I'll help you look at the financing alongside the lifestyle, so your next home makes sense for the way you want to live.

For any property you're considering, we'll include property taxes, insurance quotes, association dues, applicable special assessments, and maintenance in the payment conversation. For a custom build, we'll also review the site and construction plan. The right home should leave room in your spending plan for enjoying life beyond the front door.

Explore my Granite Bay relocation article and Serrano homebuying article for more inspiration.

Your next-home questions, answered.

Can I buy my next home before selling my current home?

Yes, there may be a way to do that. I can review Buy Before You Sell options, bridge financing, or a purchase using other eligible funds. The best fit depends on your equity, ability to qualify, property, and sale timeline. We will plan for the temporary costs of both homes before you make an offer.

Are a bridge loan and Buy Before You Sell the same thing?

They are related, but not interchangeable. A bridge loan provides temporary financing, often using existing home equity. A Buy Before You Sell solution coordinates the purchase and sale and may include bridge financing or other features. I will explain the actual structure, fees, and deadlines of the option we are considering.

Can I lower my new mortgage payment after I sell?

An eligible mortgage may allow a recast after you apply a substantial lump sum to principal. The servicer recalculates principal and interest using the smaller balance, current rate, and remaining term. Minimum amounts, fees, and timing vary, so we should confirm the rules before choosing the new loan.

Does making a large principal payment automatically recast my loan?

No. An extra principal payment reduces what you owe, but ordinarily does not change the required monthly principal-and-interest payment by itself. You need an approved recast for that payment to be recalculated. I can help you identify the questions to ask your servicer.

Do I need 20% down for a jumbo loan?

Not necessarily. Some jumbo options allow less than 20% down for qualifying buyers, while others require more. Loan amount, property type, income, credit, and reserves affect the available choices. I will compare your actual options and the cash you want to keep after closing.

What happens after seven years on a 7/6 ARM?

The initial fixed-rate period ends, and the rate may adjust every six months under the loan terms. The index, margin, caps, and any floor determine the rate, and your payment may rise or fall. We will review the possible higher payment before you choose an ARM, rather than rely on a future refinance.

Can a construction-to-permanent loan cover land and the build?

Depending on the product, eligible land acquisition and construction costs may be included. If you already own the land, its eligible equity may contribute to the transaction. The builder, plans, project costs, appraisal, and your qualifications all need review. Bring me into the conversation early, whether you have a lot in mind or are just beginning your search.

What should I bring to our discovery call?

Start with your goals, preferred timing, estimated current home value, mortgage balance, and the payment range that feels comfortable. If you are building, bring any lot information, plans, or builder estimates you already have. We can identify the documents needed after we talk. You do not need to have selected a house to begin.

Your dream deserves a conversation.

You don't need every detail figured out to take the next step. Tell me what you're hoping for, what you own today, and what you want your next chapter to feel like. I'll help you compare the possibilities and build a practical plan.

Book Time With Amy

Prefer to call or text? (916) 705-2557

Loan availability and terms depend on your qualifications, property, and the selected product. Educational sources: mortgage recasting and adjustable-rate mortgages.