
The Ultimate VA Home Loan Guide
Join me for The Ultimate VA Home Loan Guide. I walk you through VA loan benefits, eligibility, the funding fee, and the questions to ask as you plan your home purchase.
Your VA benefit. Your next chapter.
A backyard for the dog. Room for family. A home that feels like yours. Whether you are buying, improving a home, or exploring a refinance, I will help you understand your VA options and build a plan that fits your life.
A VA loan is a mortgage backed in part by the U.S. Department of Veterans Affairs and made by an approved lender, such as loanDepot. It helps eligible Veterans, service members, and certain surviving spouses buy or refinance a home. You do not have to be a first-time buyer, and your benefit may be used more than once.
For many qualifying buyers, VA financing offers a path to homeownership with no down payment and no monthly mortgage insurance. You still need to qualify for the loan, and closing costs may apply. We will walk through your eligibility, comfortable monthly payment, and the cash you may need before you make a decision.
I'm Amy DeBusk, Branch Manager & Mortgage Advisor with loanDepot. I help homebuyers and homeowners in Roseville, Placer County, Greater Sacramento, and throughout California, Tennessee, and Texas. Visit my Veterans Resource Center or explore the options below.
Tell me what you want your next home or refinance to make possible. My team and I help you review eligibility, understand the paperwork, and compare payment and upfront-cost scenarios. If you have used VA before or are navigating a military transition, we work through those details with you before choosing a direction.
You can start with questions, then move into preparation and pre-approval when you are ready. See how we build your VA homebuying plan together →
Prefer to watch? Explore the VA Home Loan Video Hub ↓
Watch and learn with me
Prefer to watch? Join me for a closer look at your VA benefit, how VA and CalVet differ, and the VA streamline refinance. Start with the topic that matters most to you.
Join me for The Ultimate VA Home Loan Guide. I walk you through VA loan benefits, eligibility, the funding fee, and the questions to ask as you plan your home purchase.
Explore two different paths for eligible Veterans. VA and CalVet have their own requirements, so we will help you compare the details for your situation.
Learn how an IRRRL works and what to consider when comparing your existing VA loan with a new one.
Watch more of my VA videos, or visit your VA Resource Center for articles and tools to help you plan your next step.
Videos provide general education. Program requirements and availability can change; I will confirm the current details for your loan.
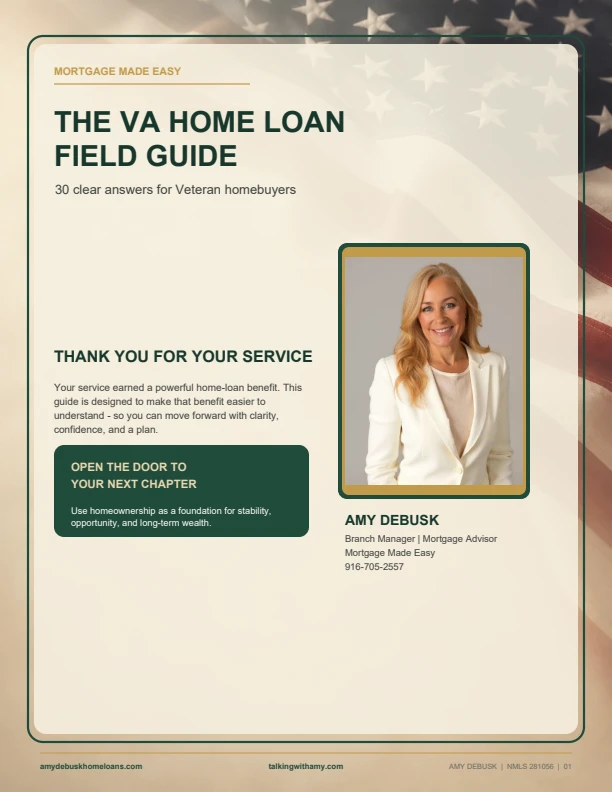
Your complimentary take-home guide
Keep clear answers close at hand. My VA Home Loan Field Guide walks through the questions Veterans and military families ask about eligibility, entitlement, closing costs, appraisals, and refinancing.
Download your copy to read at your own pace and bring your questions to our next conversation.
Free PDF · 12 pages · 3.7 MB
Make your move
A VA purchase loan can help you buy a primary residence with little or no down payment, depending on your entitlement, the purchase price, appraised value, and approval. Eligible properties can include a single-family home, a condo in a VA-approved project, or a two- to four-unit property when you live in one unit. Some manufactured homes may qualify under additional requirements.
I'll help you connect your entitlement, financing, and purchase timing. My team can work with your real estate professional on the mortgage steps, including questions about the home and your move. If you need an agent, we can help you connect with one familiar with VA purchases.
With a fixed-rate loan, your interest rate stays the same for the life of the loan. The scheduled principal and interest payment stays consistent, making it easier to build your household spending plan. Property taxes, homeowners insurance, and any HOA dues can still change.
We can compare available loan terms, including shorter terms and a 30-year option. A shorter term generally means a higher monthly principal and interest payment but less interest over the life of the loan. The right choice leaves room for your other priorities.
High-balance and larger VA loan options are available for eligible borrowers. With full entitlement, VA does not impose a county loan limit on loans over $144,000, but lender limits and qualification requirements still apply. With partial entitlement, county limits can affect how much you may borrow without a down payment. We will review your Certificate of Eligibility before estimating your purchasing range.
Ready to look at homes? Start with home loan pre-approval. We will review your income, debts, credit, and the money left for household expenses after your obligations, which VA calls residual income.
Understand your choices
A VA adjustable-rate mortgage, or ARM, begins with a fixed interest rate for a set period. With a 5/1 ARM, that period is five years; with a 3/1 ARM, it is three years. Afterward, the rate can adjust annually under the loan's index, margin, and rate caps. Your payment can increase.
An ARM may be worth comparing if you expect to move within a few years or want to evaluate the starting payment against a fixed-rate option. We will also show you how future adjustments could affect your payment. Your plan should work even if your move is delayed or refinancing is unavailable.
A fresh look at your existing loan
An Interest Rate Reduction Refinance Loan, often called an IRRRL or VA streamline refinance, replaces an existing VA loan. It may help lower your interest rate or move you from an adjustable rate to a fixed rate. It is not the option for taking cash out of your home's equity.
Many IRRRLs have fewer documentation requirements than a purchase or cash-out loan. An appraisal is not required in many situations, but exceptions and lender requirements apply. You must certify that you currently live in, or previously lived in, the home. This can make an IRRRL worth exploring after a move.
We review your payment history, required waiting period, and the refinance's benefit. Loan seasoning generally includes at least six full monthly payments and a 210-day timing requirement; the exact eligible date depends on your loan history. Applicable cost-recovery rules also need to be met.
Eligible closing costs can often be included in the new balance. That reduces upfront cash but increases what you owe. I will compare the monthly payment, closing costs, time to recover those costs, and total interest. Starting a new loan term can increase lifetime interest even when the payment falls.
Put your equity into perspective
A VA cash-out refinance replaces your existing mortgage with a new VA loan. After paying off the current mortgage and applicable costs, eligible remaining proceeds can be used for needs such as home improvements or other planned expenses. This refinance can also move an eligible non-VA mortgage into VA financing, even when you are not receiving cash back.
This option requires a full review of income, credit, debts, entitlement, and the property, including a VA appraisal. You must occupy the home as your primary residence. Payment history, seasoning, and a qualifying benefit also matter.
The standard program generally allows up to 90% of the home's appraised value for a refinance that increases the loan balance under VA's Type II rules. Separate rules apply to other refinance structures. We will confirm which program fits your existing loan and how much cash would actually remain after payoff and costs.
A cash-out refinance changes the financing on your entire mortgage. It can increase your balance, payment, or total interest. If you use proceeds to pay unsecured debts, those amounts become debt secured by your home. We will help you weigh the new costs against your goals.
See more refinance options and read my VA refinancing article for Roseville and Rocklin homeowners.
Loan-to-value, or LTV, compares the loan balance with the appraised home value. loanDepot's separate high-LTV VA cash-out program offers eligible borrowers fixed-rate financing above 90% and up to 100% LTV, subject to all program requirements. The maximum includes any financed VA funding fee.
100% LTV does not mean you receive the home's full value in cash. Your existing mortgage, other required payoffs, financed fees, and closing costs affect the proceeds. Borrowing closer to the home's value also leaves less equity if you later sell or refinance.
This program has its own loan amount, property, credit, and automated underwriting requirements. Manufactured homes and manually underwritten loans are not eligible under this option. Texas Section 50(a)(6) cash-out transactions are also ineligible. I will confirm availability for your property and location before presenting it as an option.
See the possibility in a home
Sometimes the location feels right, but the house needs work. A VA renovation loan can combine the purchase of an eligible home and approved improvements into one mortgage. For a qualifying buyer, that may create a path to updating a home without arranging a separate renovation loan.
Projects may include flooring, paint, kitchen or bathroom updates, and eligible repairs. The specific renovation program determines the permitted work, project limits, property types, and completion requirements. Larger projects or structural changes need a separate review before you make an offer.
The purchase and refinance guidelines do not automatically apply to renovation financing. We will confirm the current renovation option, contractor requirements, and repair limits for your property. Improvements do not guarantee a particular increase in value.
I explain how eligible buyers may combine a home purchase and approved improvements. We will review your project and the current renovation requirements before you move forward.
Your Certificate of Eligibility (COE) confirms your VA home loan benefit and available entitlement. I can help request or review it. Loan approval also depends on the requirements for your particular product.
VA loans do not have monthly mortgage insurance, but a one-time VA funding fee may apply. The amount depends on the transaction, use of the benefit, and sometimes your down payment. Certain borrowers are exempt, including many receiving VA compensation for a service-connected disability. We will verify your exemption status rather than assume a fee applies.
A zero-down purchase can still involve appraisal charges, closing costs, prepaid insurance, and property tax reserves. Seller or lender credits may help when permitted. A VA appraisal evaluates value and minimum property requirements; a separate home inspection helps you understand the home's condition.
For official details, visit VA's eligibility guidance, entitlement and loan limits, and funding fee information.
No. Eligible borrowers can use the benefit for a first home or a later home. Previous VA use may affect your remaining entitlement and funding fee. We will review your COE and any existing VA loan before estimating your options.
Not necessarily. Closing costs, prepaid expenses, and an appraisal gap may require money of your own. Your entitlement and approval also matter. We will explain the estimated cash to close and any permitted credits before you commit.
The requirements vary by loan type, loan amount, property, and underwriting results. Purchase, IRRRL, high-LTV cash-out, and renovation loans do not all use the same minimum. Let us review your full picture rather than assume one advertised score determines eligibility.
An IRRRL refinances an existing VA mortgage and does not provide equity cash-out. A cash-out refinance can replace a VA or eligible non-VA mortgage and may provide cash after payoff and costs. It requires a fuller income, credit, and property review.
Potentially, yes. Each new refinance must meet the applicable payment history, seasoning, benefit, and cost-recovery requirements. A previous refinance does not automatically prevent another, but the timing and financial benefit must be reviewed again.
An IRRRL may be available if the property has an existing VA loan and you can certify prior occupancy, even if you have since moved out. Additional lender requirements can apply. VA purchase and cash-out loans generally require primary-residence occupancy.
Eligible costs can often be included, subject to the loan type, maximum loan amount, value limits when applicable, and benefit requirements. Financing costs increases the balance and interest you pay. We will compare that with paying costs at closing.
An eligible renovation loan can combine a home purchase and approved improvements in one mortgage. The property, contractor, repair scope, appraisal, and completion plan must meet that program's rules. Ask us to review the home and proposed work before relying on renovation financing in an offer.
Book your complimentary 30-minute discovery call. Bring your questions, your plans, and your current mortgage statement if you own a home. I will help you compare your options, understand the numbers, and choose a next step that feels manageable.
All loans are subject to credit approval, property approval, and applicable VA and lender requirements. Program availability and terms may change. Refinancing may increase your total finance charges.