
What would being closer make possible for your family?
Your plans may bring three or four buyers together: parents who already own a home, adult children buying for the first time, and perhaps a sibling joining the purchase. You are combining more than resources. You are creating a place where several generations can share everyday life while keeping space for their own routines.
There is no single way a family home has to look. It could be one house with separate living areas, a home with a permitted backyard cottage, or a property with more than one residence. We will start with how you want to live, then explore the property and financing choices that support it.
Some family members may bring income to the application, others savings or equity from a home they already own. I will help everyone understand how those pieces can work together. First-time buyers deserve clear explanations, and experienced homeowners may be navigating an entirely new kind of purchase. Bring everyone into the conversation; you do not need all the answers before we talk.
Together when you want to be. Privacy when you need it.
The right layout can make shared living feel natural. Think about separate entrances, bedrooms on the main floor, room to work from home, parking, and a place where everyone can gather.
An accessory dwelling unit, or ADU, may offer independent living space on the same property. A larger house with a private suite may fit just as well. I will help you understand how the property's classification and condition affect the loan before you commit to a particular home.
A few ways families can make a home together
- Parents and adult children: stay close while creating space for each household's routines.
- Siblings or extended family: explore buying together and sharing ownership and expenses.
- Several generations: plan for connection today and changing needs over time.
- Family helping family buy: explore an eligible gift or co-borrower arrangement, even when everyone will not live together.
Build a plan everyone feels good about
Talking through the practical details early gives everyone a clearer picture of what they are saying yes to. I will help you connect the financing questions to the conversations you are already having at home.
I'll help each proposed borrower understand how their income, funds, and existing obligations fit the application, so everyone understands the financing being considered. We can work with your purchase and sale agents, or help you find someone to guide a home search for several generations. Your legal advisor can help with ownership agreements.
- Picture daily life. Who will live there, what space does each person need, and what do you want to share?
- Create a shared spending plan. Include the mortgage, taxes, insurance, utilities, maintenance, and money set aside for repairs. Decide who will contribute and how you will handle changes.
- Clarify the financing and ownership. Being on the mortgage means responsibility for repayment. Being on title means an ownership interest. We will review the loan requirements, and your attorney can help document the ownership arrangement.
- Leave room for life to change. Talk about what happens if someone moves, wants to sell their share, or needs a different living arrangement. A written agreement can help protect both your plans and your relationships.
Co-borrowers are responsible for the mortgage under the loan agreement, not just the share your family informally agrees each person will pay. I will explain that clearly so everyone understands the commitment.
One family vision. Several possible financing paths.
Buying with family is a way of living, not one specific mortgage product. The right loan depends on who is buying, whose income supports the application, who will live there, and the property you choose.
Conventional Home Loans
Compare financing for eligible family co-borrowers and the home you will share.
Explore this loan option →
FHA Home Loans
Explore an FHA purchase with eligible family borrowers and documented contributions.
Explore this loan option →
VA Home Loans
Have military service in the family? Review eligibility, borrowers, and occupancy together.
Explore this loan option →
Jumbo Home Loans
Explore financing when your shared purchase needs a loan above the conforming limit.
Explore this loan option →
HomeStyle Renovation Loans
Consider combining a purchase or refinance with eligible improvements for your family.
Explore this loan option →
FHA 203(k) Renovation Loans
Explore financing for eligible repairs and improvements alongside your mortgage.
Explore this loan option →
Custom Construction Loans
Compare construction options for a new home designed around several generations.
Explore this loan option →
Conventional Cash-Out Refinance
Explore using eligible equity from an existing home toward the next purchase.
Explore this loan option →
Home Equity Lines of Credit
Compare borrowing against available equity while keeping your existing first mortgage.
Explore this loan option →Browse all loan options or plan a remodel for your family.
One shared home can involve several financial starting points. We will map out each buyer's income, existing housing payments, available funds, and role in the new home before choosing a loan.
Selling one home to help buy the next
Parents may sell their current home and bring the proceeds into a purchase with their adult children. We will estimate what remains after the mortgage payoff and selling costs, then coordinate the sale, purchase, and move. If you want to buy first, we can compare buy-before-you-sell options and the temporary payments involved.
Keeping a home and using some of its equity
Another family may want to keep an existing property and explore a cash-out refinance or home equity line of credit to help fund the next purchase. Equity is not the same as cash available to spend: we need to confirm the borrowing amount, costs, and new payment. Borrowing against one home while buying another means reviewing both obligations together, including any change in how the existing home will be used.
First-time buyers and experienced homeowners, buying together
Your adult children may be buying their first home even though you have owned for years. I will explain the process so everyone can participate confidently. We can explore first-time buyer resources and review whether any assistance fits the complete borrower group. One person's first-time buyer status does not automatically make the whole purchase eligible; each option has its own rules.
Can family income or a gift help?
Eligible co-borrower income may help support the application, but each borrower's debts and credit also matter. Contributions from someone who lives in the home are not automatically qualifying income. I will review the documentation and loan options with you.
A documented family gift may help with eligible purchase costs. If you are buying a relative's home, a gift of equity may also be worth exploring. We will distinguish a gift from money that must be repaid and confirm what the chosen loan allows.
What about a home with an ADU or multiple units?
A listing that says 'multigenerational' does not determine its financing category. Permits, legal use, appraisal findings, and the loan's property rules matter. Before you make an offer, let's look at whether it is a one-unit home with an ADU, a two-to-four-unit property, or another arrangement.
Complimentary guides for the home you want to share
Bring these to your next family conversation. Start with your shared vision, then explore remodeling or building if those paths fit your plans.
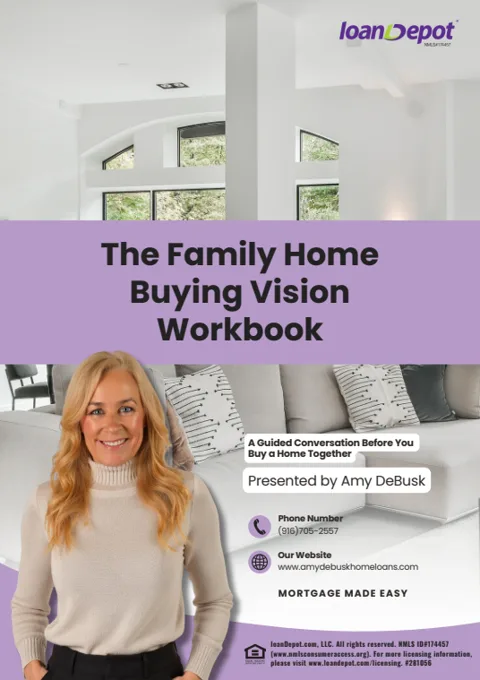
The Family Home Buying Vision Workbook
Start here together: explore the home, privacy, and shared goals each generation has in mind.
Download your complimentary guide
The Remodel Roadmap
Thinking about adapting a home for family? Start organizing your ideas for the space you need.
Download your complimentary guide
The Custom Home Blueprint
Considering a custom home? Explore the planning steps behind a home designed around your family.
Download your complimentary guideBrowse all family homebuying guides or explore ideas with the Family Home Planning GPT.
More ideas and real experiences to learn from
These articles offer a closer look at the questions families bring to me when they are ready to buy together.
Buying a Home With Your Parents
A step-by-step playbook for planning a purchase together.
Read the article →
Buying With Family: Loans, Ownership & Future Plans
Explore financing, shared ownership, and conversations to have before you buy.
Read the article →
Buying a Parent's Home: A Real Family Story
See how one family used a gift of equity in their home purchase.
Read the article →Questions about buying a home with family
Can three or four family members buy a home together?
Yes, a purchase can include multiple eligible borrowers, subject to the chosen loan's requirements. I will review each person's income, debts, credit, and contribution, along with who will live in the home. Combining incomes can help, but we also need to account for everyone's obligations and agree on a comfortable shared spending plan.
Can I buy a home with my parents, adult children, or siblings?
Yes, eligible family members can buy together. I will review who will borrow, who will live in the home, and the income, debts, and funds involved to identify suitable options.
Does everyone living in the home have to be on the mortgage?
No. Living in the home and borrowing for it are different roles. We will determine who needs to qualify for the loan and make sure the occupancy and ownership arrangement meets its requirements.
Can someone help us qualify without living there?
Some loans allow an eligible non-occupant co-borrower. That person takes on mortgage repayment responsibility, and their credit, income, and debts are reviewed. I will help you compare whether that structure fits.
Do we have to contribute equal amounts?
Your family can discuss different contributions, but required funds and ownership must fit the chosen loan and be documented appropriately. A written agreement prepared with legal guidance can address contributions, expenses, and ownership shares.
Can we buy a home with a separate space for our parents?
Yes, there are properties designed for that kind of living. A private suite, permitted ADU, or eligible multi-unit home may work. We will check the specific property rather than assume every separate living space qualifies the same way.
Can we use down payment assistance when buying with family?
It may be possible. Each assistance option has its own borrower, income, ownership-history, and occupancy rules. I will review the proposed household and borrowers before we decide which options to pursue.
What if we already own a home we need to sell?
We can plan the sale and purchase together. Your equity, qualifying income, available cash, and timing will help determine whether selling first, coordinating closings, or exploring a buy-before-you-sell approach fits.
Where should our family start?
Start with the life you want to share, the privacy each person needs, and a comfortable spending plan. Use the complimentary workbook, then book a discovery call. I will help you turn those ideas into practical next steps.
Let's talk about the home your family is imagining
You bring the vision. I will help you understand the financing, ask the right questions, and take the next step with a clearer plan. Your complimentary 30-minute discovery call is a comfortable place to begin.
Have a question now? Call or text (916) 705-2557.