
Tell me what comes next
Share your plans, your timeline, and how your business earns money. You do not need to pick a loan before we talk.
Your self-employed homebuyer hub
You have put your ideas, energy, and dedication into your business. Now let's talk about the home you want, and the financing that can help you get there.
I will help you understand your options, make sense of the numbers, and take your next step with confidence.
Complimentary 30-minute call · 25+ Years of Mortgage Experience
Your goals come first
If you have ever wondered whether your tax returns tell the whole story, or felt unsure how a lender would understand your business, you are in the right place. There are several ways to document qualifying income. My role is to help you understand which ones fit your situation.
Tell me how you earn your income and which records you have. I can explain what a lender may use, what needs closer review and how the financing choices could affect the cash you keep in your business.
Amy DeBusk | Branch Manager & Mortgage Advisor
Amy DeBusk Home Loans, powered by loanDepot
With 25+ Years of Mortgage Experience, I help you turn a collection of financial records into a clear conversation about your home financing options.
Maybe you want your first backyard, an office with a door you can close, room for family, or a home closer to the life you have imagined. Perhaps you already own a home and want to explore your equity. We start with that goal, then build a financing plan around your income, savings, and comfortable spending plan.
Share your plans, your timeline, and how your business earns money. You do not need to pick a loan before we talk.
I review the documentation paths that may fit, explain how income is calculated, and help you compare the full payment and cash needed.
We organize the required records and work toward a supported financing plan, keeping your household and business needs in view.
More than one way to document income
Business deposits are not automatically qualifying income. The review may account for business expenses, transfers, ownership, and the documentation required by the program. We will also consider the working capital you want to keep in your business. The self-employed loan explanation goes deeper into those differences.
Your tax returns, business deposits, 1099 earnings, or eligible assets may support different approaches. These cards explain each option in more detail. I will help you choose based on your finances and the property you have in mind.
Explore 12- or 24-month personal or business statement options for eligible self-employed income.
Explore this option →
An option for established independent earners using eligible 1099 documentation.
Explore this option →
Review an eligible mortgage using the most recent year of personal and business returns.
Explore this option →
Explore qualification using a professionally prepared 12-month P&L statement.
Explore this option →
Learn how eligible assets can support qualifying income, alone or with other income.
Explore this option →
Explore a distinct asset-based approach for a primary-home purchase or rate-and-term refinance.
Explore this option →
Explore a separate home-equity option that may let you retain your current first mortgage.
Explore this option →Visit the Self-Employed Loan Options page → Browse all loan options →
A real self-employed homeowner experience
Being self-employed does not mean your home financing journey ends once you own a home. I helped Jessica and Mike with a bank-statement home equity line of credit, and Jessica shared their experience on Google.
“Amy and her team were attentive to every detail, communicated clearly, and provided top-notch service as always.”
A little preparation goes a long way
You do not need a perfect presentation to begin. Start with the records you already have, and I will help you identify what the selected loan requires.
With your permission, my team and I can coordinate documentation questions with your accountant or tax preparer. They guide your tax decisions; I help you understand how the records fit the mortgage options we are reviewing.
I will confirm the exact documents before you order new reports. If business funds will help with your home purchase, we will review their eligibility and discuss the working capital you want to preserve.
Learn at your own pace
Keep a useful starting point close at hand while you prepare your questions. We will review current requirements together for the option that fits your plans.
Download Your Complimentary GuideExplore your questions
Use the educational GPT tool to explore concepts and prepare questions for our conversation. Leave private financial records out of the chat.
Explore the tool →Keep learning
Find more articles and resources about home financing for business owners and independent earners.
Visit the Resource Center →Watch with me
Explore my videos about self-employed home financing and bring your questions to our next conversation.
Watch the playlist here →Helpful reading for your next step
From my blog
Learn more about documenting business income and preparing for your home financing conversation.
Read the article →
From my blog
Read about bank-statement refinancing and questions to bring when reviewing your current mortgage.
Read the article →Clear answers, a more confident next step
Yes. Business owners, independent contractors, and freelancers can qualify for home financing. I will review how you earn, the documentation available, your debts and savings, and the home you want, then explain the options that fit.
No. A tax-return income review is one starting point, and permitted adjustments may affect qualifying income. Depending on your situation, bank statements, 1099 documentation, a professionally prepared P&L, or an asset-based approach may give us another eligible way to review your finances.
Business-history requirements depend on the selected loan and documentation method. For example, the FLEX one-year 1099 option requires 24 months of being paid through 1099s; the name does not mean only one year of work is needed. Tell me about your timeline so I can review the applicable requirements.
The FLEX bank-statement option includes both, with 12- or 24-month documentation paths. Personal statements and business statements use different calculations, and business expenses matter. I will help you identify which accounts and records support the appropriate review.
Business funds may be usable when they meet the selected program requirements. We need to document ownership, access, and any required review of the effect on business operations. We will also talk about the cash you want to keep available for your business and household after closing.
Each property needs its own review. The lender relies on the appraisal, the use and characteristics of the property, and your intended use to determine eligibility. Having animals does not by itself establish farm use; property-type and acreage limits still apply to the chosen loan.
Yes. We can review refinancing, purchasing another home, and home-equity options. A bank-statement HELOC follows different rules from a first-mortgage bank-statement loan. Tell me whether your priority is accessing equity, changing your payment structure, or planning a move.
Your complimentary 30-minute discovery call starts with your goals, how you earn, and where you are in the process. I will help identify the options to explore and the records to gather. You do not need to know which loan to choose before we talk.
Watch here as you explore your plans. Use the player’s playlist menu to choose another video.
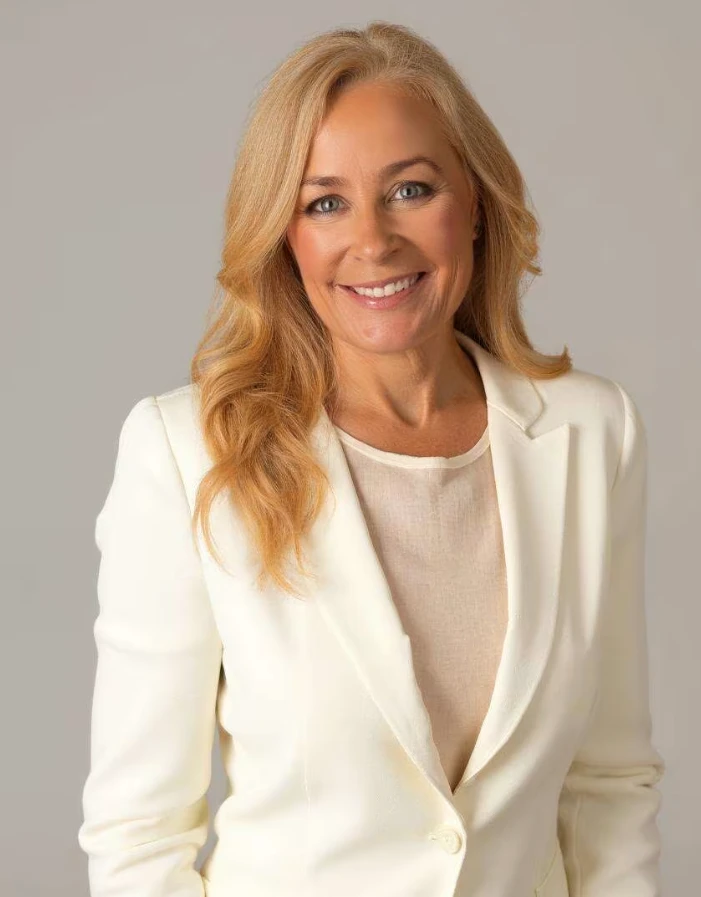
Your plans. My experience.
Let's talk about the life you want your home to support. Your complimentary 30-minute discovery call is a place to ask questions, share your plans, and understand where to start.
Amy DeBusk NMLS# 281056. loanDepot.com, LLC NMLS# 174457. Equal Housing Opportunity. Licensed in California, Tennessee, and Texas. Verify licensing at NMLS Consumer Access (nmlsconsumeraccess.org). · Get to Know Me