With Amy DeBusk
Compare the choices around your life.
I can help you understand the VA financing we offer and organize a useful comparison with CalVet: payment, upfront costs, insurance, property plans, and long-term flexibility. Bring the terms you are considering and the questions that concern you. CalVet administers its own program; its team should confirm its current eligibility and terms. My role is to help you understand your mortgage choices, not assume one program fits every Veteran.
Talk through the questions to compare → · Talk with me about your plans →
Veterans in California have access to two powerful home loan options:
the federal VA Home Loan and the California-exclusive CalVet Home Loan.
Most Veterans know the basics of the VA loan: zero down, no mortgage insurance, flexible guidelines, and unmatched long-term affordability. But many have never heard of CalVet, or they've heard mixed stories about how it works. Some believe it's better. Others believe it's outdated. And some have heard it's harder to close.
The truth?
Both loans can be exceptional tools, depending on your goals, your property type, and your long-term plan.
This guide is your full breakdown: how the two programs differ, when one may be better than the other, myths that create confusion, and how real Veterans are using both to build long-term stability and wealth.
Let's dive in.
The Purpose Behind Each Program
Before unpacking the differences, it helps to understand why these programs exist.
The VA Home Loan Program
Created in 1944, the federal VA loan exists to help Veterans achieve long-term homeownership with:
- Zero down payment
- No mortgage insurance
- Competitive interest rates
- Flexible credit and income guidelines
It is backed by the U.S. Department of Veterans Affairs and is available in all 50 states.
The CalVet Home Loan Program
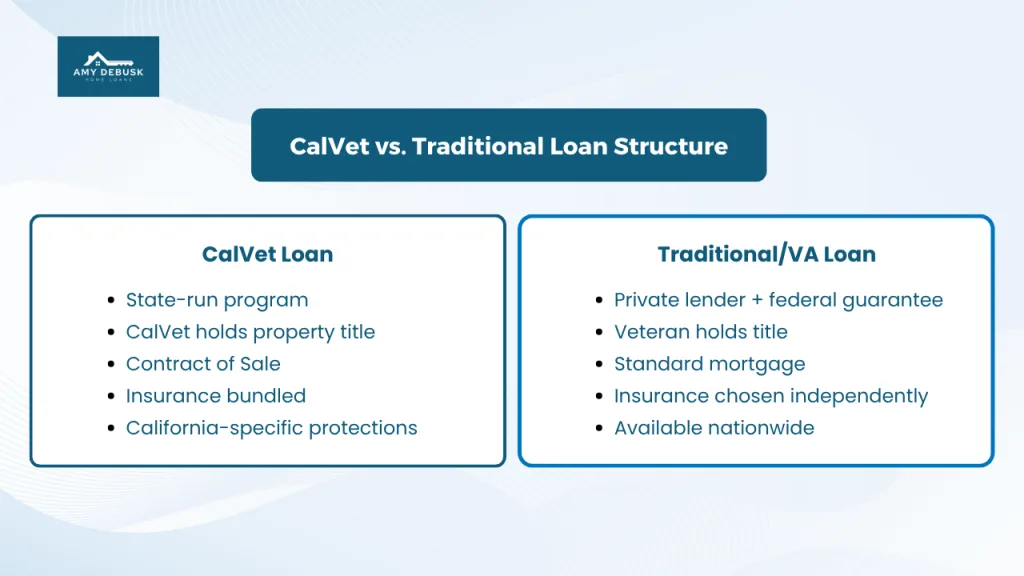
CalVet works differently from traditional lenders and that's exactly what makes it so valuable for California's Veterans.
While the VA Loan Program is federal, CalVet is a California-specific initiative with one mission:
to make homeownership more accessible, affordable, and secure for Veterans living in California.
Unlike traditional loans, CalVet does not operate through banks or mortgage lenders. Instead:
CalVet Holds the Legal Title
Rather than issuing a standard mortgage, CalVet retains legal title to the property until the loan is fully paid off.
This arrangement is known as a Contract of Sale and it gives CalVet the ability to:
Provide bundled, lower-cost insurance options
Offer enhanced protections that traditional lenders cannot
Deliver Veteran-focused benefits unique to California homeowners
This structure allows CalVet to prioritize Veteran stability and support at every stage of the homeownership journey.
Both Programs Serve Veterans, But in Different Ways
VA Loans offer nationwide benefits and flexible financing through private lenders.
CalVet Loans offer state-specific, highly controlled protections tailored to California Veterans.
Both programs help Veterans achieve homeownership, they just take different paths to get there.
Interest Rates: Who Offers the Best Deal?
VA Loans
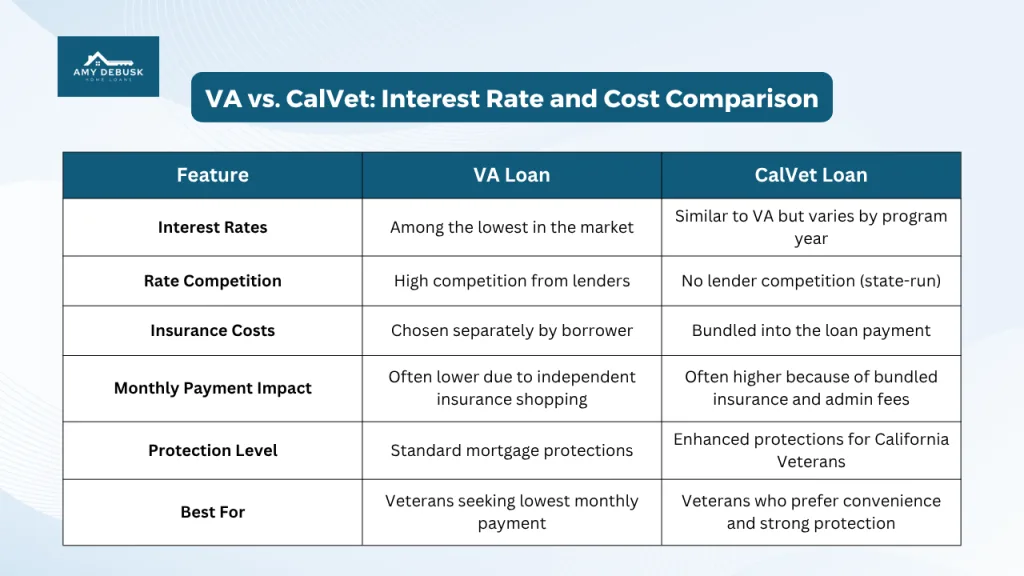
VA loans are often among the lowest interest rate options available.
This is partly because lenders compete aggressively for VA borrowers, which helps keep rates highly competitive.
CalVet Loans
CalVet interest rates are usually similar to VA loan rates. They may be slightly higher or slightly lower depending on the program year.
The real difference is not usually the rate itself but the total monthly cost.
CalVet loans include a comprehensive insurance package, which can increase the monthly payment. Even with a strong interest rate, the overall cost may be higher because the following items are bundled into one payment:
Fire insurance
Disaster insurance
Flood insurance when required
Personal property insurance
Administrative fees
For some Veterans, this bundled protection is valuable and provides peace of mind.
For others, a VA loan ends up being the more affordable option month to month.
Down Payment Rules
VA Loan
- 0% down
- Seller can pay ALL closing costs
- Seller can pay up to 4% of the price toward paying off the Veteran's debts
CalVet Loan
- 0% down on many programs
- Some property types require a small down payment
- Seller concessions vary depending on the property and underwriting
Both programs support Veterans with low or no down payment, but VA tends to be more flexible for seller credits and debt payoff.
Mortgage Insurance
VA Loan
- No mortgage insurance EVER
CalVet Loan
- No PMI
- But… CalVet has administrative fees
- And CalVet requires bundled insurance, which affects the total monthly cost
VA wins here on simplicity and long-term affordability.
Funding Fee vs. CalVet Origination Costs
VA Loan Funding Fee
The VA Funding Fee exists to keep the VA program self-sustaining.
It can be financed into the loan and is waived if the Veteran has a disability rating of 10% or more.
CalVet Loan Fees
- No VA funding fee
- May include CalVet administrative fees
- Insurance premiums can be higher than private insurance
- Total payment can exceed VA even with no funding fee
For Veterans with a disability rating, the VA loan is almost always the better choice because the funding fee is waived entirely.
Property Types: Where Each Program Excels
VA Loan Allows
- Single-family homes
- Condos (VA-approved list)
- 2-4 unit properties
- Manufactured homes (depending on lender guidelines)
CalVet Allows
- Single-family homes
- Manufactured homes
- Mobile homes in parks (unique advantage)
- Farms and agricultural properties (in special programs)
CalVet can actually be more flexible for mobile home parks and certain rural properties.
Insurance Requirements
This is where CalVet is truly unique.
VA Loan
- Veteran chooses their own insurance provider
- Standard homeowners' insurance policy
- Optional earthquake insurance in California
CalVet Loan
Insurance is mandatory and bundled into the loan:
- Fire insurance
- Flood (if required)
- Earthquake (huge benefit for CA Veterans)
- Disaster coverage
- Disability and life insurance options
- Vandalism and malicious mischief protection
CalVet was designed to shield Veterans from the insurance-risk exposure common in California, especially fire zones and earthquake zones.
Appraisal and Property Condition
VA Loans
VA loans include strict Minimum Property Requirements, often called MPRs.
The property must meet three core standards:
Safe
Sound
Sanitary
These requirements help protect Veterans from buying a home that is unsafe or in poor condition.
CalVet Loans
CalVet follows similar expectations regarding property condition. In many cases, CalVet may apply additional guidelines depending on the property type or location.
These extra safeguards exist to ensure the home is safe, insurable, and appropriate for long-term occupancy.
Both programs are designed to protect Veterans from unsafe or structurally compromised homes. However, CalVet may include extra layers of protection to align with state requirements and insurance considerations.
MAJOR DIFFERENCES BETWEEN VA & CALVET
WHO HOLDS THE TITLE?
VA → You hold title.
CalVet → CalVet holds legal title until loan is paid.
REFINANCING OPTIONS
VA → IRRRL, Cash-out, Debt consolidation, Flexible.
CalVet → No cash-out. No streamline. Can only refinance OUT into VA.
SELLER CREDITS
VA → Seller may pay off Veteran debt up to 4% of the price.
CalVet → Seller may NOT pay off debt; credits limited to allowed closing costs.
When the VA Loan Is the Better Choice
A VA loan often makes the most sense when you want:
The lowest possible monthly payment
A waived funding fee because you have a VA disability rating
A condo purchase with fewer complications
Flexibility with seller credits or paying off debt at closing
A home you may sell within a few years
A straightforward refinance option
The simplest and most traditional loan structure
VA loans excel in affordability, flexibility, and ease of use.
When a CalVet Loan Is the Better Choice
A CalVet loan can be the stronger option when you are facing California-specific challenges, such as:
Buying in a fire zone or an area with high insurance costs
Wanting earthquake insurance included automatically
Purchasing a mobile home inside a park
Working with lenders who cannot approve the loan due to insurance limitations
Wanting protection from insurance lapses
Preferring CalVet's Veteran-centered ownership system
CalVet is built to protect California Veterans, especially in high-risk regions where insurance is expensive, limited, or difficult to secure.
Perfect Example: When a Veteran Chooses VA Over CalVet
A Veteran selling their home in Lincoln, CA and moving out of state typically benefits most from using the VA loan, because:
- VA works nationwide
- VA loans offer very low monthly payments
- The funding fee is waived with eligible disability
- Closing costs can be covered with seller credits
- Refinancing options (IRRRL) are much easier later
- The VA loan can be used again and again
This is exactly what your brother experienced.
He sold his home in beautiful Lincoln, California, took the equity he earned, and used his VA eligibility to buy a home in Dublin, Ohio, where he is now semi-retired. Because he used the VA loan program:
- His payment is extremely affordable
- He didn't need mortgage insurance
- His interest rate was competitive
- His long-term cost of ownership stayed low
This kind of financial stability is what the VA loan was designed to create.
VA vs. CalVet (Which Should You Choose?)
Here is the simplest way to understand the difference:
✔ VA loans provide maximum affordability, strong long-term benefits, and broad flexibility. They work well anywhere in the country and are usually the most cost-effective option for California Veterans.
✔ CalVet loans offer powerful California-specific protections, expanded insurance options, and access to property types that traditional lenders may struggle to approve. The tradeoff is a higher total monthly cost.
Neither program is the best choice for every Veteran. The right option depends on factors such as:
Your property type
Your insurance needs
Your location
Your disability rating
Your long-term plans
Your financial goals
Most California Veterans select a VA loan because it provides the lowest monthly payment and the most flexibility.
CalVet becomes the stronger choice when insurance availability or risk makes buying a home difficult, and when the additional protections CalVet provides are essential for securing or keeping the property.
Not sure which program works best for you?
Amy specializes in helping California Veterans navigate every step of the homebuying process with clarity and confidence. Reach out today for a personalized loan review and let Amy DeBusk help you choose the option that protects your budget, your benefits, and your long-term goals.
❓FAQs About VA vs. CalVet
Here are the most common questions we receive, especially around popular programs like VA and CalVet loans.
❓ Do I need to be a California resident to use CalVet?
Yes. To qualify, you must either currently live in California or plan to live in the home you're purchasing in California.
❓ Can I use a CalVet loan and a VA loan at the same time?
Not on the same property. But you can use a CalVet loan now and use your VA loan later or vice versa.
❓ Does CalVet require the VA Funding Fee?
No. CalVet loans do not require the VA funding fee. However, CalVet has its own administrative and insurance costs that often create a higher monthly payment.
❓ Can CalVet be used to buy mobile homes in parks?
Yes, and this is one of CalVet's biggest advantages. VA loans typically cannot finance mobile homes in parks, but CalVet can.
❓ Which program has the lowest monthly payment?
Almost always, the VA loan. Even when CalVet's rate is competitive, the insurance bundle usually increases the monthly payment beyond a standard VA loan.
❓ Does CalVet allow refinancing?
Yes, but not through the typical VA IRRRL. The refinance structure must go through CalVet's approved channels, which can be more limited and less streamlined than the VA IRRRL.
❓ Does CalVet allow seller credits?
Yes, but VA loans tend to be more flexible, especially with the 4% rule that allows sellers to pay the Veteran's debts or closing costs.
❓ Can CalVet be used if I have a VA disability rating?
Yes. Your disability rating does not change your eligibility for CalVet. However, a disability rating may waive the VA funding fee, making a standard VA loan much more affordable.
Explore Our VA Loan Playlist on YouTube
Want to dive deeper into VA loans? Our YouTube playlist breaks down everything you need to know in clear, easy-to-follow videos. From eligibility requirements to funding fees and step-by-step guides, each episode is designed to help Veterans and active-duty service members make confident home-buying decisions.
Get Started Today
- Book a FREE discovery call: talkingwithamy.com
- VA Loan Page: Explore Your VA Benefits
- Mortgage Calculator: Estimate Your Monthly Payment
- Tax Savings Calculator: Calculate Your Potential Savings
All Mortgage Made Easy articles · Book a Complimentary Discovery Call