
Flexible underwriting
Your income, credit history, and circumstances deserve a careful review. I can talk directly with our underwriters, help explain your situation, and explore the flexibility a loan program allows.
More ways to help you get home
A mortgage advisor you trust.
Loan options that fit your life.
You deserve a mortgage advisor who takes the time to understand your finances, explains your options clearly, and stays by your side through the process. My job is to help you find the loan and rate that best fit your needs, using the banking resources available to us.
That is why I chose mortgage banking. At loanDepot, our loan partner and our processor work closely with us and our underwriting team. We have one consistent team, with the same person in each role. If we cannot do your loan at loanDepot, I can shop it with approved outside lenders, compare the eligible options, and explain the differences so you can make a confident decision.
Why it matters for your loan
Your income, credit history, and circumstances deserve a careful review. I can talk directly with our underwriters, help explain your situation, and explore the flexibility a loan program allows.
When timing matters, close teamwork matters too. We work to review documents, answer questions, and resolve conditions promptly. If you need a short purchase escrow or a quick refinance, tell me early so we can plan around your deadline.
You work with one consistent team: Amy, our loan partner, and our processor. We have one person in each role, and those are the same people we work with every day. We know your loan, stay in touch, and work side by side to help you understand what happens next.
Our banking resources give us more places to look for a loan that fits your finances. I compare eligible rates, fees, payments, and requirements, then explain what each option means for you. If we cannot do your loan at loanDepot, I can shop it with approved outside lenders.
Your closing date depends on the loan, required documents, appraisal, title work, and other transaction details. We will discuss what is realistic for your purchase or refinance.
We will check which loans and lenders are available for your property and circumstances.
How I can help you find financing
You should not have to figure out a complicated mortgage process on your own. I help you understand the choices, compare the costs, and find a path that fits your financial needs. We have our lending team at loanDepot and access to 75+ approved outside lending partners when your loan needs another option.
Our loan partner and our processor work alongside us to help gather documents, prepare your file, and keep you informed. We have one person in each role, so you have a consistent team that knows your loan. Our underwriters review the application against the loan requirements. That close working relationship helps us answer questions and keep your loan moving.
If your situation does not fit loanDepot’s guidelines, I can look at approved outside lenders. A different lender may offer the income-documentation approach, property financing, or specialized program you need.
Personal attention when it matters
Perhaps you are self-employed, your income changes from month to month, or something in your credit history needs an explanation. I want to understand your circumstances and help our team understand them too.
At loanDepot, we have an underwriting committee whose job is to review loans that are being turned down and look for a way to approve them within the program’s requirements. I can bring a difficult situation to that team so we can take a closer look at what may be possible.
We can sometimes finance a loan another lender has declined. Different lenders have different requirements, and a careful review of the complete application can make a difference. If another approved lender is a better fit, we can explore that too.
A recent client experience
These clients came to me after a mortgage broker had turned them down. We got them pre-approved, then approved and funded within 19 days.
This is why I value our underwriting team and the ability to ask for a closer review. If you have been told no, I want to understand why and see whether we have an option that works for you.
A recent completed loan.
Your closing schedule will depend on your loan and transaction.
Funded · VA debt-consolidation refinance · Returning client
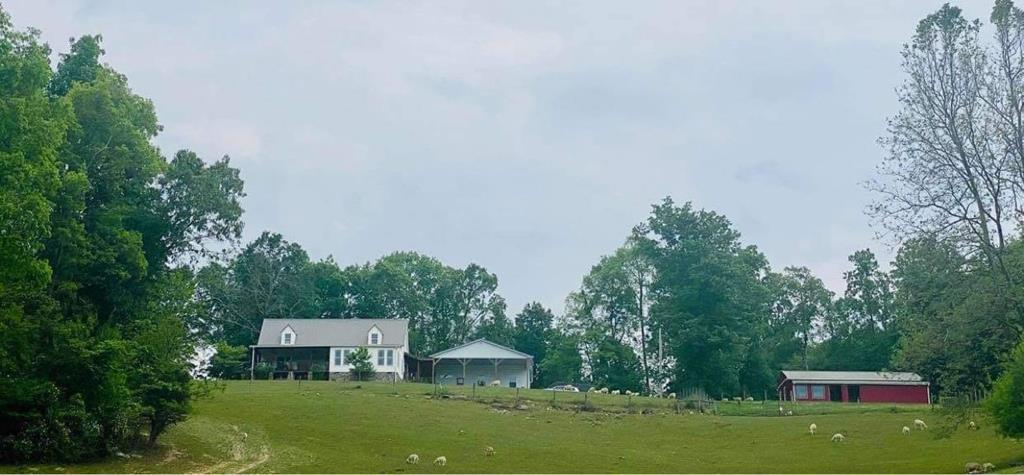
A past client came back to us with a clear goal: consolidate debt and create more room in their monthly spending plan. We helped them use a VA cash-out refinance on their manufactured home to pay off a HELOC on another home they owned and a car loan, while reducing the mortgage’s interest rate from 7.99% to an initial 5.99% on a five-year ARM. Credit challenges and required repairs meant getting there took careful documentation and a team that stayed involved.
Purchased in 2025
The clients bought their manufactured home in 2025 and completed extensive repairs.
Appraised one year later
The later appraisal followed that repair work. This is a comparison of the purchase price and later appraised value, not a measure of market appreciation alone or profit after repair costs.
Putting their equity to work: The refinance provided cash to pay off the HELOC secured by their other home and the car loan. Those balances became part of the new mortgage debt. We look at the new payment alongside closing costs, the repayment term, and the fact that the consolidated debt is now secured by this home.
This is one reason to choose Amy DeBusk Home Loans, powered by loanDepot. We know how to present a complicated file, explain a client’s circumstances, and work closely with processing, underwriting, and committee reviewers. For these clients, that teamwork helped turn a difficult refinance into a funded debt-consolidation loan with a lower initial mortgage rate and meaningful monthly payment relief.
This is a completed client loan, not a current rate offer. Every application is different; recent late payments or a manufactured home do not automatically qualify.
Explore VA financing with our team →Two loans we helped complete
These completed loans show why I value having our own lending team and other approved lenders to work with.
Funded · Our in-house FHA team
This buyer’s FHA loan funded through our team at loanDepot. The purchase price was $600,000, with a $17,000 seller credit.
I share this example because a credit score is one part of a loan application. Income, debts, savings, the property, and the loan requirements also matter. Having access to our team lets me ask questions and help a situation receive a careful review.
Learn about FHA home loans →
Funded · Bank-statement loan with an outside lender
This borrower needed a loan that could work with a specialized income situation. I evaluated three outside banks and compared pricing. The bank-statement loan funded with an approved outside lender.
This is where those relationships can make a difference. I could shop the loan for the borrower, compare the banks whose income-documentation requirements fit, and explain the pricing and options in plain language. The borrower had someone by their side doing that work with them.
Learn about bank-statement financing →These are individual borrower experiences. Your available financing will depend on your application and the lender’s requirements.
Careful attention to your costs
My branch at loanDepot operates as a profit-and-loss branch. That means I am responsible for our branch’s income and operating expenses. I pay attention to how we run our business because I want us to offer competitive financing while giving our clients the care and attention they deserve.
Mortgage pricing changes daily and sometimes during the day. What often changes is the upfront cost or lender credit attached to each available rate. Each loan program and borrower scenario is different, so an online rate alone cannot tell you what is available for your loan. We review your details, research eligible pricing through loanDepot and approved outside lending partners suited to your needs, and explain the product, rate, costs, and full payment together. Our goal is to find competitive financing that fits your finances and plans.
Explore current pricing, rates, and closing costs →Help with loans that can be harder to find
My experience includes bank-statement loans, foreign-national DSCR financing, fix-and-flip loans, and jumbo construction-to-permanent financing.
These loans serve different needs: documenting income, buying rental properties, renovating a home to resell, or building a custom home. Having access to more lenders gives us more options to explore when a standard mortgage does not fit.
Thinking about a second home? Start with our vacation-home loan guide and South Lake Tahoe homebuying guide. You can also explore the communities we serve in California, Tennessee, and Texas.
I focus on the lenders that may be right for you. I do not send every loan to every partner. We consider the requirements, rate, fees, service, and closing schedule together.
Our approved relationships include participating credit unions. Their offers through this channel may differ from direct member offers, so it is worth comparing the actual loan proposals.
Let’s start with what matters to you
“My value is helping you understand your choices and find a loan that fits your life. I want you to feel comfortable asking questions, confident in your decision, and supported from our first conversation through closing.”
You are welcome to ask
I am Amy DeBusk, Branch Manager & Mortgage Advisor with loanDepot, NMLS 281056. You can check my licensing and read what clients and others have shared about working with me.
More about my credentials and reviews →Questions you may have
Through loanDepot, eligible loans can be originated, processed, underwritten, and funded in-house. You work with Amy, our loan partner, and our processor, with the same person in each core team role. We also have access to 75+ approved outside lending partners. We research eligible loan options and pricing suited to your needs, then explain the product, rate, costs, payment, and closing plan. If your scenario does not fit loanDepot’s guidelines, an approved outside lender may offer another option. You have an experienced advisor and a consistent team doing that work with you.
Our underwriters review the complete application. LoanDepot also has an underwriting committee dedicated to reviewing loans facing a turndown and looking for a way to approve them within the program’s requirements. I can bring a difficult situation to that team for a closer look.
Tell us your deadline early. You work with one consistent team: Amy, our loan partner, and our processor, with the same person in each role. Working closely together and communicating with underwriting helps us resolve questions and work toward short purchase escrows and timely refinances. We review the loan, required documents, appraisal, title work, and other conditions with you, then discuss a realistic closing plan.
I can look at approved outside lenders that may have a program suited to your income, property, or other needs. For one funded bank-statement loan, I evaluated three outside banks and compared pricing before the loan closed.
I start with your financial needs, comfortable payment, and plans for the property. I compare the eligible loan options, rates, fees, requirements, service, and closing timeline among lenders suited to your situation. Then we talk through the differences so you understand your choices.
Yes. Bring the written offer or Loan Estimate. We can look at the loan type, rate, fees, credits, monthly payment, and closing requirements together. Participating credit unions are also part of our approved outside lending relationships.
There may be another option. Recent clients came to me after a broker had turned them down. We got them pre-approved, then approved and funded within 19 days. Bring the reason for the decision and the documents you have so we can discuss your situation. That completed loan is an example, not a guaranteed approval or timeline.
Yes, we can review whether a VA cash-out refinance fits your property, credit history, and goals. In one funded debt-consolidation case, returning clients used their manufactured home’s equity to pay off a HELOC on another home and a car loan. Property repairs and inspections took three months, and a new mortgage late shortly before closing required manual underwriting and committee review. Our team documented the circumstances, the committee approved the loan, and it funded. Consolidation moves debts into your mortgage; we explain the payment, costs, repayment term, and the home securing that debt. Approval depends on the complete application.
I would love to hear what you have in mind
Tell me what you want to accomplish and what matters to your household. We will talk through your finances, answer your questions, and explore the loan options that could work for you.
Book Your Free 30-Minute Discovery CallGeneral lender and broker definitions: Consumer Financial Protection Bureau. HUD’s FHA credit-score explanation.
Loan options and completed-loan details confirmed with Amy DeBusk on November 15 and 17, 2026. Borrower names and addresses are not shown. The VA case-study property photograph is from the listing for 739 Tattle Branch Road, Chilhowie, Virginia, credited to Maria Peake / Godwin Realty LLC via Redfin. It illustrates the property type and is not the client’s home. The funded-story lifestyle images illustrate homeownership and do not show the borrowers described. The family arriving home and couple carrying moving boxes photographs are from Amy’s existing licensed iStock collection: assets 1618677014 and 1014814254. The Sacramento suburban neighborhood photograph is by Stephen Leonardi / Pexels, used under the Pexels License. Photos also include Amy’s supplied portrait and a real kitchen-signing stock photograph identified as iStock image 973890860, shown as an illustrative lifestyle image rather than a client photograph.