Roseville, CA · NMLS 281056 · Licensed CA, TN, TX (916) 705-2557 adebusk@loandepot.com
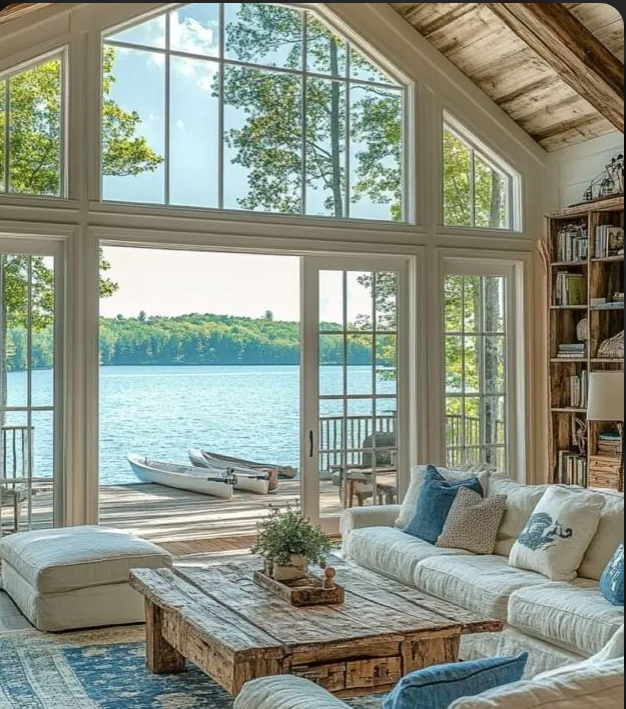
Bright lakefront vacation home with a calm water view

SECOND-HOME FINANCING

A place to exhale, and a plan to make it yours.

A lake house, mountain escape, or place near the people you love can become part of your everyday story. Amy helps you see the full picture before you make an offer: the cash needed, the payment you can carry, and the loan that fits the home.

START WITH THE PURPOSE

What makes a home a vacation home?

The reason you want the home matters. Maybe you want to be closer to family, spend more weekends by the water, have a favorite mountain town within reach, or create a place your family returns to year after year. That personal use is part of what separates a second home from an investment property.

A second home is a home you plan to enjoy yourself.

It is not a property you intend to rent out as your primary business. For many conventional programs, a second home is typically at least 100 miles from your primary residence, unless it is in a recognized vacation or resort area. The exact property and loan-program rules still need to be confirmed before you write an offer.
10% down

Some qualified buyers can start here, subject to loan amount, property, credit, and program limits.

20% down

Often brings meaningfully better pricing and can give you more flexibility in the options we compare.

Two payments

You generally need to qualify for the proposed vacation-home payment as well as your primary residence.

DESTINATION MATTERS

Begin with the places that already feel like yours.

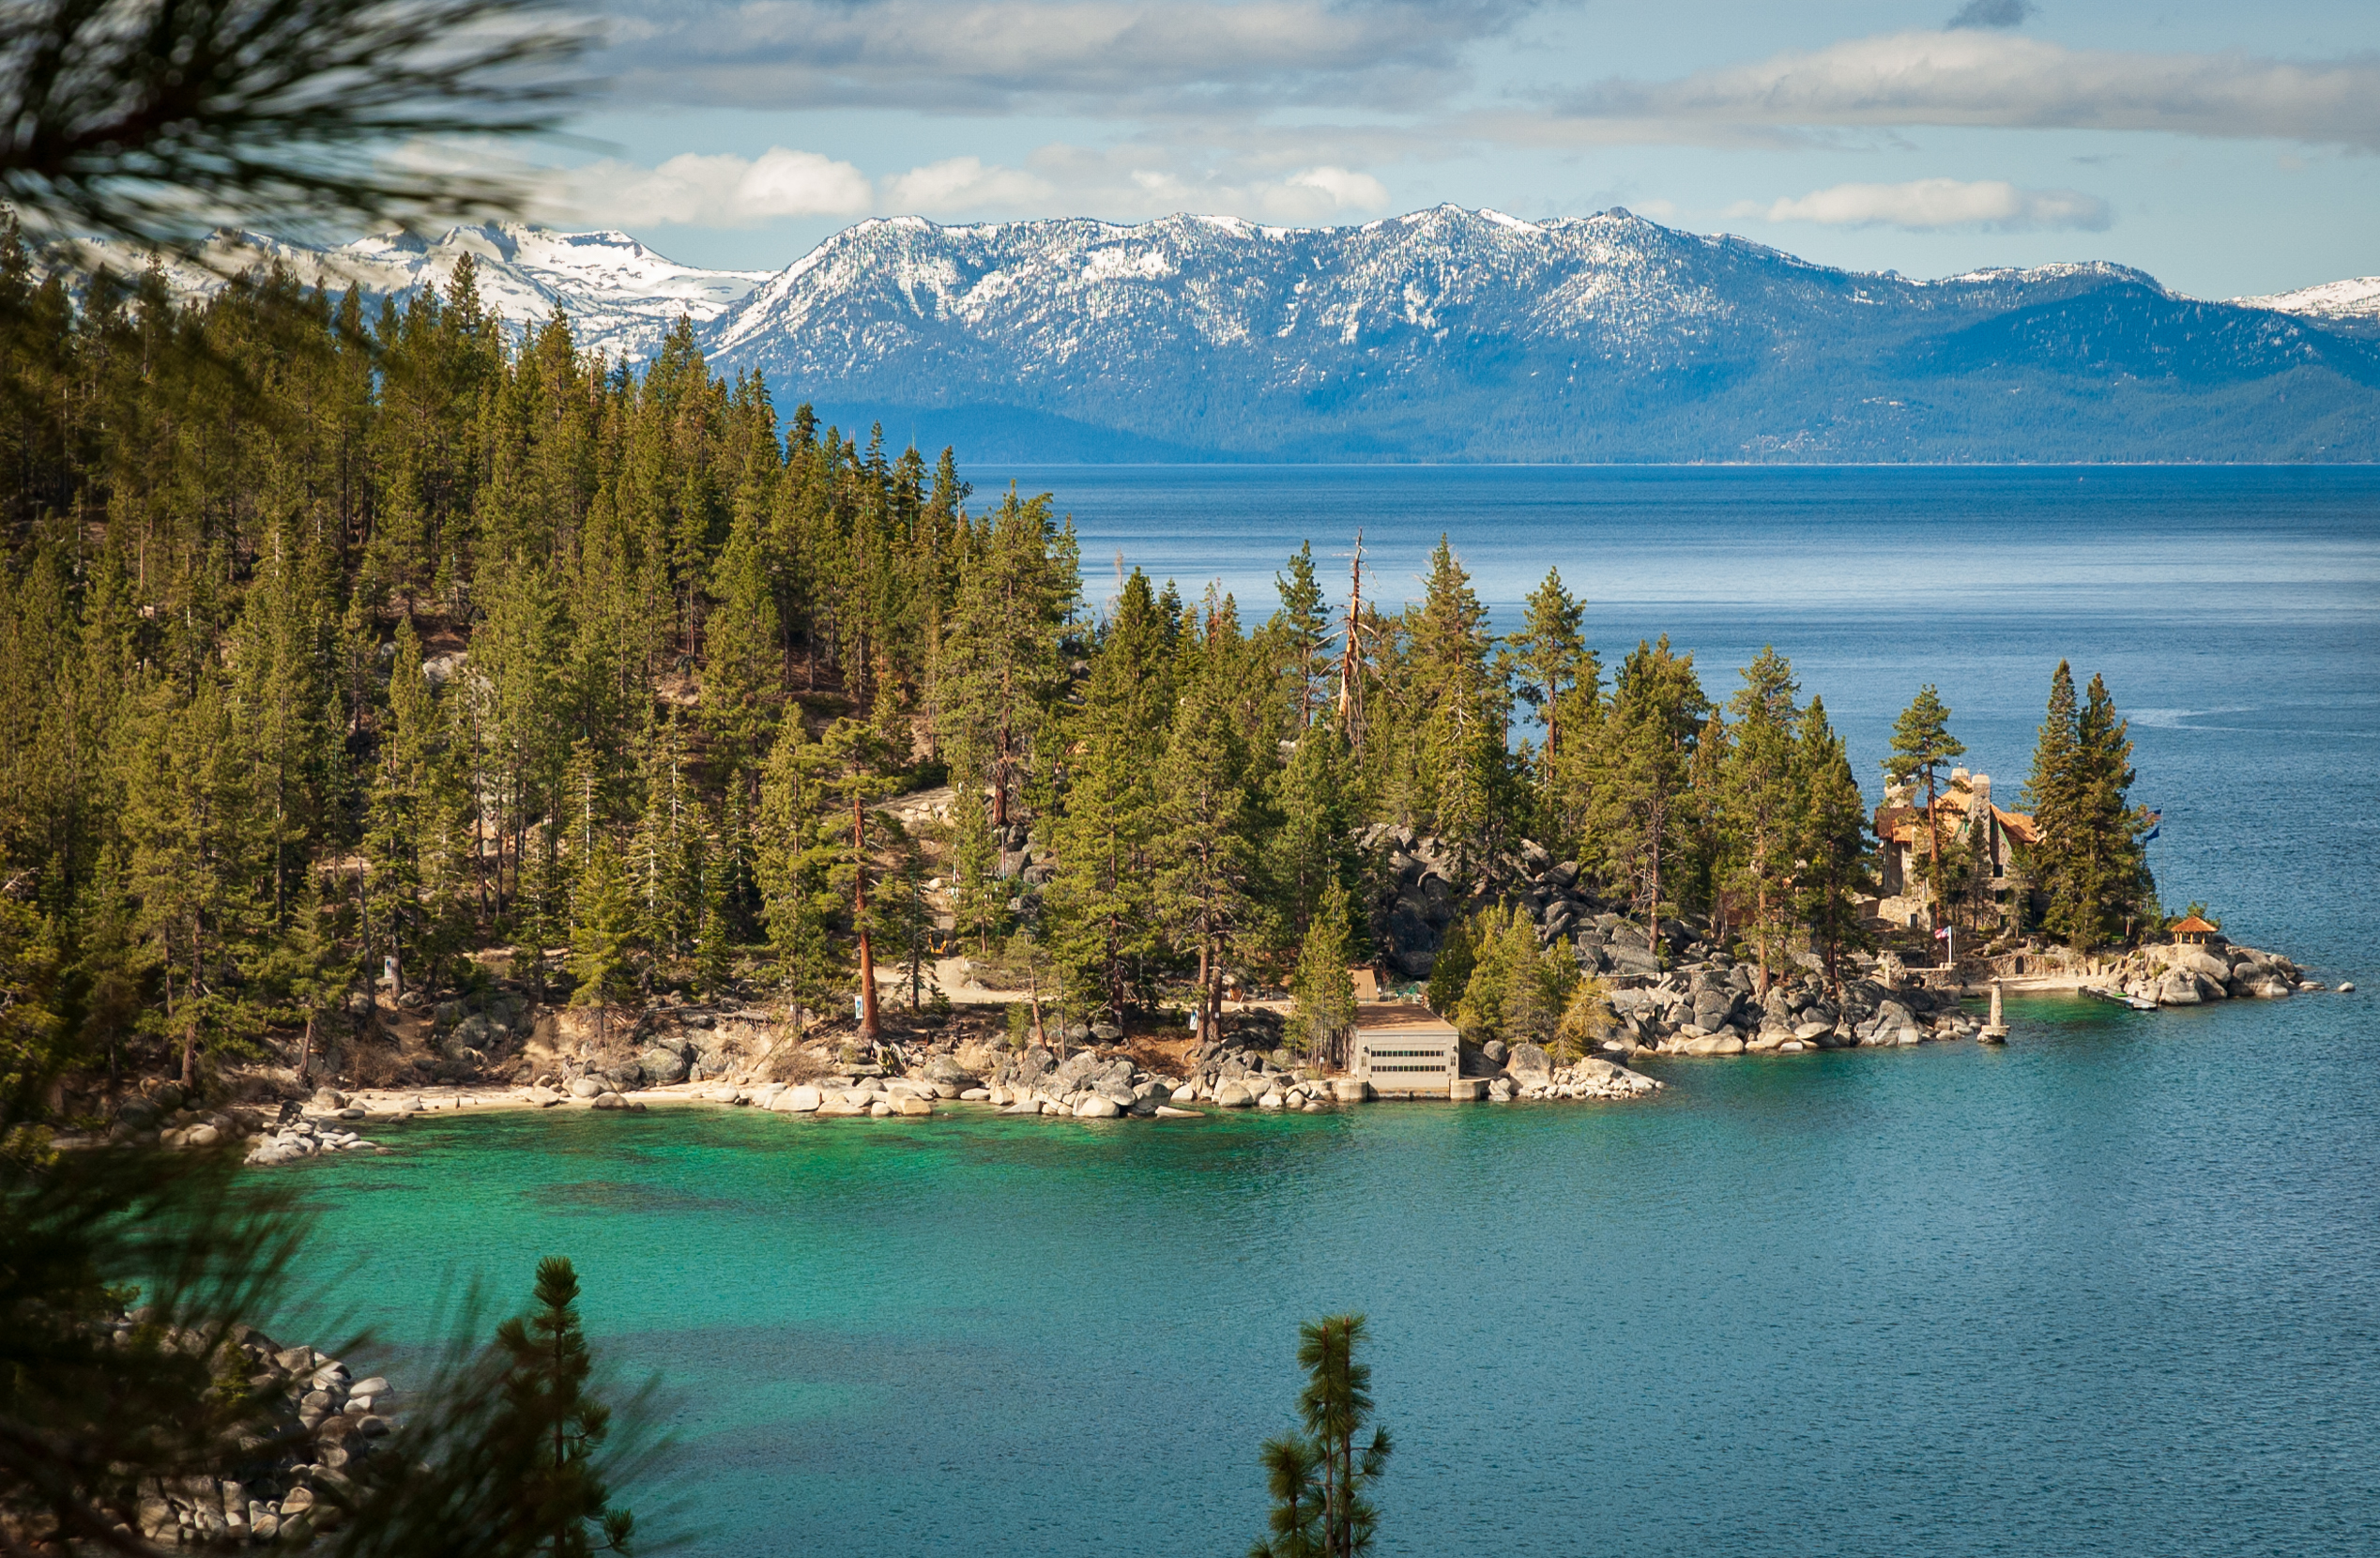
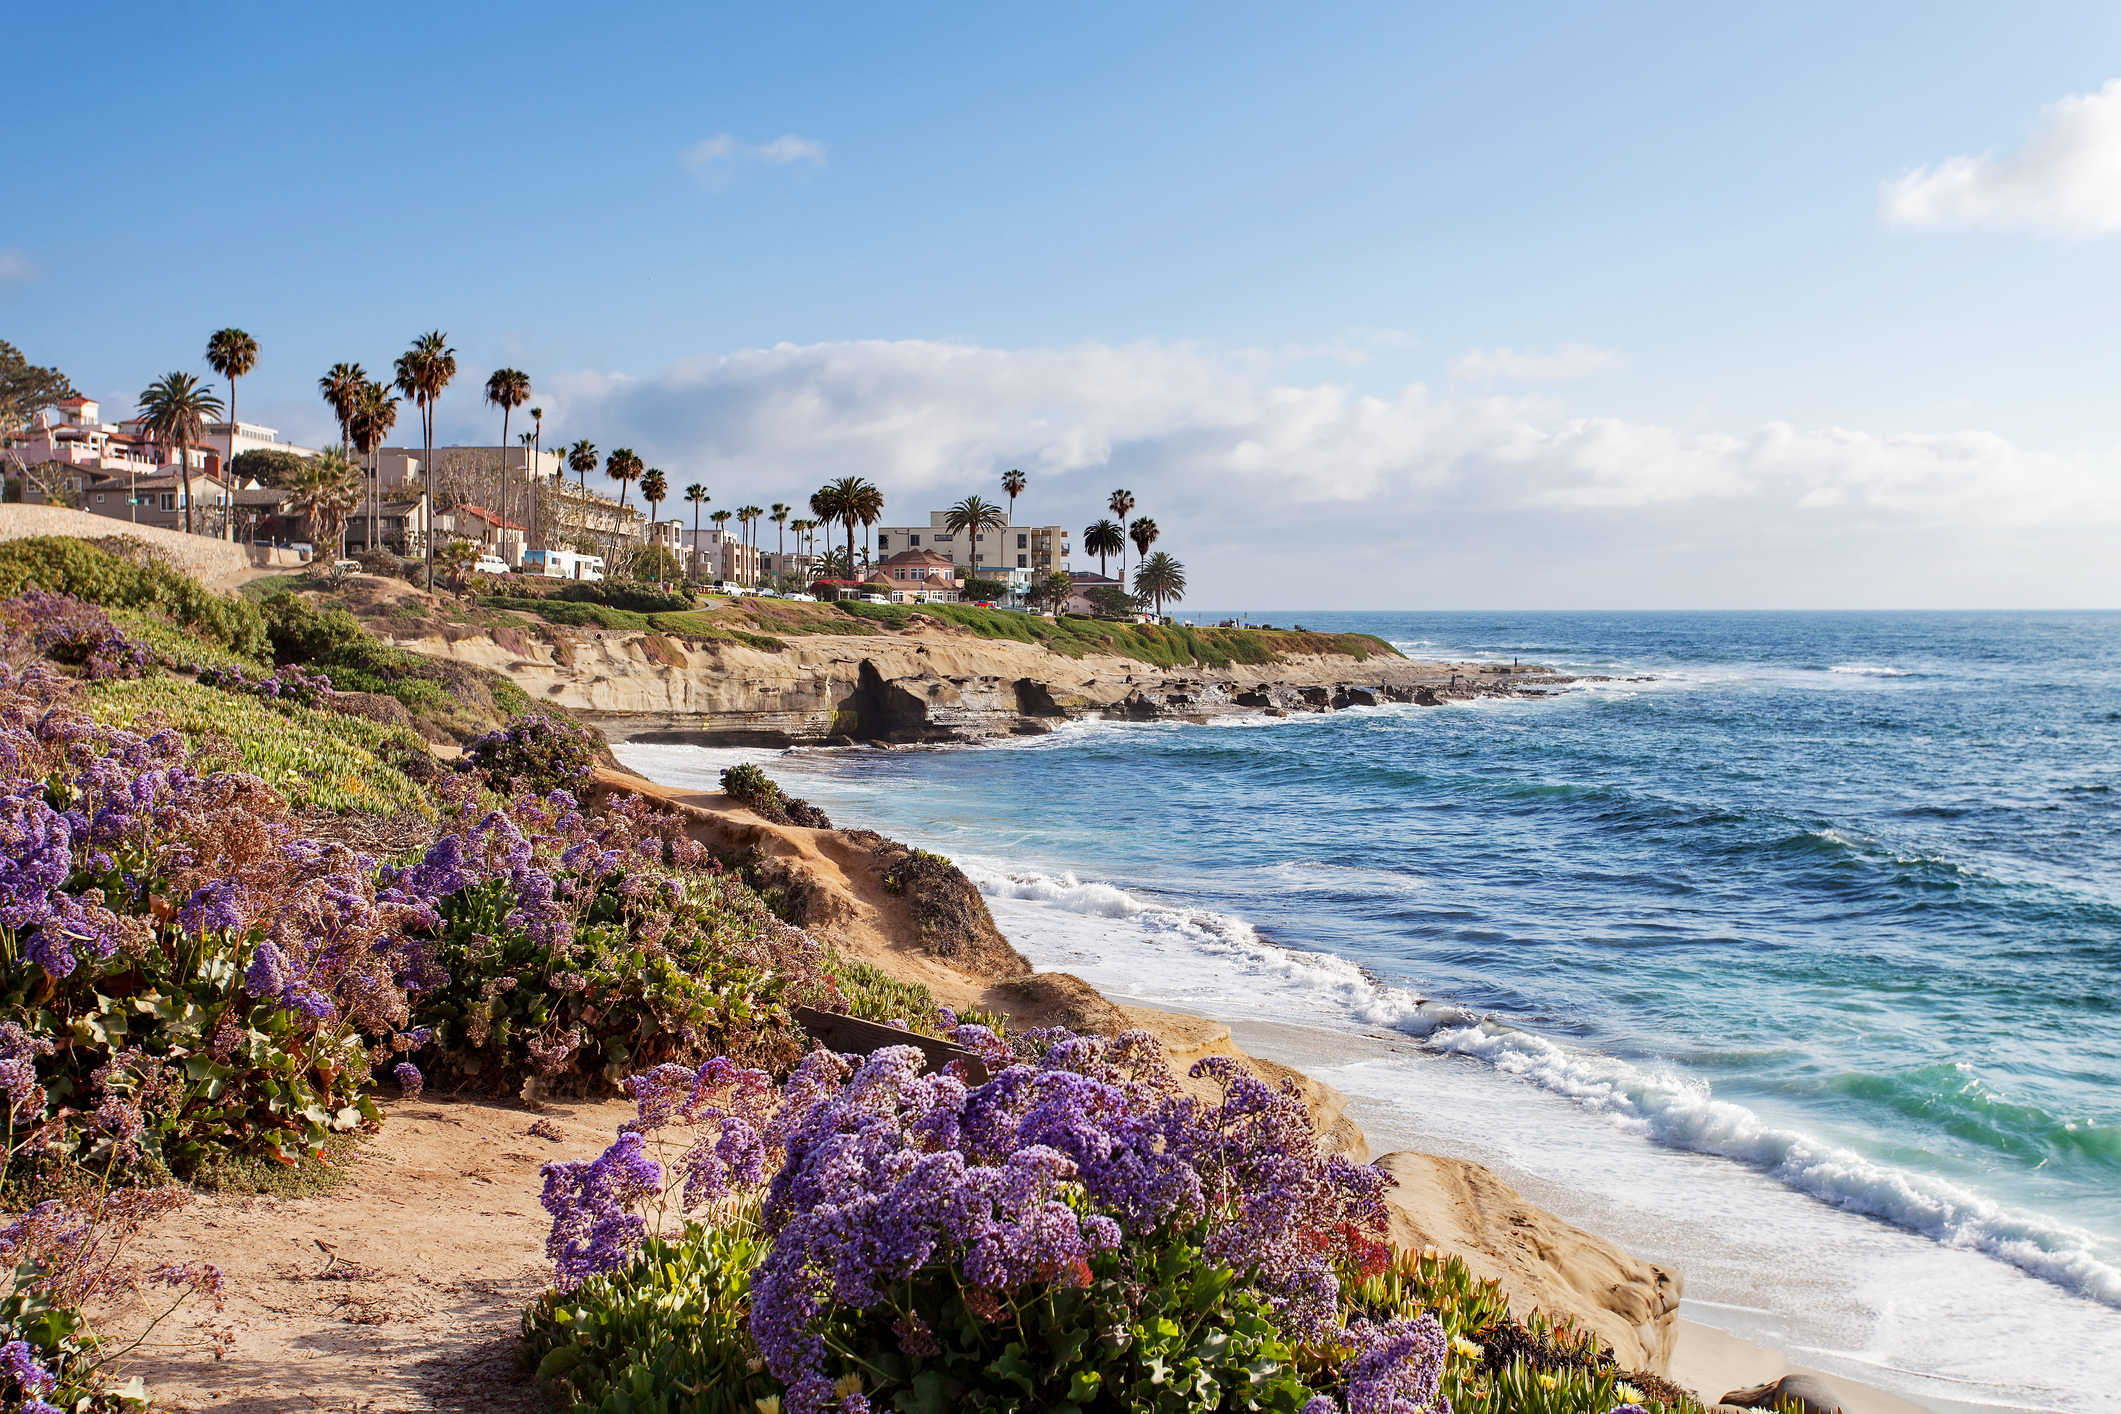
A vacation home can be closer than you think when it supports the way you want to spend time. South Lake Tahoe and Southern California each bring their own property, insurance, and financing questions. Explore the area before you fall in love with a specific address.

BEFORE YOU MAKE AN OFFER

Build the payment around real life.

Before you make an offer, Amy will help you look beyond the principal-and-interest payment and understand the economics of the home you are buying.

  • Insurance firstGet an insurance quote early, especially for mountain, lake, coastal, or wildfire-prone properties.
  • Two-home comfortMake sure the combined payment leaves room for travel, upkeep, family time, and the life you want to enjoy there.
  • Property detailsReview HOA dues, rental rules, taxes, access, and maintenance needs with the exact address in hand.

COMMON QUESTIONS

Vacation-home questions, answered.

Do I need 20% down to buy a vacation home?

Not always. Some qualified buyers may have options starting at 10% down, subject to program, loan amount, property, credit, and other requirements. A 20% down payment can often improve pricing, so we will compare both paths using your actual numbers.

Do I have to qualify for both my primary home and vacation home?

Usually, yes. Your qualifying review generally includes the proposed vacation-home payment and the payment on your primary residence, along with your other monthly obligations. We will look at the full monthly picture before you shop.

How far away does a vacation home need to be?

Many conventional second-home guidelines look for a property at least 100 miles from your primary residence, unless it is in a recognized vacation or resort area. The exact program and the property’s location determine how it is evaluated.

Can I rent out my vacation home?

Rental use can affect how a loan is classified. Before you rely on rental income or plan regular short-term rentals, let’s review the program rules, local requirements, and the property’s HOA policies for that address.

LET'S PLAN THE GETAWAY

Your favorite place can become part of the plan.

Bring the area you are considering, the price range, and the reason this home matters to you. Amy will help you understand the financing before you make an offer.