With Amy DeBusk
Let’s see what a refinance would actually change.
Bring your current mortgage statement and tell me what you want to improve. I help compare the existing loan with a proposed refinance, including costs, payment, loan term, and the time it may take to recover the costs. If you need money from your equity, we will discuss that separately from an IRRRL. The goal is a decision you understand, including when keeping your current loan may make more sense.
Prepare your refinance questions → · Talk with me about your plans →
How Veterans Can Lower Their Payment, Access Better Terms, and Build Long-Term Wealth Through Smart Refinancing Strategies
The VA Home Loan is one of the most powerful benefits our country offers to the brave men and women who serve. Many Veterans know they can buy a home with zero down and competitive interest rates, but fewer realize just how much power the VA gives them after they become homeowners - especially when it comes to refinancing.
This guide is a deep dive into VA Refinances, including the highly popular VA IRRRL, the VA Cash-Out Refinance, how refinancing affects eligibility, how your equity works with VA loans, and how Veterans use these tools to strengthen their financial future.
And to bring this to life, I'm sharing the story of my brother, a retired Army Veteran, who has used his VA home loan multiple times - including his most recent move from beautiful Lincoln, California to Dublin, Ohio. Thanks to his VA benefits, strategic planning, and the equity he built over the years, he was able to secure a comfortable, affordable home loan that supports the next chapter of his life.
Let's dive into everything you need to know.
What Is a VA Refinance?
A VA refinance is a home loan that replaces your existing mortgage with a new VA loan - often with better terms, a lower rate, or a better payment structure.
There are two main types of VA refinances:
1. VA IRRRL
Interest Rate Reduction Refinance Loan
(Also known as the "Streamline Refinance.")
2. VA Cash-Out Refinance
Allows you to take equity out or refinance a non-VA loan into a VA loan.
Both programs share the same foundation:
✔ Only available to qualified Veterans, Active-Duty Service Members, and eligible surviving spouses
✔ Backed by the Department of Veterans Affairs
✔ Designed to make long-term homeownership more affordable and sustainable
But they are used for very different situations.
Let's break them down.
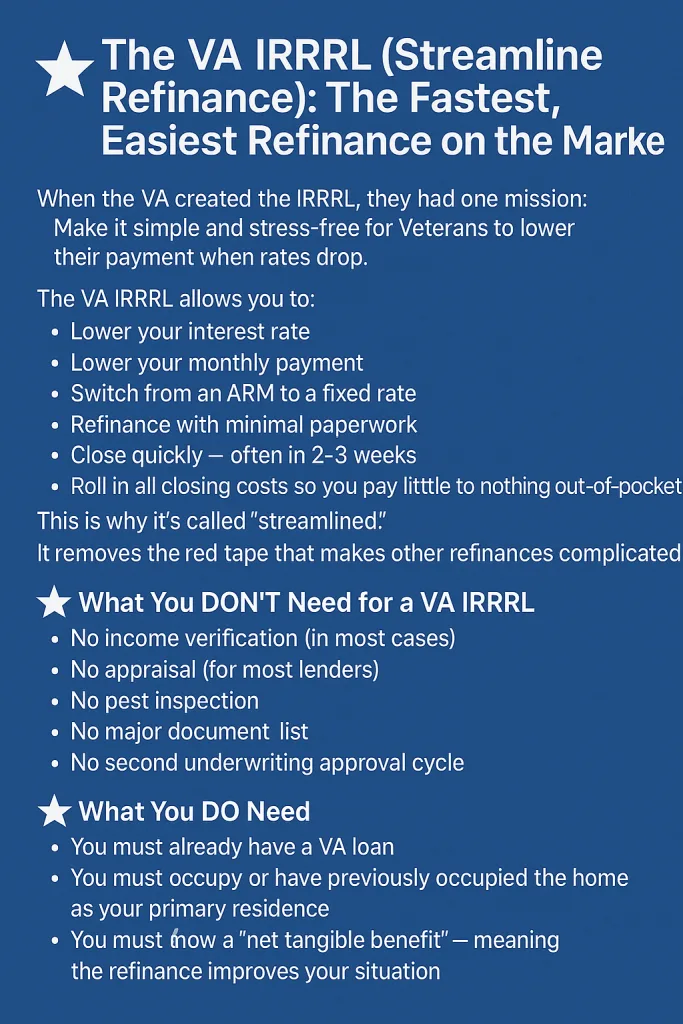
⭐ What Counts as a "Net Tangible Benefit"?
Here are examples of benefits that satisfy VA guidelines:
-
A lower monthly payment
-
A lower interest rate
-
Switching from an ARM to a fixed-rate loan
-
A shorter loan term (e.g., 30 years to 15 years)
-
Avoiding payment shock
-
A more stable long-term mortgage structure
If the lender can show the refinance improves your financial position, the VA IRRRL is usually approved.
Does the IRRRL Require an Appraisal?
In most cases, no.
This is one of the reasons Veterans love the IRRRL - even if property values change, the VA allows you to refinance based on your existing loan structure, not the current market value.
This makes refinancing fast, predictable, and extremely Veteran-friendly.
Does the IRRRL Require You to Live in the Property Now?
Another advantage:
You only need to certify you previously lived in the home.
This means you can IRRRL a property you used to occupy but now rent out or use differently.
The VA Funding Fee on an IRRRL
The VA IRRRL has a reduced funding fee compared to a regular VA purchase or cash-out refinance.
-
0.5% (half a percent)
-
Many Veterans have this fee waived if they have a qualifying disability rating
You can roll this fee into the new loan.
What About Closing Costs?
The VA allows IRRRL closing costs to be:
-
Rolled into the loan
-
Or covered with a small lender credit depending on rate
This keeps cash out of pocket low often zero.
The VA Cash-Out Refinance
If the IRRRL is the "fast, simple, lower-my-payment" refinance…
The VA Cash-Out Refinance is the flexibility powerhouse.
It allows you to:
-
Tap into equity for home improvements
-
Consolidate debt
-
Refinance a non-VA loan into a VA loan
-
Rebuild savings
-
Improve your long-term financial foundation
This is a full refinance:
-
Appraisal required
-
Full income & credit review
-
Standard VA underwriting
-
Can go up to 90% loan-to-value in many cases
This is a strong option for Veterans who want to unlock financial breathing room or move from a conventional/FHA loan into a VA loan for better terms.
What Happens to My VA Eligibility When I Refinance?
Great question and a place where many Veterans get confused.
Here's the truth:
✔ You do NOT "use more entitlement" by refinancing.
A refinance simply replaces your existing VA loan with another VA loan.
✔ Your entitlement remains tied to the home until the loan is paid off.
Just like before.
✔ When the loan is paid in full or the property is sold, your entitlement can be restored.
A Real Story: My Brother's Journey With the VA Loan
I want to share this because it's personal, meaningful, and shows exactly how powerful the VA loan really is.
My brother served in the United States Army and later retired from his military career with honor, discipline, and the heart of someone who always puts service first. Over the years, he used his VA Home Loan benefit multiple times, leveraging it strategically as his life and family evolved.
He lived in Lincoln, California, a wonderful community where he built both equity and memories. When the time came for a new chapter, he sold his home in Lincoln and used his equity combined with his VA eligibility to purchase a home in Dublin, Ohio, where he is now semi-retired.
Because of the VA program:
-
He didn't have to come in with a big down payment
-
His interest rate stayed competitive
-
His monthly payment remained incredibly affordable
-
His closing costs were minimal
-
His transition from California to Ohio was financially smooth and stress-free
His story is a perfect example of how Veterans can use the VA loan benefit again and again, across state lines, across different seasons of life, and across different financial goals.
The VA home loan truly supports stability and long-term wealth building.
Why Veterans Refinance: Real Motivations That Matter
Here's what I see every day in my practice:
⭐ Lowering the Monthly Payment
A lower rate means more room in your monthly budget and less stress.
⭐ Improving Cash Flow
Refinancing into a lower payment or adjusting the loan term gives more space for living, saving, investing.
⭐ Shifting into a More Stable Mortgage
Moving from an adjustable-rate mortgage (ARM) into a long-term fixed loan brings peace of mind.
⭐ Accessing Equity
Renovations, debt consolidation, emergency funds - refinancing can create stability.
⭐ Preparing for Retirement
Veterans approaching retirement often consolidate or lower payments to support their financial lifestyle.
Thank YOU For Our Freedom & Your Service!
There is a moment in every conversation with a Veteran where I pause and just take it in the honor of serving those who have served us.
Your courage, your commitment, your sacrifices, your families, your stories…
they are the heartbeat of this work.
Refinancing isn't just about lowering a rate or exploring options.
It's about creating stability.
It's about building wealth.
It's about supporting the life you've worked hard for.
And as someone who has a brother who dedicated his life to the Army, this mission is personal. It's deeply meaningful. And it's something I will never take for granted.
Thank you truly for your service.
❓Frequently Asked Questions About VA Refinancing & the VA IRRRL
❓Can I use a VA IRRRL if I already refinanced before?
Yes. Veterans can use the VA IRRRL multiple times as long as each refinance gives you a net tangible benefit meaning the refinance must improve your financial situation. This usually means a lower rate, lower payment, or switching from an ARM to a fixed rate.
❓Do I need a Certificate of Eligibility (COE) for a VA IRRRL?
Not usually. For most VA IRRRL refinances, your previous VA loan already established eligibility, so your lender can use the prior information. In many cases, the VA doesn't require a new COE at all - one of the biggest reasons the IRRRL is called a "streamline."
❓Can I roll my closing costs into the loan with a VA IRRRL?
Yes. With the VA IRRRL, most closing costs can be rolled into the new loan amount, making it possible to refinance with little to no money out of pocket.
❓ Can I refinance if my credit isn't perfect?
Yes. The VA is one of the most flexible loan programs available. Even if your credit isn't perfect, you may still qualify especially for an IRRRL, which doesn't require a full credit package in most cases.
❓ Can I roll closing costs into the loan?
Yes, most va refinances allow you to roll closing costs in the new loan amount. As long as you have enough equity.
❓ Can I refinance even if I've refinanced before?
Yes. You can use your VA benefit more than once. The only requirement is that the IRRRL provides a net tangible benefit meaning the refinance must improve your financial position.
❓ Can I refinance a rental property with a VA loan?
Yes if it was previously your primary residence. The IRRRL allows you to refinance a home that you once lived in, even if it's now a rental property.
❓ Do I need a pest inspection for a VA refinance?
Not for an IRRRL. One of the major benefits of the VA Streamline is that it does not require a pest inspection or repairs in most cases.
Yes. Veterans can use the VA IRRRL multiple times as long as each refinance gives you a net tangible benefit meaning the refinance must improve your financial situation. This usually means a lower rate, lower payment, or switching from an ARM to a fixed rate.
Not usually. For most VA IRRRL refinances, your previous VA loan already established eligibility, so your lender can use the prior information. In many cases, the VA doesn't require a new COE at all - one of the biggest reasons the IRRRL is called a "streamline."
Yes. With the VA IRRRL, most closing costs can be rolled into the new loan amount, making it possible to refinance with little to no money out of pocket.
Yes. The VA is one of the most flexible loan programs available. Even if your credit isn't perfect, you may still qualify especially for an IRRRL, which doesn't require a full credit package in most cases.
Yes, most va refinances allow you to roll closing costs in the new loan amount. As long as you have enough equity.
Yes. You can use your VA benefit more than once. The only requirement is that the IRRRL provides a net tangible benefit meaning the refinance must improve your financial position.
Yes if it was previously your primary residence. The IRRRL allows you to refinance a home that you once lived in, even if it's now a rental property.
Not for an IRRRL. One of the major benefits of the VA Streamline is that it does not require a pest inspection or repairs in most cases.
Explore Our VA Loan Playlist on YouTube
If you're the kind of Veteran who likes to see how things work - not just read about them - you're going to love our VA Loan Playlist on YouTube. This collection brings together everything you need to understand your VA benefits clearly, confidently, and without the overwhelm that often comes with mortgage research.
Inside the playlist, you'll find:
-
The Ultimate Guide to VA Loans - a deep-dive video where I walk you through eligibility, funding fee rules, seller credits, MPR requirements, and how to structure offers that get accepted.
-
VA IRRRL Explained (Streamline Refinance) - a visual breakdown of how the VA's fastest refinance works, who qualifies, and how to lower your payment with minimal paperwork.
-
VA vs. CalVet - a comparison to help California Veterans understand when each option is the better choice.
-
VA Myths Debunked - tackling the most common misconceptions that keep Veterans from using the benefit they earned.
-
Winning VA Offers in a Competitive Market - guidance for both Veterans and Realtors on how to write stronger offers and speak to listing agents with confidence.
Every video is designed to be simple, empowering, and packed with value - whether you're buying your first home, refinancing for a better payment, or preparing to make an offer.
You can visit the full playlist anytime here:
YouTube Playlist: The Ultimate VA Home Loan Guide
All Mortgage Made Easy articles · Book a Complimentary Discovery Call