With Amy DeBusk
Your home search starts with a workable plan.
I help Veterans buying in Sacramento and Placer County connect the home they want with a payment, cash-to-close estimate, and financing timeline they understand. Before you make an offer, my team and I review your VA benefit and application, explain property questions, and coordinate the mortgage steps with your agent. If you are relocating, we can work together by Zoom or phone while you explore neighborhoods.
Build your VA homebuying plan → · Talk with me about your plans →
The Ultimate VA Home Loan Guide for 2026
By Amy DeBusk, Branch Manager & Mortgage Advisor | loanDepot
All loans subject to approval. Equal Housing Lender.
The VA Home Loan program is one of the most powerful, flexible and life-changing benefits available to the brave men and women who served our country. And for Veterans buying a home in Sacramento, Roseville, Placer County, or anywhere in California, the program isn't just helpful, it can be part of a thoughtful plan for long-term homeownership.
This ultimate guide blends clear explanations with deeper technical insights that most lenders never explain. My goal is simple: help you fully understand your VA benefit so you can build long-term wealth and buy your home with confidence.
A Message From My Heart to Every Veteran and Military Family
Before anything else, I want to speak directly to you.
Thank you for your service.
Thank you for your courage.
And thank you for protecting the freedom and beauty of our country.
I am deeply thankful to be a citizen of the United States, and I appreciate every man and woman who has served to keep our nation strong. It is one of the greatest honors of my life to serve Veterans and help you use the home loan benefit you have earned with such dedication.
Your sacrifices and the sacrifices of your families matter.
I see you.
And I am here to support your homeownership journey with the highest level of care, clarity, and respect.
What Makes the VA Loan So Different?
Most loan programs are transactional.
The VA loan is transformational.
It offers:
Zero down payment
No mortgage insurance
Competitive rates
Flexible credit
No prepayment penalty
Higher allowances for seller credits
Multiple refinance options
Multi-unit property opportunities
Lifetime reuse
This program exists because of your service. You earned it.
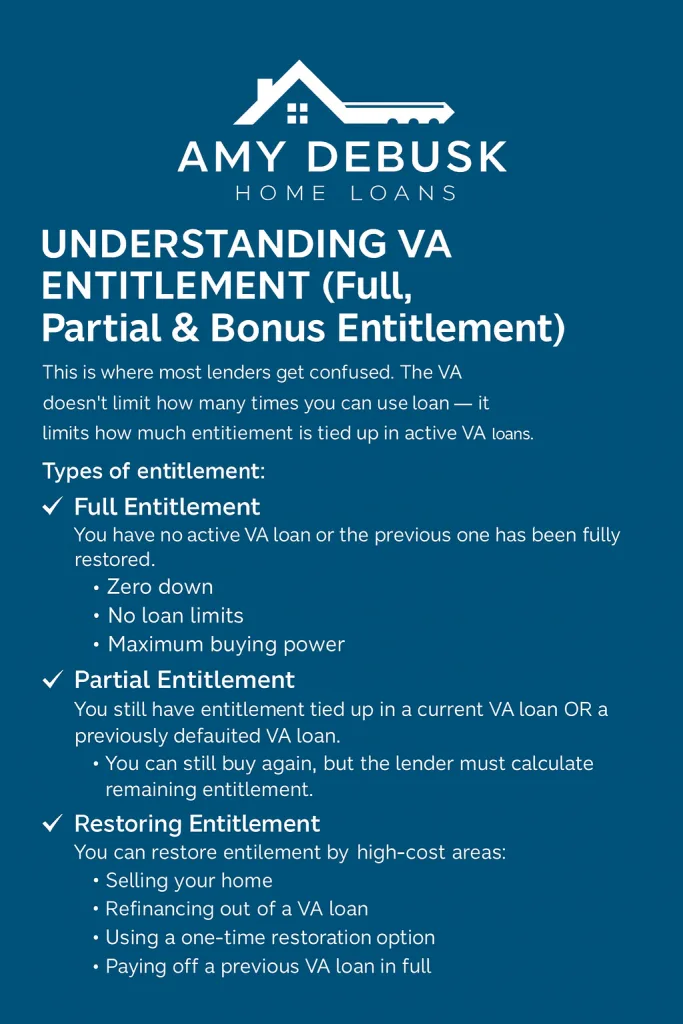
VA Loan Eligibility & Entitlement (Real-World Breakdown)
Understanding VA eligibility is the foundation of using your benefit effectively.
✔ Who Is Eligible?
You may be eligible if you are:
A Veteran
Active-Duty
National Guard or Reserve
An eligible surviving spouse
A member of NOAA, Public Health Service, or certain commissioned officer programs
✔ Service Requirements (Simplified)
Different eras of service have different required service days:
Wartime service: generally 90 consecutive days
Peacetime: generally 181 days
National Guard & Reserves: typically 6 years, unless activated under Title 10
Most Veterans underestimate their eligibility - even if they never deployed.
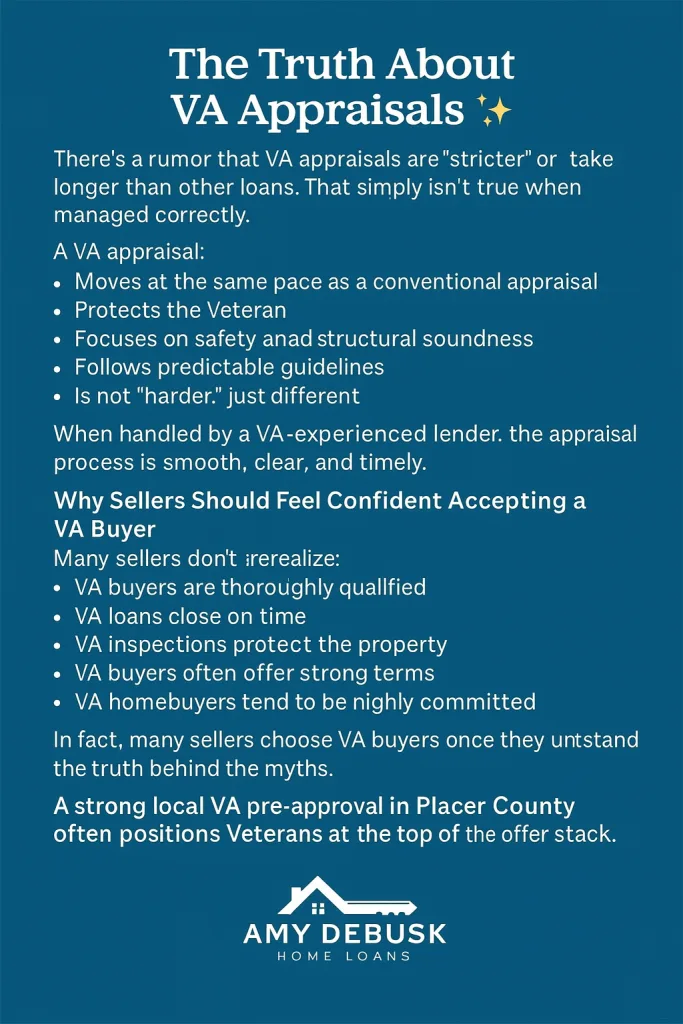
VA Appraisal & Minimum Property Requirements (Deep Technical Breakdown)
The VA appraisal is often misunderstood - including by Realtors.
It has two parts:
✔ 1. Property Valuation
Confirms that the price is fair.
✔ 2. Minimum Property Requirements (MPRs)
Ensures the home is safe, sanitary, and structurally sound.
Let's break down the MOST important MPRs.
Critical VA MPR Requirements
✔ Roof & Structure
Roof must have "reasonable remaining life."
No severe leaks, major sagging, or structural compromises.
✔ Mechanical Systems
Electrical, plumbing, and heating must be:
Safe
Functional
Adequate for the home's size
HVAC must heat the home to a comfortable level.
✔ Water & Sewage
The home must have:
Safe drinking water
Approved sewage system
Hot water
Working fixtures
Private wells are allowed but must pass water quality tests.
✔ Lead-Based Paint
If the home was built before 1978:
Peeling paint must be repaired
Lead hazards corrected
This is non-negotiable.
✔ Crawlspace & Attic
Must be:
Accessible
Adequately ventilated
Clear of standing water
Free of serious damage
✔ Electrical
No:
Exposed wires
Missing plates
Unsafe panel conditions
VA Repairs - The Truth The VA does not require perfection. It requires safety.
Most VA-required repairs are minor and can be negotiated with sellers easily - especially when you are properly represented. By a premier VA Realtor, who understands how to navigate a VA purchase transaction. At Amy DeBusk Home Loans we have premier VA realtors standing by to serve you.
VA Closing Costs (And What Veterans Cannot Pay)
The VA has unique rules about what fees the buyer is not allowed to pay.
This protects Veterans.
❌ Veterans cannot pay:
Attorney fees for the lender
Prepayment penalties
Brokerage fees
"Junk fees" charged by lenders
✔ Veterans can pay:
Appraisal
Credit reports
Title fees
Recording fees
Seller Credits (The Famous VA 4% Rule)
Sellers can:
Pay ALL closing costs
Pay prepaid taxes & insurance
Pay discount points
Contribute up to 4% of the purchase price toward:
• Paying off debt
• Collections
• Judgments
• Funding fee
This is a massive advantage for lower-income or first-time Veteran buyers.
MYTH BUSTER :You Need Full Pest Clearance (Section 1 & 2) to Close a VA Loan.
This one surprises almost everyone - even Realtors and some lenders.
Many people believe that VA requires a full pest report with every Section 1 and Section 2 item repaired before closing.
Truth:
In many cases, all that is required is the NPMA-33 form, which certifies no visible active infestation - not full clearance of every repair.
A full Section 1 and Section 2 clearance is only needed when:
The appraiser notes evidence of wood-destroying organisms
The pest inspector identifies active infestation or structural concerns
The property is in a high-risk region and the inspection notes visible issues
Here in Placer County - where VA buyers are common - the NPMA-33 is widely accepted when appropriate.
This saves:
Time
Money
Stress
Unnecessary repairs
Most Veterans have never been told this - but this single rule can make your offer significantly stronger.
One of the Most Powerful VA Loan Rules: Sellers Can Pay Off Your Debts
This is one of the best-kept secrets of the VA loan.
A seller can contribute up to 4% of the purchase price toward:
Closing costs
Prepaid taxes and insurance
Discount points
AND debts you need to pay off to qualify
For example, on a $600,000 home, a seller can contribute up to $24,000.
That money can be used to:
Pay off credit cards
Pay down an auto loan
Eliminate a personal loan
Cover closing costs
Reduce your interest rate
This dramatically improves your buying power and qualification.
Hidden Advantage: Grossing Up Disability or Social Security Income
Veterans receiving non-taxable income get a unique benefit when qualifying for a VA loan.
VA guidelines allow lenders to "gross up" non-taxable income by 15%, increasing the qualifying amount.
Example
Your disability income is $3,500 per month.
15% of that is $525.
This means you can qualify using $4,025 instead of $3,500.
This can increase your:
Purchase power
Debt-to-income ratio
Loan approval strength
Most Veterans do not know VA offers this expanded qualifying option - but it's one of the most impactful benefits.
California Disabled Veteran Advantage: SB-23
California is one of the most Veteran-supportive states in the nation, especially for those with a disability rating.
Under SB-23, Disabled Veterans may qualify for major property tax exemptions, saving thousands of dollars every year.
Some of my clients in Placer County save $8,000-$12,000 annually on property taxes.
This dramatically improves:
Monthly affordability
Long-term wealth
Qualification strength
Financial ease
If you are a Disabled Veteran in California, SB-23 is one of the most powerful financial advantages available.
What Veterans Should Know Before Touring Homes
1. Your spending plan matters - not perfection.
You don't need a perfect financial picture to qualify. You just need clarity.
2. Your VA strategy is unique.
Entitlement, income, goals, timing - every Veteran's path is different.
3. A strong VA pre-approval helps you win offers.
Sellers want certainty. A thorough pre-approval provides that advantage.
4. Touring too early creates frustration.
Knowing your numbers first makes the entire process smoother.
5. The pre-approval process is fast.
A conversation and a few documents are all it takes.
Final Thoughts
Your VA benefit is more than a mortgage - it's a lifelong financial advantage. When used correctly, it can help you:
Build wealth
Invest strategically
Keep your payment affordable
Create stability for your family
Buy multiple homes over your lifetime
And in the Sacramento and Roseville markets, where the right strategy matters, having an expert in your corner makes all the difference.
Strengthen Your Spending Plan with SaveBotGame.com
Financial readiness doesn't have to feel heavy.
To make this easier - and even fun - I created:
It's a simple, supportive game that helps you:
Strengthen your spending plan
Build confidence
Improve your savings
Prepare for homeownership
So many Veterans tell me it's the first time saving money actually felt encouraging - not restrictive.
Your Full VA Resource Library
For deeper education, explore my dedicated VA page:
👉 https://amydebuskhomeloans.com/va-home-loans-expert
You'll find:
Entitlement rules
Multi-VA loan strategies
Local Sacramento + Placer County guidance
VA closing cost options
My full set of VA videos and tools
This page is your complete VA homebuying roadmap.
Everything Veterans Ask About VA Home Loans
❓ 1. Can I use my VA loan more than once?
Yes you can use your VA loan for your entire life.
❓ 2. Can I have two VA loans at the same time?
Yes, depending on your remaining entitlement.
❓ 3. Do VA loans take longer to close?
No with a VA-knowledgeable lender, VA loans close just as smoothly as other loan types. The VA appraisal can take up to 10 business days, with Amy DeBusk Home Loans our process is seemless and we ensure that your loan funds on time per your contract.
❓ 4. Do all pest issues need to be repaired?
Not always. In many cases, the NPMA-33 form (no active infestation) is all that's required.
❓ 5. Can a seller pay my closing costs?
Yes up to 4% of the purchase price.
❓ 6. Can I buy a duplex or fourplex with a VA loan?
Yes as long as you live in one of the units.
❓ 7. Do I need perfect credit for a VA loan?
No VA loans have flexible credit guidelines. For credit health guidelines please check out Amy DeBusk's website
❓ 8. Are VA interest rates competitive?
Yes VA rates are often lower than conventional and FHA loans. To learn more about current interest rates - Book your free discovery call with Amy, here!
❓ 9. How does SB-23 work for Disabled Veterans?
SB-23 offers powerful property tax exemptions, reducing annual expenses dramatically.
All Mortgage Made Easy articles · Book a Complimentary Discovery Call