VA 5/1 Adjustable-Rate Mortgages (ARMs) offer eligible Veterans and service members in Roseville, Rocklin, Lincoln, Sacramento, and Placer County an initial interest rate that is often significantly lower than a traditional 30-year fixed VA loan.
I'm Amy DeBusk, Branch Manager with over 25 years of experience helping Veterans and homebuyers navigate the mortgage process, and a specialist in VA home loans here in Northern California.
In today's market, VA 5/1 ARM rates are typically about 0.75% lower than comparable 30-year fixed VA loans. That difference can create meaningful monthly savings during the first five years, while still following a full 30-year principal-and-interest amortization schedule.
In 2026, with mortgage rates averaging between 6.3% and 6.5% and home prices in Roseville, Rocklin, Lincoln, and Placer County ranging from approximately $626,000 to $658,000, this lower starting rate can dramatically improve affordability and buying power for many Veterans.
What is a VA 5/1 ARM?
A VA 5/1 ARM is a hybrid mortgage backed by the Department of Veterans Affairs.
It offers:
- a fixed interest rate for the first 5 years
- annual rate adjustments after year 5
"5" = fixed period
"1" = adjusts once per year
Unlike some loan types, this loan is fully amortized over 30 years from day one, meaning every payment includes both principal and interest.
VA ARM Protections
VA loans include built-in safeguards that protect borrowers:
- First adjustment cap: 2%
- Annual adjustment cap: 1%
- Lifetime cap: 5% above your starting rate
These protections are one of the reasons VA loans remain one of the strongest loan programs available.
Common Misconception
A common myth is that VA ARMs are interest-only loans.
That is NOT true.
VA 5/1 ARM loans:
- include principal and interest from the beginning
- build equity immediately
- follow a standard 30-year amortization
The lower rate simply reduces your monthly payment, it does not delay principal repayment.
How much lower are VA ARM rates?
In most cases, VA 5/1 ARM rates are about 0.75% lower than 30-year fixed VA loans.
This difference can result in:
- $150 to $300 per month in savings
- thousands of dollars saved over the first 5 years
This is especially impactful in higher-priced areas like:
- Roseville
- Rocklin
- Lincoln
- Sacramento
- Placer County
Why VA ARMS are different from Conventional ARMS
This is where things get really important.
In today's market, VA ARM loans are one of the few ARM products that truly make sense.
Because of the current bond market and yield curve:
Many conventional ARM rates are very similar to 30-year fixed rates
That means:
- conventional ARMs often do NOT provide meaningful savings
- they may not justify the added risk
VA ARMs, on the other hand, still offer real rate advantages
Jumbo ARM Strategy
For higher-priced homes, another option is a Jumbo ARM loan.
These can be beneficial for buyers in:
- Roseville
- Rocklin
- Lincoln
- Placer County
Jumbo ARMs may offer:
- lower initial rates
- increased flexibility
- improved short-term affordability
Real Client Example: VA ARM Savings for a Veteran in Placer County
Recently, I helped a Veteran refinance out of a 7.375% 30-year fixed VA loan into a VA 5/1 ARM at 5.125%.
At the time, the 30-year fixed rate was approximately 5.99%.
By choosing the VA ARM instead of the fixed loan, this borrower:
- lowered their interest rate significantly
- saved approximately $300 per month
- improved their cash flow immediately
This is a perfect example of using a VA ARM strategically.
What Happens in Year 6?
After the first 5 years, your VA ARM transitions from a fixed rate to an adjustable rate. Starting in year 6, the interest rate can change once per year based on market conditions.
How the New Rate Is Calculated
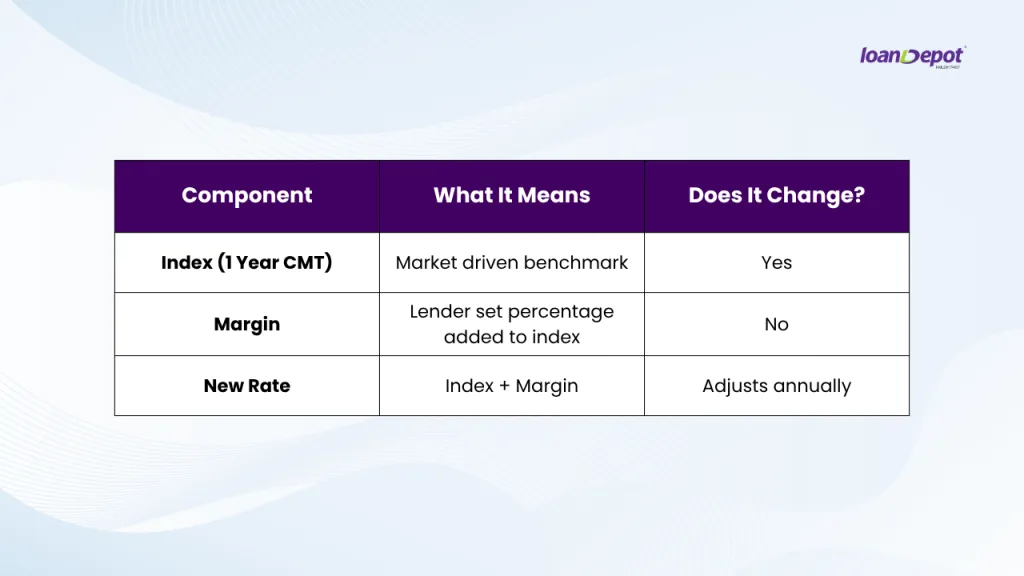
Your updated rate follows a simple formula:
Index + Margin = New Interest Rate
Both parts play a different role in how your rate moves.
Understanding the Components
- The Index: Most VA ARMs are tied to the 1 Year Constant Maturity Treasury (CMT). This index reflects broader market trends and can rise or fall over time.
The Margin: The margin is set by your lender at the beginning of the loan and remains fixed for the entire loan term. It does not change, regardless of market conditions.
What This Means for You
Your rate is not locked after year 5, but it is also not unpredictable chaos. Adjustments happen once per year, giving you time to evaluate your options.
Rates may decrease if the market improves, which can lower your monthly payment. On the other hand, if rates rise, your payment may increase, but only within the limits set by your loan's caps.
Annual Adjustments Only
VA ARMs adjust once per year, not monthly. This structure gives you breathing room to plan ahead, refinance if needed, or prepare for potential payment changes without sudden surprises.
Is it a problem if the rate adjusts?
This is where experience matters.
It is NOT always the end of the world.
Over the past 25+ years, I've worked with many clients who had adjustable-rate mortgages and actually ended up paying less interest over time compared to taking a higher fixed rate upfront.
Why Many Still Choose Fixed Rates
Most people prefer certainty.
That's why many Veterans choose: a 30-year fixed VA loan or VA IRRRL refinance
Risk vs Reward
A VA ARM can be a smart financial tool when used strategically. It offers meaningful advantages upfront, but it is important to understand the tradeoffs.
The Potential Benefits
- Lower initial interest rate compared to fixed loans
- Opportunity for long term savings if rates stay stable or decline
- Flexibility if you plan to move, refinance, or pay off the loan within a few years
Some Veterans also use this flexibility as part of a longer-term investment plan.
The Tradeoff
Some level of uncertainty after the fixed period ends
An Honest Perspective
I tend to be optimistic when it comes to market trends, but the truth is simple. No one can predict exactly where interest rates will go.
That is why this loan is less about guessing the future and more about having a clear strategy.
If you go into a VA ARM with a plan, whether that is selling, refinancing, or taking advantage of early savings, it can work strongly in your favor.
Key Benefits of a VA 5/1 ARM
A VA 5/1 ARM can open doors for buyers who want to maximize affordability in the early years of homeownership.
- Lower monthly payments during the initial fixed period
- Increased buying power, allowing you to qualify for more home
- No down payment required for eligible borrowers
- No PMI, which helps keep monthly costs lower
- Built in rate caps that limit how much your rate can increase
- Flexibility to refinance or sell before adjustments become a factor
When a VA ARM Makes Sense
This type of loan works best when it aligns with your timeline and financial strategy.
- Planning to move within 5 to 7 years
- Expecting to refinance before or shortly after the adjustment period
- Believing rates may improve over time
- Prioritizing lower payments and higher affordability upfront
When It May Not Be the Best Fit
A fixed rate loan may be the better choice if stability is your top priority.
- Planning to stay in the home long term
- Preferring consistent, predictable monthly payments
- Wanting to avoid any exposure to future rate changes
Local Market Impact
For Veterans buying in highly competitive areas like Roseville, Rocklin, Lincoln, Sacramento, and throughout Placer County, a VA 5/1 ARM can create a real advantage.
With lower initial payments, buyers may qualify for higher purchase prices while keeping monthly costs manageable. This can strengthen offers and improve overall competitiveness in fast moving markets where affordability and positioning both matter.
Some buyers also compare this approach with other VA-backed options depending on their long-term goals.
VA 5/1 ARM vs 30 Year Fixed VA
Here is a side by side look at how these two options compare:
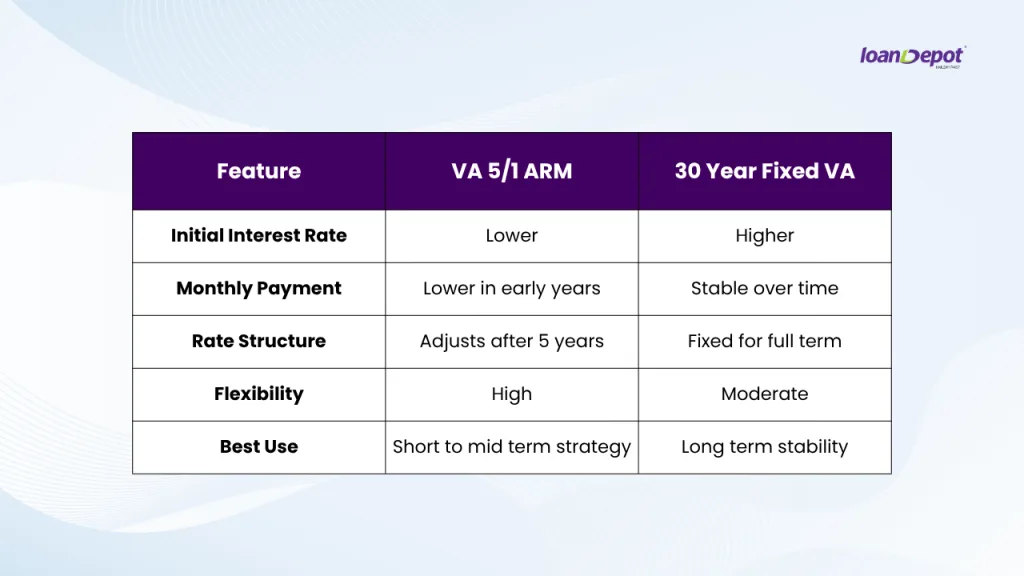
Choosing between these options comes down to your timeline, financial goals, and how much flexibility you want in the early years versus long term predictability.
❓ FAQs About VA 5/1 ARM Loans
❓1. What is a VA 5/1 ARM loan and how is it different from a fixed-rate loan?
A VA 5/1 ARM is a loan backed by the Department of Veterans Affairs that offers a fixed interest rate for the first 5 years, followed by annual adjustments after that.
The key difference from a 30-year fixed loan is flexibility versus certainty.
With a fixed-rate loan, your interest rate and payment never change. With a VA ARM, your rate can adjust after year 5, but you benefit from a lower starting rate.
This can be a powerful strategy if you don't plan to stay in the home long-term or if you intend to refinance later. For more information, read our Ultimate Guide to VA Loans.
❓2. How is the interest rate determined after the first 5 years?
After year 5, your interest rate is recalculated once per year using:
Index + Margin = New Rate
Most VA ARMs are tied to the 1-Year Constant Maturity Treasury (CMT) index, which moves based on market conditions.
The margin is a fixed number set when your loan is originated and does not change.
If interest rates are lower at the time of adjustment, your rate could actually decrease. If rates are higher, your rate may increase, but it is limited by VA caps.
❓3. How much can my payment increase after the adjustment period?
VA loans include built-in protections to prevent large payment shocks.
These include:
- First adjustment cap of 2%
- Annual adjustment cap of 1%
- Lifetime cap of 5% above your starting rate
This means even in a worst-case scenario, your rate increases gradually and within defined limits.
It's also important to remember that many borrowers refinance before these adjustments become significant.
❓4. Is a VA 5/1 ARM risky compared to a 30-year fixed loan?
It depends on your situation and your plan.
A VA ARM does introduce some uncertainty after year 5, which is why many borrowers prefer fixed-rate loans.
However, when used strategically, an ARM can actually reduce overall interest paid, especially if you sell or refinance before major adjustments occur.
Over the past 25+ years, many borrowers have benefited from adjustable-rate loans because they took advantage of lower rates early on.
The key is having a plan and understanding your options.
❓5. When does it make the most sense to choose a VA ARM?
A VA 5/1 ARM makes the most sense when your timeline aligns with the fixed period.
Examples include:
- you plan to move within 5-7 years
- you expect interest rates to decrease
- you want to refinance later using a VA IRRRL
- you want to maximize buying power today
If your goal is flexibility and short- to mid-term savings, this loan can be a strong option.
❓6. Can I refinance a VA ARM loan before it adjusts?
Yes, and this is one of the biggest advantages.
Veterans can use a VA IRRRL (Interest Rate Reduction Refinance Loan) to refinance into a fixed-rate loan or another structure.
To qualify:
- the loan must be seasoned 210 days from the first payment
- you must make at least 6 on-time payments
- there must be a clear net tangible benefit
This creates a built-in exit strategy.
❓7. How does a VA ARM compare to conventional and jumbo ARM loans?
In today's market, VA ARMs often provide more value than conventional ARMs.
Due to the current bond market and yield curve, many conventional ARM rates are very close to fixed rates, which reduces their benefit.
VA loans still offer:
- lower rates
- no PMI
- better overall terms
Jumbo ARM loans can also be useful for higher-priced homes, especially in markets like Roseville and Placer County.
For a deeper breakdown of how conventional loans compare and when they make sense, it helps to understand the full picture.
❓8. Can I use a VA ARM if I plan to turn the home into a rental later?
Yes, many Veterans use this strategy.
A VA ARM can be especially useful in this scenario because it lowers your initial payment, improving cash flow before transitioning the property into an investment.
A VA 5/1 ARM is a loan backed by the Department of Veterans Affairs that offers a fixed interest rate for the first 5 years, followed by annual adjustments after that.
The key difference from a 30-year fixed loan is flexibility versus certainty.
With a fixed-rate loan, your interest rate and payment never change. With a VA ARM, your rate can adjust after year 5, but you benefit from a lower starting rate.
This can be a powerful strategy if you don't plan to stay in the home long-term or if you intend to refinance later. For more information, read our Ultimate Guide to VA Loans.
After year 5, your interest rate is recalculated once per year using:
Index + Margin = New Rate
Most VA ARMs are tied to the 1-Year Constant Maturity Treasury (CMT) index, which moves based on market conditions.
The margin is a fixed number set when your loan is originated and does not change.
If interest rates are lower at the time of adjustment, your rate could actually decrease. If rates are higher, your rate may increase, but it is limited by VA caps.
VA loans include built-in protections to prevent large payment shocks.
These include:
- First adjustment cap of 2%
- Annual adjustment cap of 1%
- Lifetime cap of 5% above your starting rate
This means even in a worst-case scenario, your rate increases gradually and within defined limits.
It's also important to remember that many borrowers refinance before these adjustments become significant.
It depends on your situation and your plan.
A VA ARM does introduce some uncertainty after year 5, which is why many borrowers prefer fixed-rate loans.
However, when used strategically, an ARM can actually reduce overall interest paid, especially if you sell or refinance before major adjustments occur.
Over the past 25+ years, many borrowers have benefited from adjustable-rate loans because they took advantage of lower rates early on.
The key is having a plan and understanding your options.
A VA 5/1 ARM makes the most sense when your timeline aligns with the fixed period.
Examples include:
- you plan to move within 5-7 years
- you expect interest rates to decrease
- you want to refinance later using a VA IRRRL
- you want to maximize buying power today
If your goal is flexibility and short- to mid-term savings, this loan can be a strong option.
Yes, and this is one of the biggest advantages.
Veterans can use a VA IRRRL (Interest Rate Reduction Refinance Loan) to refinance into a fixed-rate loan or another structure.
To qualify:
- the loan must be seasoned 210 days from the first payment
- you must make at least 6 on-time payments
- there must be a clear net tangible benefit
This creates a built-in exit strategy.
In today's market, VA ARMs often provide more value than conventional ARMs.
Due to the current bond market and yield curve, many conventional ARM rates are very close to fixed rates, which reduces their benefit.
VA loans still offer:
- lower rates
- no PMI
- better overall terms
Jumbo ARM loans can also be useful for higher-priced homes, especially in markets like Roseville and Placer County.
For a deeper breakdown of how conventional loans compare and when they make sense, it helps to understand the full picture.
Yes, many Veterans use this strategy.
A VA ARM can be especially useful in this scenario because it lowers your initial payment, improving cash flow before transitioning the property into an investment.
Learn More: VA Loan Video Playlist for Veterans
If you prefer to learn by watching instead of reading, we've created a full YouTube playlist dedicated to VA home loans, strategies, and real-world scenarios.
In this playlist, we break down topics like:
- VA loan eligibility and benefits
- how to use your VA loan more than once
- refinancing strategies with VA IRRRL
- turning your VA home into a rental
- and how to structure your loan for long-term success
These videos are designed to give you clarity and confidence so you can move forward with a plan that fits your goals.
Ask Anything: VA Loan GPT App for Veterans
Have questions about VA loans, credit, down payment assistance, or your specific situation?
We've created a VA Loan GPT App designed specifically for Veterans, so you can get quick, clear answers anytime.
You can use it to:
- understand your VA loan eligibility
- explore loan options
- learn about refinancing strategies
- get guidance on buying your first home or next investment
It's like having a mortgage expert available whenever you need it.
Explore Our VA Loan Hub
If you're serious about using your VA benefits, our VA Loan Hub is the best place to start.
This section of our website brings everything together in one place, including:
- VA loan education
- step-by-step home buying guidance
- refinancing options
- tools and resources for Veterans
- strategy-based content to help you build long-term wealth through homeownership
Whether you're buying your first home, refinancing, or planning your next move, the VA Hub will help you understand your options clearly.
All loans subject to approval. Equal Housing Lender.
All Mortgage Made Easy articles · Book a Complimentary Discovery Call