With Amy DeBusk
See the potential, then prepare the financing.
You may have found the right neighborhood and a home that needs some care. I help you review the proposed work, financing needs, and available renovation options before you move forward. My team explains the contractor documentation, appraisal, and loan steps that need to come together. We coordinate the financing questions with your agent and contractor, while those professionals guide the home search and construction work.
Explore renovation planning and options → · Talk with me about your plans →
This is not a standard VA loan program.
If you're a Veteran looking to buy a home in Sacramento, Roseville, or the surrounding areas and you're seeing homes that need updates, you may feel stuck choosing between overpaying for a fully renovated home or walking away from a property with potential.
I'm Amy DeBusk, a Branch Manager and mortgage advisor with over 25 years of experience, and I work with buyers every week who don't realize there are options that allow them to purchase a home and finance renovations into the same loan.
This VA renovation program is one of the most underutilized opportunities available to Veterans today. In some cases, it allows for 100% financing, flexible credit options, and the ability to turn a fixer-upper into the home you actually want.
The key is understanding how this program really works and whether it fits your situation. If you're a Veteran looking to buy a fixer-upper in Sacramento or Roseville, this program can open up opportunities most buyers overlook.
If you're still exploring how VA financing works overall, you can start with our full VA loan guide to understand the basics before diving into renovation options.
Why Most Lenders Don't Offer This Program
One of the biggest misconceptions is that all lenders offer VA renovation loans.
The reality is, very few lenders have the systems, approvals, and overlays in place to support this type of financing.
That's why many Veterans are told this option doesn't exist.
I've personally worked with buyers who were previously turned away or misinformed, only to discover that this program was available with the right structure.
What Is a VA Renovation Loan?
A VA Renovation Loan allows eligible Veterans and active duty service members to purchase a home and finance the cost of improvements into one loan.
Key features:
- 0% down payment
- Finance both purchase and renovation in one loan
- Credit scores starting around 600 FICO depending on profile
- One monthly payment instead of multiple loans
This means you can take a home with potential and turn it into a space that truly fits your lifestyle without needing separate financing or waiting years to renovate.
Instead of settling for what is available, you have the ability to create the home you actually want from the start.
Many buyers compare this with other loan types, so if you are weighing options, here is a helpful breakdown of how FHA loans work for buyers needing flexibility.
All loans subject to approval. Equal Housing Lender.
Why This Loan Matters Right Now
Inventory is tight and move in ready homes are selling at premium prices.
Buyers are competing for the same updated properties, often driving prices higher and limiting options.
But there is a major opportunity many buyers overlook.
Homes that need updates.
These properties are often priced lower, receive less competition, and can open the door to better locations or larger homes.
Instead of competing for the most polished home, you can:
- Buy at a lower price
- Customize everything to your style
- Build equity faster
This strategy gives you more control over your budget, your design choices, and your long term investment, often leading to better overall value.
For buyers trying to make affordability work in today's market, combining this strategy with down payment assistance programs can open even more opportunities depending on your eligibility.
Two Powerful Options Based on Your Vision
One of the biggest advantages of a VA Renovation Loan is flexibility.
Not every buyer is looking for the same level of work, and not every home requires a full overhaul. That is why this program offers different paths depending on your goals, timeline, and the condition of the property.
Whether you are looking for light cosmetic updates or a full transformation, there is an option designed to fit your vision.
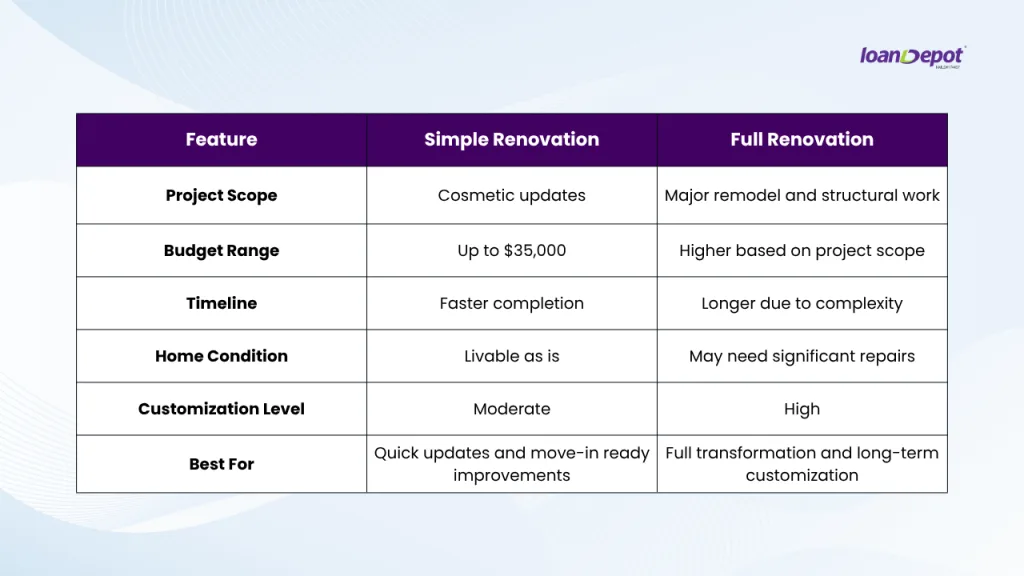
The Simple Renovation (Up to $35,000)
This option is perfect for homes that are already livable but need a refresh.
If the layout works and the structure is solid, you can focus on improving the look and feel of the home without taking on a major construction project.
Common upgrades include:
- New flooring
- Interior or exterior paint
- Kitchen or bathroom updates
- Appliances
- Minor repairs
This option is faster, more streamlined, and ideal for buyers who want to move in quickly while still upgrading the home to match their style.
Full Renovation (Major Remodel)
This is where you unlock the full potential of a property.
If you find a home in a great location but it needs significant work, this option allows you to finance larger, more complex renovations and truly redesign the space.
Common upgrades include:
- Kitchen and bathroom remodels
- Roof replacement
- Structural repairs
- Room additions
- HVAC, plumbing, or electrical upgrades
This option is ideal for buyers who want to create a fully customized home and are willing to take on a more detailed renovation process.
Should You Use a VA Renovation Loan?
In today's Sacramento and Placer County market, this loan can be a powerful strategy, but only if it aligns with your timeline, comfort level, and the condition of the property.
This program works best when:
- The home needs cosmetic updates
- You want to avoid overpaying for a fully renovated home
- You're looking to build equity through improvements
- You want to keep your upfront cash investment low
It may not be the best option if:
- The home requires major structural repairs
- You need a fast or simple closing process
- You're not comfortable managing renovation timelines
This is not the right loan for every buyer, but for the right situation, it can be a game-changer.
Why the Scope of Work Matters
The scope of work is one of the most important parts of a VA Renovation Loan.
It directly impacts how your loan is structured, how and when funds are released, and how long the entire process will take from start to finish.
Understanding this upfront helps set the right expectations and helps avoid delays later on.
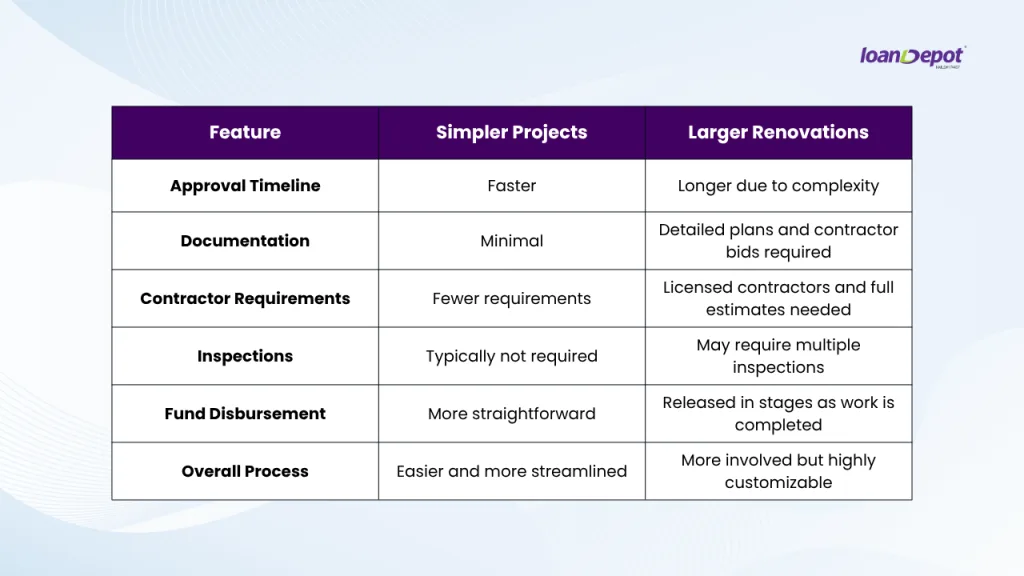
Choosing the right scope of work comes down to your priorities. If speed and simplicity are important, a smaller project keeps things moving quickly and gets you into your home sooner. It is a great option for buyers who want improvements without a complex renovation process.
On the other hand, if your goal is to fully transform a property, a larger renovation gives you the flexibility to redesign and upgrade nearly every aspect of the home. While it requires more planning and time, it can deliver a finished product that truly matches your vision and long-term goals.
Real Strategy: Buy Smart, Build Equity
This loan is not just about fixing a home.
It is about making a strategic financial move that puts you in control of your investment from day one.
Instead of paying a premium for a fully updated property, you have the opportunity to buy a home with potential and unlock its value through improvements.
When you:
- Buy below market value
- Improve the home
- Increase its value
You are not just upgrading a property. You are actively creating equity almost immediately.
This approach allows you to benefit from both the purchase advantage and the added value from renovations, rather than relying solely on market appreciation over time.
That is how long-term wealth through homeownership is built, by making intentional decisions that increase value from the start.
As your home value increases, you may also have the option to refinance in the future to improve your rate or loan terms. When that time comes, understanding your VA refinance options including the IRRRL can make a big difference.
Who This Is Perfect For
This program is ideal for Veterans who want to make the most of their VA benefits and take a more strategic approach to homeownership.
It is a great fit if you:
- Want to fully maximize your VA loan benefits
- Are open to buying a home that needs some work
- Want to customize your home to match your style
- Feel priced out of move-in ready homes
- See the opportunity in today's market conditions
If you are willing to look beyond perfect listings, this loan can open up significantly more options and long term value.
If you are still deciding whether now is the right time to buy, our first-time buyer guide can help you evaluate timing, budget, and strategy with more clarity.
VA Renovation Loan Options for Manufactured Homes and Multi Unit Properties
One of the most exciting features of a VA Renovation Loan is its flexibility.
This program is not limited to traditional single family homes. Based on current guidelines, it can also be used for other property types that expand your options and buying power.
Manufactured Homes
Yes, you can use a VA Renovation Loan to purchase and improve a manufactured home, giving Veterans access to more affordable housing opportunities.
This can be a powerful option because:
- Lower purchase prices compared to traditional homes
- Ability to upgrade and modernize after closing
- Access to 0% down VA financing
This opens the door for buyers who may have felt priced out of the market but still want to own and improve a home.
Multi Unit Properties (2 to 4 Units)
You can also use this loan for multi unit properties, including:
- Duplex (2 units)
- Triplex (3 units)
- Fourplex (4 units)
As long as you occupy one unit as your primary residence, you may be able to:
- Live in one unit
- Renovate the entire property
- Generate rental income from the other units
Many Veterans start this way and later turn the property into a full rental after moving into their next home using their VA benefits again. This can become a powerful long term income strategy. If you want to understand how that works, check out our guide on turning a VA loan home into a rental property.
This is one of the most powerful ways for Veterans to combine homeownership with income potential and long term wealth building.
Can I Do the Renovations Myself? (DIY vs Licensed Contractor Requirements)
This is one of the most common questions Veterans ask when exploring renovation loans.
It is also one of the most important to understand upfront.
DIY Renovations Are Not Allowed
With a VA Renovation Loan, you cannot perform the work yourself, even if you have experience or a construction background.
All renovation work must be completed by a licensed and approved contractor.
This is a standard requirement and plays a key role in how the loan is structured and protected.
Why DIY Work Is Not Eligible
This requirement is designed to protect you, the property, and the lender throughout the renovation process.
Here is how it works:
- Quality and Safety Standards: Licensed contractors ensure all work meets VA property requirements and local building codes
- Proper Documentation: Contractors provide detailed bids, scope of work, timelines, and required documentation for loan approval
- Controlled Fund Disbursement: Funds are held in escrow and released in stages based on completed work and inspections
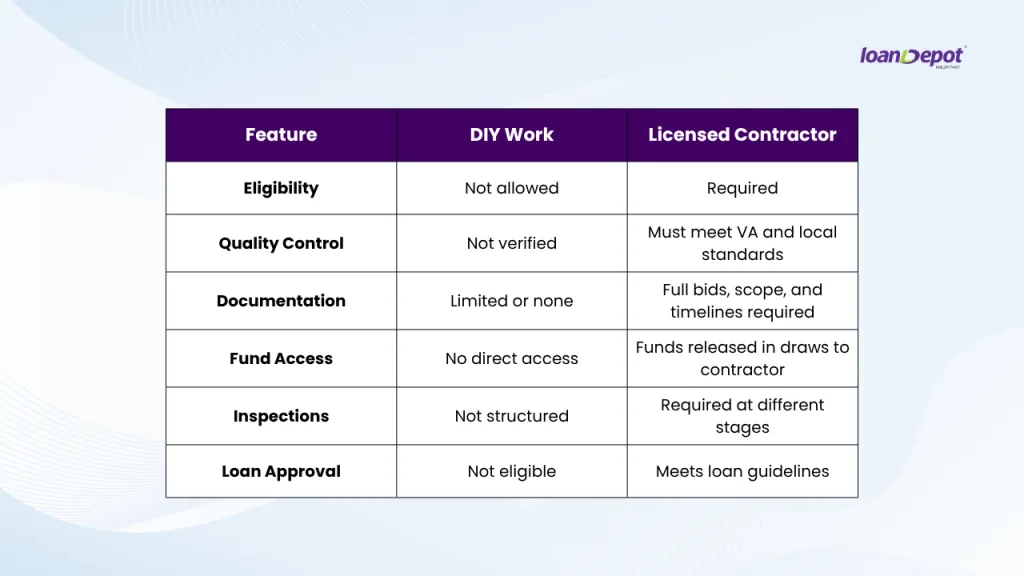
While it may feel limiting at first, this structure is actually designed to keep your project on track and protect your investment. Having licensed professionals involved helps ensure the work is completed correctly, on time, and up to standard.
In the long run, this reduces risk, prevents costly mistakes, and creates a smoother renovation experience from start to finish.
What This Means for You as a Veteran
Even if you are skilled or have construction experience, VA Renovation Loan guidelines require that all work be completed by a licensed contractor.
While that may seem restrictive at first, it actually removes a lot of pressure from your plate.
The good news? You are not expected to manage everything on your own.
A licensed contractor will:
- Help define a clear and detailed scope of work
- Provide accurate and realistic cost estimates
- Handle the execution of the renovation
- Keep the project aligned with loan guidelines and timelines
This allows you to focus on the bigger picture while experienced professionals handle the details.
Pro Tip: Choose the Right Contractor
Choosing the right contractor is one of the most important decisions you will make in this process.
The right partner can make the experience smooth and efficient, while the wrong one can create delays and frustration.
Look for someone who:
- Is fully licensed and insured
- Has proven experience with renovation projects
- Communicates clearly and consistently
- Understands timelines, budgets, and expectations
The right contractor combined with the right loan strategy creates a streamlined process and a finished home you can be proud of.
We also have trusted contractor recommendations to help make your search easier.
If you want guidance on the process or need help getting started, reach out to us or book a free call at talkingwithamy.com to talk through your VA Renovation Loan options.
What I'm Seeing Right Now in Sacramento and Roseville
In the Sacramento and Placer County markets, I'm seeing many buyers struggle with limited inventory and higher prices on fully updated homes.
Homes that need updates are often priced more competitively but require the right financing strategy.
This is where a VA renovation loan can give buyers an advantage by allowing them to purchase a home with potential and customize it after closing.
❓ VA Renovation Loan FAQs for Veterans
❓What credit score do I need for a VA Renovation Loan?
Many Veterans are surprised to learn that this program may allow credit scores as low as 600 FICO, depending on the full loan profile.
Your credit score is just one piece of the puzzle.
We also look at:
- Payment history
- Debt-to-income ratio
- Income stability
- Overall financial profile
If your score is close, there may be strategies to improve it quickly and get you qualified.
❓What documents do I need to apply for a VA Renovation Loan?
Getting pre-approved is easier than most people think when you know what to expect.
Typical documents include:
- Most recent pay stubs (covering 30 days)
- W-2s for the past 2 years
- Federal tax returns (if self-employed or required)
- Bank statements (usually 2 months)
- Certificate of Eligibility (COE) for VA benefits
- Photo ID
If you are self-employed or have multiple income sources, we may request additional documentation.
The goal is to clearly show your ability to repay the loan and support the renovation portion.
❓How does the renovation portion of the loan work?
The renovation funds are built directly into your loan.
Here's how it typically works:
- You choose a property
- A contractor provides a bid and scope of work
- The renovation cost is added to your loan amount
- Funds are held and released in stages as work is completed
This allows you to finance both the purchase and improvements with one loan and one payment.
❓Can I choose my own contractor?
In most cases, yes, but the contractor must meet specific guidelines.
This is important because:
- The lender needs to verify licensing and experience
- The work must meet VA property standards
- The project must be completed within required timelines
Having a qualified contractor is key to a smooth renovation process.
❓What types of renovations are allowed?
The renovations must add value and improve the livability of the home.
Allowed improvements may include:
- Kitchens and bathrooms
- Flooring and paint
- Roof replacement
- HVAC, plumbing, electrical
- Structural repairs
- Accessibility upgrades
Luxury upgrades may have limitations, but most functional improvements are allowed.
❓How long does a VA renovation loan take?
Because of the added renovation component, these loans can take a bit longer than a standard VA loan.
Typical timelines depend on:
- Scope of work
- Contractor bids and approvals
- Appraisal with renovation plans
Planning ahead and working with an experienced lender makes all the difference.
❓Can I use this loan for a fixer-upper that needs major repairs?
Yes, and this is one of the biggest advantages.
Whether the home needs:
- Light cosmetic updates
or - A full remodel
You can structure the loan based on the scope of work.
This gives you access to homes that many buyers overlook.
❓Can I use this loan to build equity?
Absolutely.
This is one of the smartest strategies available.
When you:
- Buy a home below market value
- Improve it
- Increase its appraised value
You are creating equity through your improvements.
This is how many homeowners accelerate wealth through real estate.
❓Is this better than waiting for the perfect home?
In today's market, waiting often means:
- Higher prices
- More competition
- Fewer options
With a VA renovation loan, you shift your strategy.
Instead of searching for perfect…
You create it.
Many Veterans are surprised to learn that this program may allow credit scores as low as 600 FICO, depending on the full loan profile.
Your credit score is just one piece of the puzzle.
We also look at:
- Payment history
- Debt-to-income ratio
- Income stability
- Overall financial profile
If your score is close, there may be strategies to improve it quickly and get you qualified.
Getting pre-approved is easier than most people think when you know what to expect.
Typical documents include:
- Most recent pay stubs (covering 30 days)
- W-2s for the past 2 years
- Federal tax returns (if self-employed or required)
- Bank statements (usually 2 months)
- Certificate of Eligibility (COE) for VA benefits
- Photo ID
If you are self-employed or have multiple income sources, we may request additional documentation.
The goal is to clearly show your ability to repay the loan and support the renovation portion.
The renovation funds are built directly into your loan.
Here's how it typically works:
- You choose a property
- A contractor provides a bid and scope of work
- The renovation cost is added to your loan amount
- Funds are held and released in stages as work is completed
This allows you to finance both the purchase and improvements with one loan and one payment.
In most cases, yes, but the contractor must meet specific guidelines.
This is important because:
- The lender needs to verify licensing and experience
- The work must meet VA property standards
- The project must be completed within required timelines
Having a qualified contractor is key to a smooth renovation process.
The renovations must add value and improve the livability of the home.
Allowed improvements may include:
- Kitchens and bathrooms
- Flooring and paint
- Roof replacement
- HVAC, plumbing, electrical
- Structural repairs
- Accessibility upgrades
Luxury upgrades may have limitations, but most functional improvements are allowed.
Because of the added renovation component, these loans can take a bit longer than a standard VA loan.
Typical timelines depend on:
- Scope of work
- Contractor bids and approvals
- Appraisal with renovation plans
Planning ahead and working with an experienced lender makes all the difference.
Yes, and this is one of the biggest advantages.
Whether the home needs:
- Light cosmetic updates
or - A full remodel
You can structure the loan based on the scope of work.
This gives you access to homes that many buyers overlook.
Absolutely.
This is one of the smartest strategies available.
When you:
- Buy a home below market value
- Improve it
- Increase its appraised value
You are creating equity through your improvements.
This is how many homeowners accelerate wealth through real estate.
In today's market, waiting often means:
- Higher prices
- More competition
- Fewer options
With a VA renovation loan, you shift your strategy.
Instead of searching for perfect…
You create it.
Final Thought
This program is designed to set you up for success from the very beginning.
While DIY projects are not allowed with a VA Renovation Loan, having the right team in place ensures your home is completed safely, correctly, and built to last.
With the right strategy, the right contractor, and the right guidance, you are not just renovating a home. You are creating a space that fits your life while building long term value at the same time.
VA Loan YouTube Playlist
Visit my YouTube channel where I break down VA loans in simple, easy-to-understand videos, including:
- How VA loans work
- 100% financing explained
- Seller-paid closing costs
- Common mistakes to avoid
- Strategies to get your offer accepted
These videos are designed to help you understand your options so you can move forward with clarity and confidence.
VA Loan Resource Hub
We've also created a dedicated VA Loan Hub where you can explore:
- Step-by-step home buying guidance
- VA loan eligibility and benefits
- Credit tips and approval strategies
- Real-world examples and scenarios
This is your go-to resource for everything VA loan related, all in one place.
Meet Amy DeBusk | VA Loan Specialist & Branch Manager
Amy DeBusk is a Branch Manager at LoanDepot and a nationally recognized mortgage advisor with over 26 years of experience in the lending industry.
She specializes in helping Veterans fully understand and maximize their VA loan benefits.
Over the years, Amy has helped hundreds of Veterans:
- Purchase homes with 0% down
- Structure offers that get accepted
- Navigate credit and qualification challenges
- Build long-term wealth through homeownership
What sets Amy apart is her ability to simplify the mortgage process and guide her clients every step of the way with clarity, strategy, and care.
Her mission is simple:
- To make the home loan process easy to understand
- To help Veterans feel confident in their decisions
- To create a path to homeownership that actually works
If you are a Veteran and want expert guidance from someone who truly understands VA loans, you're in the right place.
📞 (916) 705-2557
🌐 amydebuskhomeloans.com
📅 talkingwithamy.com
All loans subject to approval. Equal Housing Lender.
All Mortgage Made Easy articles · Book a Complimentary Discovery Call