Why Self-Employed Buyers Choose Bank Statement Loans in Sacramento and Roseville
The Bank Statement Loan is built for self-employed professionals whose tax returns do not reflect their actual income. Instead of relying on your taxable income, the lender reviews your actual deposits.
This means your income is calculated from:
- Client payments
• Invoices paid
• Recurring ACH deposits
• Zelle and Venmo business payments
• Stripe, PayPal, and Square revenue
• Contract income
• Retainers and service fees
This program honors your business activity and the way you truly earn money.
If you are shopping for a home in Sacramento CA, Roseville CA, Lincoln, Auburn, or surrounding suburbs, and you want a lender who finally understands self-employment, this program is for you.
Minimum Credit Score and Down Payment Requirements
To keep everything clear and compliant, here are the two most important guidelines you must know:
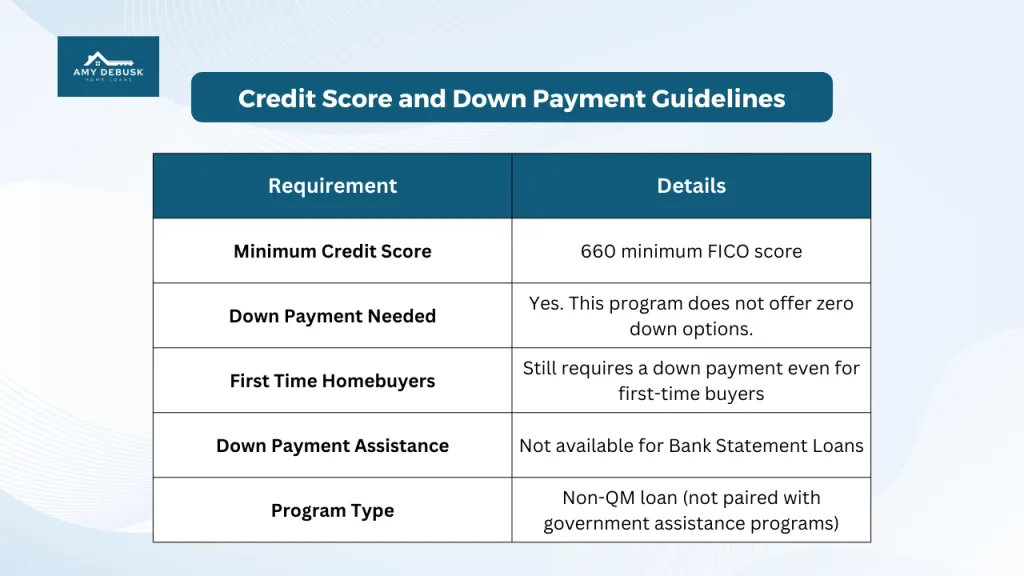
Minimum FICO score is typically 660
This ensures the program remains stable and beneficial for borrowers, lenders, and the long-term financial system.
Down payment is required
This is NOT a zero-down loan. Even if you are a first-time homebuyer, a down payment is necessary.
No Down Payment Assistance Programs (DPA) are available for Bank Statement Loans
Since these are non-QM (non-qualified mortgage) loans, they do not pair with government-sponsored assistance programs.
If you are working to improve your credit score or financial foundation, you can review my 👉 Credit Health Page here:
It guides you through the exact steps to strengthen your credit profile so you can qualify confidently.
Who Qualifies for a Bank Statement Loan
The strength of these programs lies in their flexibility and fairness. Here's who benefits most:
1. Borrowers with at least 12-24 months of self-employment
However, here's the part almost nobody tells you:
You may qualify with only 12 months of self-employment if you have at least 2 years of experience in the same field.
This rule changes everything for so many Sacramento and Roseville residents.
Let me share a real example.
A Powerful Real-Life Example: The RN Who Qualified After Only One Year of Self-Employment
A client of mine worked as an RN in a Sacramento hospital for five years. She loved her patients, she loved her job, and she was exceptional at her work. But she wanted more financial freedom, more flexibility, and more time with her family.
Last year, she founded her own in-home nursing care company, serving patients directly in their homes.
She became self-employed only 12 months ago.
But because she had:
- Five years of RN experience
• The same profession
• The same skillset
• A new business in the same field
• Strong, consistent deposits
She qualified easily for a Bank Statement Loan.
This same rule applies to:
- Stylists who leave a salon to rent their own suite
• Therapists who leave a clinic to open private practice
• Electricians who start their own contracting company
• Realtors who leave salaried sales roles
• Consultants leaving corporate jobs
• Personal trainers opening their own studio
You do NOT need two years of self-employment if your profession is continuous and aligned.
This is one of the areas where Amy DeBusk Home Loans truly stands out. I understand the deeper layer of guidelines and help my buyers qualify even when other lenders say no.
Two Ways to Qualify: Personal Bank Statements or Business Bank Statements
Depending on how you pay yourself, you can qualify through two different methods.
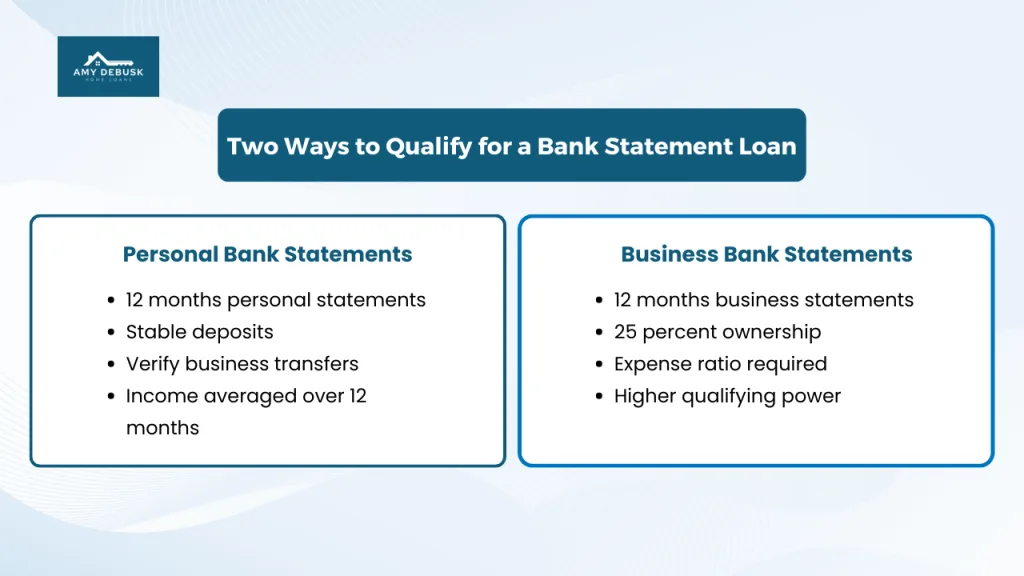
Option 1. Personal Bank Statement Loans
These use your personal bank account to calculate qualifying income.
Requirements:
- 12 consecutive months of personal bank statements
• Statements must reflect stable, predictable deposits
• Any unusual deposits explained
• Two months of business bank statements to verify transfers
• Business existence verified
• No excessive overdrafts or NSF activity
How income is calculated:
The lender totals 12 months of deposits, subtracts non-income items, and divides by 12 for a monthly income average.
This method is ideal when you pay yourself regularly from your business.
I walk you through this step-by-step so you know exactly what your income looks like through the lender's eyes.
Option 2. Business Bank Statement Loans
These use your business account instead.
Requirements:
- 12 consecutive months of business bank statements
• Documentation of business ownership (minimum 25 percent)
• Expense ratio (CPA letter or standard 50 percent expense factor)
• No excessive overdrafts
• Stable, predictable deposits
How income is calculated:
The lender analyzes:
- Total eligible deposits
• Expense ratio
• Ownership percentage
Then divides by 12 for qualifying income.
Business bank statement loans often allow for significantly higher qualifying power, especially for high-grossing businesses.
These loans are a specialty at Amy DeBusk Home Loans, and my team handles the income calculation for you so you always know what to expect.
What Counts as a Real Deposit
Not all deposits count. Eligible deposits include:
- Client payments
• Zelle or Venmo business payments
• ACH transfers from payment processors
• Checks from clients
• Regular contracted income
Non-eligible deposits include:
- Transfers between accounts
• Returned items
• Loans
• Gifts
This is where having an expert matters. My team helps you structure deposits correctly and identify which ones qualify.
Why Self-Employed Buyers in Sacramento and Roseville Choose This Program
Entrepreneurs love this loan program because it aligns with the way they really earn.
Benefits include:
- No tax returns needed
• No need to explain deductions
• Higher qualifying income
• No profit-and-loss statement unless elected
• Works for new businesses in your same field
• Faster underwriting
• Clear documentation requirements
Many buyers tell me they feel like they finally found the loan that "gets them."
This is why many call Amy DeBusk Home Loans the best mortgage broker for self-employed loans in Sacramento CA and Roseville CA.
Strengthening Your Profile Before You Apply: Credit Health and Financial Readiness
If you are working on improving your credit or preparing yourself for a stronger approval, you can access my Credit Health Page here:
👉
It walks you through how to:
- Improve your credit
• Lower your revolving balances
• Build a stronger financial foundation
• Prepare for the best loan terms possible
This page is one of the most visited resources on my site because it gives simple, actionable steps.
You can also download my Homebuying Guide for 👉👉California Buyers here:
This guide is your roadmap from start to finish.
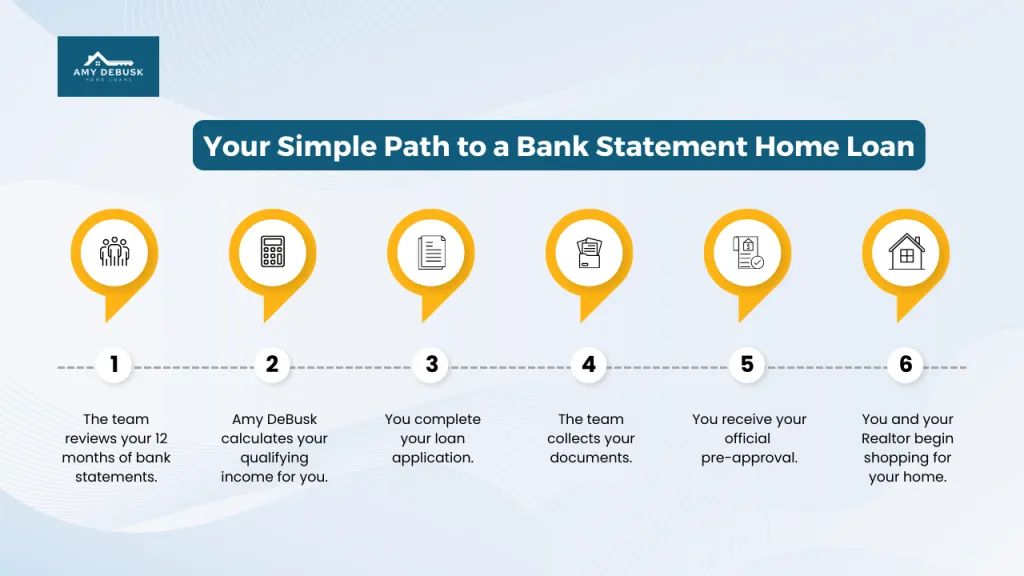
1. Strengthen Your Pre-Approval
A strong, up-to-date pre-approval shows sellers that you are a serious and qualified buyer. It also helps you understand your exact numbers, including monthly payments, closing costs, and maximum purchase price.
2. Review Loan Programs That Fit Your Situation
Many Self Employed buyers qualify for:
- 1099 Income programs
- 24 Month Bank Statement Program
- 12 Month Bank Statement program
- Permenant rate buydowns
Understanding your financing choices early helps you shop strategically and choose the best path toward homeownership.
To explore these options in more detail, you can visit our mortgage products page.
3. Start Touring Homes to Learn the Market
Even if you are not ready to write an offer today, touring homes helps you:
- Understand pricing in your preferred neighborhoods
- Identify the features that matter most to you
- Compare real homes to online listings
- Recognize a great opportunity when you see one
4. Work With a Mortgage Planner Who Knows the Local Market
Local experience matters when you are making one of the biggest financial decisions of your life. Amy and her team specialize in guiding buyers throughout Sacramento, Roseville, and surrounding communities with clear strategies, personalized loan options, and up-to-date market insights.
Working with a team that fully understands local pricing trends, lending guidelines, and negotiation opportunities can make your home-buying experience smoother from start to finish.
If you would like to get a feel for what it is like to work with Amy, you can check out her Google reviews to see real feedback from clients who have trusted her with their home financing journey.
Final Thoughts: You Are Far Closer to Your Home Purchase Than You Believe
Being self-employed is a powerful choice. It means freedom, creativity, and financial possibility. And now your mortgage options match that same energy.
You deserve a home loan that actually understands your income. You deserve a lender who sees your potential and guides you with clarity. You deserve a path that aligns with the life you are building.
If you are a business owner, entrepreneur, or independent professional in Sacramento CA, Roseville CA, Placer County, or anywhere in California, you can begin your path today.
All loans subject to approval. Equal Housing Lender.
Whenever you are ready, you can schedule your appointment here:
👉 TalkingWithAmy.com
Your homeownership journey is unfolding perfectly.
Your business is powerful.
Your income is real.
Your home is closer than you think.
To help you take the next step, you can also use these helpful tools:
- Mortgage Calculator: Estimate your monthly payment and get a clearer picture of your budget.
- Tax Savings Calculator: Calculate your potential savings and see how homeownership may benefit you financially.
Frequently Asked Questions
❓ 1. What exactly is a bank statement loan for self-employed borrowers?
A bank statement loan allows you to qualify for a mortgage using 12 to 24 months of personal or business bank statements instead of relying on W-2s or tax returns. This is ideal for self-employed borrowers because it evaluates your actual deposits, giving a much more accurate reflection of your true income.
At Amy DeBusk Home Loans, I specialize in this loan type for entrepreneurs in Sacramento CA and Roseville CA.
❓ 2. What credit score is required?
A minimum 660 FICO score is typically required for Bank Statement and 1099 loans.
❓ 3. How much down payment do I need?
You need twenty percent down. There are no down payment assistance programs for these loans. 100% of the funds for your down payment can be a gift from a family member. You also need 6 months reserves of your own money. A seller can contribute up to 6% of the purchase price towards your closing costs.
❓ 4. What counts as reserves?
Reserves include savings, retirement accounts, investment accounts, business funds, and money market accounts totaling six months of future mortgage payments.
❓ 5. What deposits count as income?
Eligible deposits include client payments, contract income, Zelle or Venmo business deposits, Stripe, PayPal, Square deposits, and other business revenue.
❓ 6. Can I combine my spouse's W-2 income with my self-employment income?
Yes, this is one of the strongest approval strategies for entrepreneurial couples.
❓ 7. What if my bank statements do not show enough income?
We can request a CPA letter verifying your true business expense percentage, which can increase your qualifying income significantly.
❓ 8. How long do I need to be self-employed?
Twelve months of self-employment if you have at least two years in the same field, or two years of self-employment if you changed industries.
❓ 9. Can I get a seller credit with a bank statement loan?
Yes, a seller is allowed to give you up to 6% of your purchase price, the seller credit cannot exceed your closing costs.
Have more questions? Ask our Bank Statement Loan AI Expert:
Connect With Amy
If you are ready to take the next step or simply want expert guidance, you can reach out to Amy directly for personalized support.
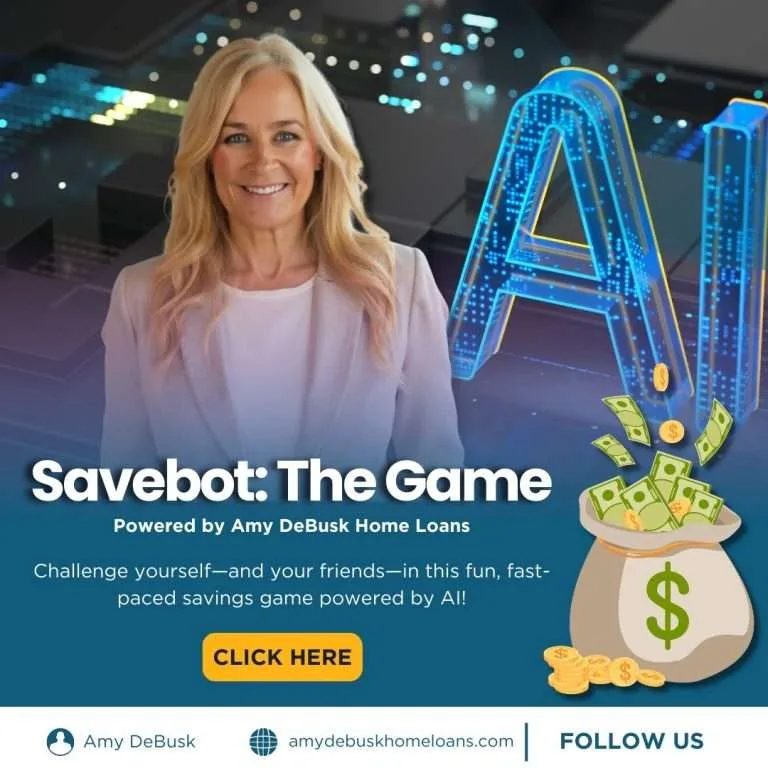
Savebot: The Game - A Fun Way to Strengthen Your Savings Muscle
If you want an easy, fun way to stay motivated with your savings goals, Savebot: The Game is the perfect place to start. It's a fast-paced, AI-powered challenge designed to help you build better financial habits without stress or overwhelm. You can play solo or invite friends and family to join you, making it a lighthearted way to strengthen your money mindset while staying consistent with your goals.
This isn't just a game - it's a tool that helps you practice the same financial awareness and clarity you'll use when preparing to buy a home. A strong savings rhythm creates confidence, opens options, and helps you move toward homeownership with ease and excitement.
Explore Our Self Employed & Bank Statement Loan Playlist
If you want clarity, confidence, and fresh insight as you plan your next move, I've put together a playlist packed with quick, helpful videos designed to guide you through today's market. Whether you're a first-time buyer, a seasoned homeowner, or someone exploring your options for 2026, these videos break everything down in a simple, encouraging way.
Inside the playlist, you'll find:
Inside this playlist you'll learn:
• How bank statement loans work in 2026
• How lenders calculate income using deposits
• How to qualify as a 1099 contractor or business owner
• What documents you really need
• How to avoid mistakes that hurt approval
• How to prepare your finances the smart way
• Real examples and strategies used by successful clients
• Expert insights for Sacramento, Roseville, Placer County & beyond
Each video is designed to make mortgages easy, reduce stress, and help you understand exactly what lenders look for - especially when your financial picture is more complex than a standard W-2 buyer.
As a Mortgage Loan Officer with 25+ years of experience serving self-employed homeowners, I'm here to guide you through every step with clarity, confidence, and a high-vibration mindset.
Whether you're preparing to buy now or planning for the future, this playlist gives you the tools and strategies to move forward powerfully in your homeownership journey.
Each video is designed to help you understand the market, learn your options, and feel supported every step of the way. You can watch the full series here:
👉Self Employed & Bank Statement Loans Best Options 2026
These videos are part of my ongoing mission to make homeownership simple, clear, and achievable for buyers throughout Sacramento, Roseville, Placer County, and beyond. Let this playlist be your go-to resource whenever you need guidance, motivation, or a fresh perspective on your homebuying journey.
All loans subject to approval. Equal Housing Lender.
All Mortgage Made Easy articles · Book a Complimentary Discovery Call