Home Equity & Retirement Hub
More possibilities for the home and retirement you envision.
More time with your grandkids. The trip you have been putting off. The possibility of working less or retiring sooner. You have put years into your home, and its equity may help support the life you want next. I'll help you explore how a reverse mortgage could fit your retirement plans and spending plan.
Book Your Complimentary 30-Minute Discovery CallWhat would you like your home to make possible?
Explore staying in your home, buying a home for your next chapter, or a reverse second mortgage that may let you keep your current first mortgage. Eligibility and availability vary. If you are still deciding whether to move, start with a smaller home with more room for living.
If you are planning after the loss of a spouse, this page offers a gentler starting point. You can also go directly to the common questions or complimentary guide.
What would you love to have more time for?
Maybe retirement means being there for weekday school pickups, taking a longer visit with family, or finally traveling without scheduling around work. Perhaps you simply want more room in your monthly spending plan so you can enjoy the home and community you love.
For some homeowners, using home equity through a reverse mortgage may make it possible to reduce work hours or revisit their retirement timeline. For others, the goal is to move closer to the grandkids or make everyday life more comfortable. We'll begin with what matters to you, then compare the numbers, costs, and effect on your remaining equity. Any change to your retirement date should fit your complete financial plan, including future living and care expenses.
Access funds without adding taxable income from the loan proceeds.
A reverse mortgage can be a strategic part of retirement planning. The funds you receive are borrowed money, not earnings, so receiving reverse mortgage proceeds does not itself create federal taxable income. That may give you another source of cash to consider alongside your retirement income and savings. The IRS explains how reverse mortgage proceeds are treated.
I'll help you understand the mortgage side, and we can include your tax professional or financial advisor in the conversation about how it fits your overall plan. We'll weigh the flexibility against borrowing costs, the growing loan balance, and the equity you want to preserve.
How your home equity may support those plans
A reverse mortgage is one financing option we can explore together. Let's connect the possibilities to how the loan actually works.
A Home Equity Conversion Mortgage (HECM) is an FHA-insured reverse mortgage for eligible borrowers age 62 and older. You continue to own your home. There is no required monthly principal-and-interest payment while you meet the loan's obligations, but interest and mortgage insurance charges add to the balance. Your equity can decrease over time.
You must live in the home as your principal residence, keep it maintained, and pay property taxes, homeowners insurance, and other applicable property charges. Let's look at those expenses alongside your other priorities so the complete picture makes sense.
More ordinary days together.
Backyard lunches, school-day visits, and time to hear every story. What would you like to make more room for?
Stay in the Home You Love
Use a Home Equity Conversion Mortgage (HECM) to explore the possibilities in your current home.
Your home may be where the grandkids gather, where you know your neighbors, and where you want to enjoy retirement. If an existing mortgage payment is taking up a large part of your spending plan, a HECM may free up monthly cash flow for visits, hobbies, or everyday breathing room while you stay in that familiar place. We'll account for the expenses that continue and the loan balance that grows.
You do not have to own your home free and clear to explore a HECM. An existing mortgage must be paid off at closing, usually using part of the reverse mortgage proceeds. If the available proceeds do not cover the required payoff and costs, you would need another eligible source of funds.
Depending on the loan structure, available funds may be received as a lump sum, a line of credit, scheduled advances, or a permitted combination. Fixed-rate and adjustable-rate options have different payout choices. A line of credit is borrowing capacity secured by your home, not an investment account or interest earned on your money.
The amount available depends on factors including the applicable age, interest rate, eligible property value, program limits, existing liens, costs, and any required set-asides. There is no single percentage of home equity that every borrower receives. I will help you compare a personalized illustration with your plans.
A new address. More time with the people you love.
Your next home could bring family closer and make everyday life a little easier.
Buy Your Next Home
A Home Equity Conversion Mortgage (HECM) for Purchase can help finance your next chapter.
Imagine being a short drive from the grandkids, having a guest room ready for family, or choosing a single-story home that is easier to enjoy and maintain. Your next move could mean less time caring for a house and more time doing what you love.
A Home Equity Conversion Mortgage (HECM) for Purchase may help you make that move without committing all your available cash to an outright purchase. It combines your required funds with reverse mortgage financing to buy a new primary residence in one transaction. We'll compare that approach with paying cash or using a traditional mortgage, including the costs and remaining equity.
You bring a substantial monetary investment plus any costs not financed. There is no universal down payment percentage: your age, the property value and price, interest rate, available proceeds, and closing expenses affect the amount. I will work through the numbers before you build your home search around them.
Funds must come from permitted, documented sources. Sale proceeds, eligible assets, and qualifying gifts may be possibilities. We will review the source and timing early, especially if you are also selling a home. Any existing HECM must be paid off as required before the new transaction is completed.
Borrowers and any eligible non-borrowing spouse must occupy the new home within 60 days of closing. Eligible properties may include qualifying single-family homes, two- to four-unit homes with you occupying one unit, eligible condominiums, and qualifying manufactured homes. Property and FHA requirements still apply.
This is not a construction or renovation loan. A newly built home must be complete before closing, and required repairs must be finished before closing. Your new home should support the life you want now and the way you expect to live in the years ahead.
Make time for the places you have wanted to see.
Whether it is a weekend away or a longer visit with family, let's talk about the experiences you want your retirement plan to support.
Find an option that supports your kind of retirement.
Staying close to friends, moving near family, or creating more flexibility for travel can call for different financing choices. Start with the life you want, then explore the option that may help you get there.
Age 62 and older
Home Equity Conversion Mortgage (HECM)
Explore home equity for your current primary residence, with no required monthly principal-and-interest payment while obligations are met.
Explore staying in your home →
Age 62 and older
Home Equity Conversion Mortgage (HECM) for Purchase
Combine your required investment with a reverse mortgage to purchase a new primary home.
Explore buying your next home →
Separate eligibility rules
Hybrid Reverse Mortgage
A refinance option with required partial-interest payments for 10 years. Age and state eligibility differ from HECM.
Understand the hybrid option →
Lump-sum reverse mortgage
HomeSafe Standard
Explore a proprietary reverse mortgage for an eligible primary-home purchase or refinance, with a lump-sum structure.
Explore this option →
First-time reverse mortgage borrowers
HomeSafe Intro
An option designed to help eligible first-time reverse borrowers who would otherwise need additional funds to close.
Explore this option →
Reverse mortgage line of credit
HomeSafe Select Intro
Explore a proprietary line-of-credit option with its own initial draw, qualification, and state availability requirements.
Explore this option →
Keep your existing first mortgage
HomeSafe Second Mortgage
Access eligible equity with a reverse second mortgage. Your first-mortgage payments and property expenses continue.
Explore this option →Prefer to compare traditional financing too? Explore refinance options and the full Home Loans for Retirement collection.
More Ways to Explore Your Equity
More ways to make room for what matters.
Your retirement may include travel, family gatherings, home improvements, or simply the freedom to take things at your own pace. If a traditional HECM doesn't fit your situation, we can explore whether a HomeSafe option supports those goals. I'll help you compare the benefit today with the effect on your equity over time.
HomeSafe products are proprietary reverse mortgages, separate from the FHA-insured HECM program. They may offer another way to use equity in an eligible primary residence. Age requirements begin at 55 for certain products and states, with higher ages in some states. Availability and qualification must be checked for the specific option and location.
These options have no required monthly principal-and-interest payment on the reverse mortgage while you meet its obligations. Interest adds to the balance, so the amount owed can grow and your remaining equity can decrease. You must continue paying property taxes, insurance, applicable fees, and maintaining and occupying the home as required. Closing costs still apply even though the supplied chart lists no mortgage insurance premium for these proprietary options.
HomeSafe Standard: plan for the next chapter you want
Perhaps you want to adapt your home for the years ahead or create more financial flexibility as you spend more time with family. Having access to a lump sum may support a defined goal. We'll decide how much you actually need and consider the cost of borrowing those funds.
If you want to explore a larger-equity reverse mortgage, HomeSafe Standard is a lump-sum option for eligible purchases and refinances. For a refinance, we will account for the existing liens that must be paid off, closing expenses, and the funds available to you. For a purchase, we will review your required investment alongside the new loan.
I'll compare the available proceeds, costs, and projected balance with HECM and other eligible choices. A larger available amount is only useful if the complete structure supports your spending plan and longer-term goals.
HomeSafe Intro: explore a possibility you thought was out of reach
If you have looked into a reverse mortgage before and the funds needed at closing made it difficult, your plans may deserve another look. Whether your goal is less pressure on your spending plan or more time away from work, I'll help you see whether this option changes the picture.
HomeSafe Intro is designed for first-time reverse mortgage borrowers who face a gap between available loan proceeds and the funds needed to close. Its higher loan-to-value structure compared with Standard may help an eligible borrower reduce that gap.
First-time reverse borrower does not mean first-time homebuyer. You may have owned your home for years and still be considering a reverse mortgage for the first time. This option cannot refinance an existing reverse mortgage, and the borrower must pass the financial assessment. I'll compare it with Standard and applicable HECM options so you can see the differences in proceeds, costs, and equity over time.
HomeSafe Select Intro: plan for needs that unfold over time
Retirement plans are not always a single purchase. You may be thinking about a family visit this year and changes to your home later. A line-of-credit structure may offer flexibility in when you access eligible funds, within its draw requirements. We'll compare that flexibility with the costs and loan terms.
The supplied comparison chart lists HomeSafe Select Intro as a separate adjustable-rate line-of-credit option. It requires an initial draw at closing rather than leaving the entire approved amount undrawn. The amount and timing of later access are governed by the loan terms.
This is distinct from HomeSafe Intro's lump-sum structure and from a traditional HELOC. We will confirm current availability, draw rules, and product-specific eligibility before using it in your plan. Purchase transactions require case-by-case review. It is also distinct from the discontinued HomeSafe Select product.
HomeSafe Second: keep what works and explore what's next
You may love your home and feel comfortable with your current mortgage, but want access to equity for improvements, family time, or other priorities. This option lets us explore those possibilities while keeping an eligible first mortgage in place.
If your existing first mortgage works well for you, replacing it may not be the approach you want. HomeSafe Second adds a reverse mortgage in second lien position, allowing eligible homeowners to access additional equity while retaining their first mortgage.
Your first mortgage payment does not go away. You must continue meeting that loan's payment and other obligations. The reverse second mortgage does not require its own monthly principal-and-interest payment while its terms are met, but its balance grows as interest accrues. Taxes, insurance, and other homeowner responsibilities continue.
The supplied comparison chart describes a lump-sum second mortgage for an existing home, not purchase financing. I'll review the type and balance of your first mortgage, your payment history, your property, and the applicable financial assessment. We can also compare a home equity loan or HELOC so you understand the differences in payments and repayment.
Let's choose around your goals and the full cost, not simply the largest available loan. Book your complimentary 30-minute discovery call and bring your current mortgage statement and questions.
Let's turn your retirement vision into a plan you understand.
Tell me what a good week in retirement would look like for you. More afternoons with family? Time to travel? Fewer hours at work? That conversation gives our loan comparison a purpose. Then we'll review what is realistic for your home, income, and longer-term needs.
- Start with your goals. We'll start with the people, activities, and plans you want more time for, then review your home, current mortgage, income, and spending plan.
- Compare illustrations. Review available proceeds, costs, projected balances, ongoing expenses, and alternatives.
- Complete independent counseling. HECM counseling with a HUD-approved agency is required. You choose the agency, and your spouse may also need counseling.
- Review your finances and property. The financial assessment, title review, and appraisal help determine whether the loan and home meet requirements.
- Plan beyond closing. Understand property-charge payments, occupancy certifications, repayment events, and your family's questions.
The assessment includes your income, assets, debts, and payment history. Depending on the findings, funds may need to be set aside for property expenses. That reduces the amount available for other uses, so we will account for it in your plan.
Keep learning at your own pace.
Our moving back to California article explores retirement financing in the context of a move. For independent education, visit HUD's HECM resources and the CFPB reverse mortgage resource center.
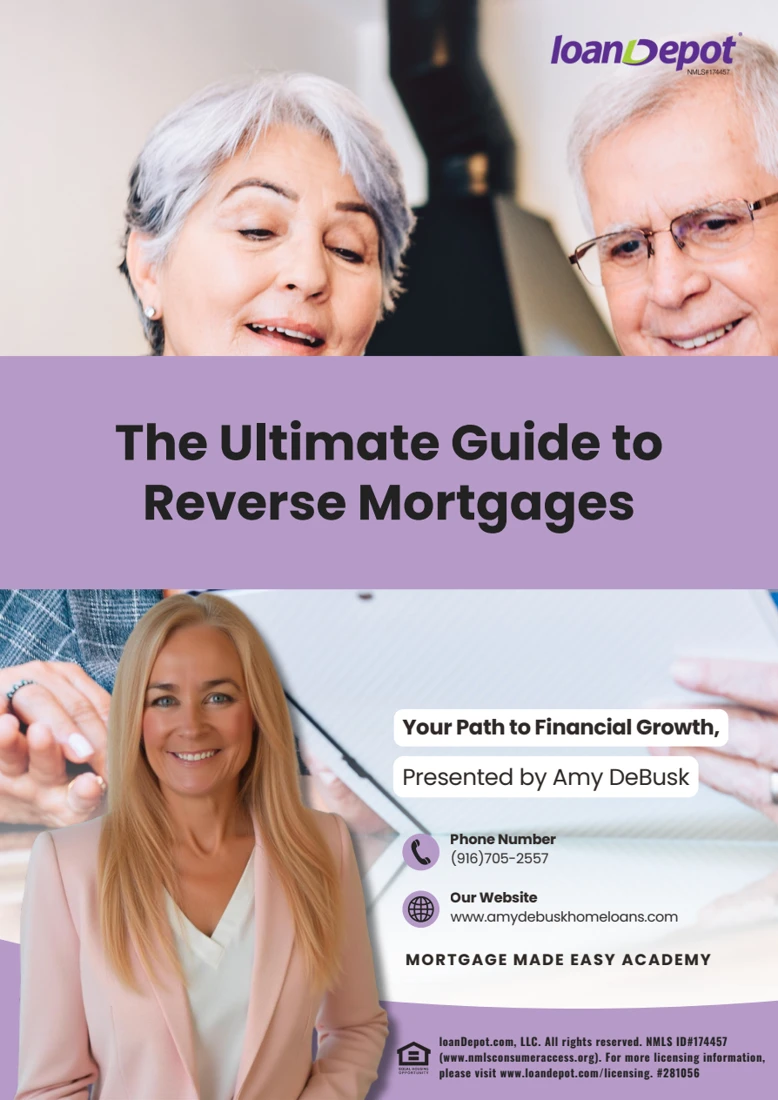
Your Complimentary Guide
The Ultimate Guide to Reverse Mortgages
Give yourself time to explore what your home equity could make possible. Download my guide to read at your own pace, share with your family, and keep your questions handy for our conversation.
Whether you're thinking about staying in your home or planning your next chapter, I'm here to help you connect the information to your goals.
Download Your Complimentary GuidePDF · 5 pages · No sign-up required
Your reverse mortgage questions, answered.
Are reverse mortgage proceeds taxable income?
No. The IRS treats reverse mortgage advances as loan proceeds, not taxable income. This can make home equity a useful resource to consider in your retirement plan. The loan still carries costs and must be repaid under its terms. Your tax professional can help you evaluate the rest of your tax situation.
Do I still own my home?
Yes. A reverse mortgage places a lien on your home; it does not transfer ownership to the lender. You must continue to meet occupancy, maintenance, and property-payment obligations. Not meeting those obligations can lead to the loan becoming due and possible foreclosure.
Can I get a HECM at 55?
HECM borrowers must be at least 62 at approval. Some separate proprietary or hybrid options have younger starting ages, subject to state and product rules. We will keep those choices separate when reviewing what fits.
Can I qualify if I still have a mortgage?
Yes, having a mortgage does not automatically rule you out. The existing loan must be paid off at closing, and available HECM proceeds must cover the required obligations or be supplemented with eligible funds. I will compare your balance with a personalized estimate.
What expenses will I still pay?
You remain responsible for property taxes, homeowners insurance, maintenance, and applicable association fees or other property charges. A HECM also has closing costs and mortgage insurance. No required monthly principal-and-interest payment does not mean your home has no ongoing costs.
How much do I need to buy a home with a HECM?
Your required investment depends on the loan calculation and the home you choose, plus costs not financed. It is not a standard low-down-payment mortgage. We will verify your funding sources and estimate the funds needed before you make an offer.
What if my spouse is younger than 62?
A younger spouse may be considered an eligible non-borrowing spouse when the requirements are met. That status has specific protections and responsibilities, and it is not the same as being a borrower. We will review age, occupancy, counseling, and what happens if the borrowing spouse dies or leaves the home.
What happens when I sell or move?
A HECM generally becomes due when the home is sold or is no longer a qualifying principal residence, subject to applicable co-borrower and spouse protections. Long absences, including time in a care facility, need careful review. Tell me about your plans so we can discuss repayment before you commit.
Can my children inherit the home?
Yes, but the reverse mortgage must be addressed when it becomes due. Heirs who want to keep a HECM-financed home can generally repay the lesser of the balance or 95% of its appraised value, following the servicing requirements and deadlines. They may instead sell it and retain remaining equity after repayment and costs. Read the CFPB explanation for families.
Your next chapter starts with a conversation.
What have you been looking forward to: a trip, more time with your grandkids, or the chance to step back from work? Bring that vision and your questions to our conversation. Invite a family member or trusted advisor if you would find that helpful. I'll help you understand whether your home equity can play a useful role in making your next chapter possible.
Book Your Complimentary 30-Minute Discovery CallHECM guidance reviewed using September 2026 underwriting materials and public HUD and CFPB resources. Qualification and property approval are required. Separate retirement loan products have their own requirements.
Serving homebuyers and homeowners in Roseville, Rocklin, Lincoln, Citrus Heights, Antelope, Fair Oaks, Carmichael, Sacramento, and across California, Tennessee, and Texas.