What Is Down Payment Assistance?
Down payment assistance helps eligible buyers with some of the money needed to buy a home. Depending on the program, it may help with your down payment, closing costs, or both. It works alongside your home loan, with its own eligibility rules.
Some assistance is a grant. Some is a second loan that must be repaid, and some can be forgiven after specific conditions are met. Amy and our team will explain the terms before you decide, including any extra payment or future repayment obligation.
Three common questions about down payment assistance
Watch this short video for a helpful starting point, then let’s review how current program rules and your own financing picture fit together.
Assistance mortgage options to explore
Each program has its own mortgage type, eligibility rules, and assistance structure. Start with the option that sounds most relevant, then we can compare the full payment and upfront costs together.
 California first-time buyers
CalHFA Assistance
Explore CalHFA first mortgages and assistance programs, including the education, income, and occupancy questions to review.
Explore CalHFA → FHA + solar project
Solar DPA 100% Financing
Explore FHA financing that can pair an eligible solar project with assistance for qualified buyers.
Explore solar financing → California purchase assistance
GSFA Platinum
See how GSFA Platinum assistance may pair with eligible FHA or conventional first mortgages.
Explore GSFA Platinum →
Let’s compare the options with your real numbers.
Assistance is only helpful when the full payment, repayment terms, and cash you need at closing fit your plan. Bring your questions, and I’ll help you sort through the programs worth exploring.
Three Options to Explore With Our Team
These programs work differently. We'll compare the assistance, your full mortgage payment, and any added costs so you can choose a house spending plan that feels comfortable.
AccessZero | FHA Down Payment Assistance
AccessZero pairs an eligible FHA purchase loan with down payment assistance through Arrive Home. It can help first-time and repeat buyers purchasing a primary residence.
- Up to 3.5% assistance with a qualifying credit score of at least 600.
- Up to 5% assistance with a qualifying credit score of at least 660.
- Assistance is calculated on the lower of the purchase price or appraised value. On a $400,000 home appraised at $400,000, those options would be $14,000 or $20,000, subject to approval.
- This is a repayable second mortgage, not a grant. You make monthly principal-and-interest payments over 10 years, in addition to your FHA mortgage payment.
Your credit score is one part of qualifying. Amy and our team also review income, debts, the property, and other requirements. First-time buyers complete homebuyer education; buyers of two- to four-unit homes also complete landlord education.
Plan for both payments. We'll show you the cost of the FHA mortgage and the assistance loan together. If you want to refinance within the first three years, the assistance provider will not agree to keep its loan behind a new first mortgage, so you may need to pay off the second loan as part of that refinance. We'll explain this before you choose.
 Explore the bigger pictureYour California DPA guideExplore grants, deferred loans, and local assistance, plus the questions to ask when comparing your options.Explore the guide →
loanDepot AccessOne | Help With a Conventional Loan
AccessOne combines an eligible Fannie Mae HomeReady conventional mortgage with a loanDepot grant. It is a conventional option, not assistance added to an FHA loan.
- A loanDepot grant of up to $3,000. The program provides a 2% contribution, capped at $3,000, toward eligible purchase costs.
- An additional $2,500 credit may be available. Eligible buyers with qualifying income at or below 50% of the area's median income may receive this Fannie Mae credit when at least one occupying borrower is a first-time buyer.
- Income limits apply. For the loanDepot grant alone, qualifying income must be at or below 80% of the area median income for the home's location. We'll look up the dollar limit for you.
- For a home you will live in. Credit, property, mortgage insurance, and loan approval requirements apply. Homebuyer education may also be required.
For an eligible one-unit purchase, the program has a minimum borrower contribution of 1% of the purchase price; eligible gifts or the qualifying Fannie Mae credit can help meet it. That does not mean every buyer needs only 1% to close. The grant cap, required total down payment, and closing costs determine the remaining amount.
For example, a $400,000 purchase with a 3% down payment requires $12,000 down. A $3,000 grant leaves $9,000 of that down payment to cover before any additional eligible help, plus closing costs. This is a down-payment illustration, not a loan quote.
Could it fit you? AccessOne may be worth exploring if you qualify for conventional financing, meet the income limits, and could use help with upfront expenses. Amy and our team will calculate your actual contribution and any credit available to you.
Some grant options are limited to certain areas, and eligibility may depend on where you live now. Read Amy's guide to grant money in Riverside and San Bernardino. Our team will confirm which location and program requirements apply to you.
Arcasa Solar Zero | FHA Financing With Solar and Assistance
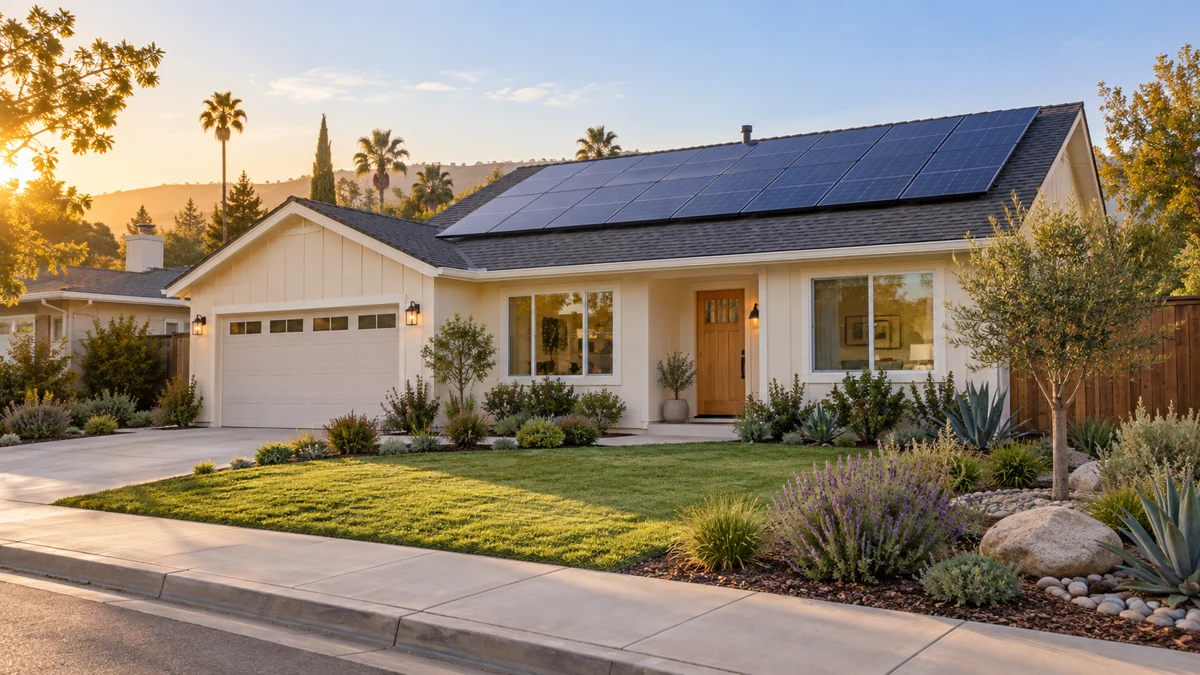
Interested in a home with solar? Arcasa Solar Zero connects an eligible FHA mortgage with a solar project and assistance for your purchase. The assistance can help with the down payment, closing costs, or an eligible permanent rate buydown.
- Assistance options from 3.5% to 5.5%. Our program information describes assistance based on the loan amount. We'll confirm the exact dollars and required project cost for your home.
- A grant or forgivable second loan. The structure depends on your approval. If a second loan is used, we'll explain its written forgiveness conditions and timing, including completion of the required solar work.
- No program income cap. You still need to qualify for the FHA mortgage and meet the property and solar requirements.
- Solar is installed after closing. The property and project are reviewed before closing. Existing solar may qualify for approved additions or improvements, reviewed case by case.
The cost of solar and eligible improvements is added to your first mortgage. To receive the selected assistance, you must complete the required project spending; more assistance means a larger required project budget. We'll compare the added loan balance, mortgage payment, project cost, and assistance together. The assistance does not make the solar system free.
How we help: Amy and our team review your FHA financing, then coordinate with Arcasa on the property assessment, project design, and documents. We'll explain the installation plan, assistance terms, and closing timeline before you commit. Assistance does not automatically cover every upfront expense.
Learn how FHA financing works →
California Assistance Options We Can Compare
Start With Our CalHFA Guide
 Understand the state programsGet to know CalHFALearn how CalHFA mortgages and assistance programs fit together, what to prepare, and which requirements to discuss with Amy.Read the CalHFA guide →
CalHFA MyHome
Eligible California first-time buyers may pair MyHome with a qualifying CalHFA first mortgage. It is a deferred-payment second loan for down payment or closing costs; repayment is postponed, not waived. Explore CalHFA MyHome.
Featured Story: Three Offers, One First Home
An inspiring story of patience, persistence, and finding the right home. When inspections uncovered serious concerns with their first two homes, Tyler and Elizabeth chose to keep looking. Their third offer led to their first home with CalHFA assistance and Amy's guidance along the way.
 An inspiring first-home journeyThree offers. One place to call home.See how Tyler and Elizabeth navigated setbacks and bought their first home with CalHFA assistance.Read their story →
GSFA Platinum
GSFA Platinum offers assistance with eligible first mortgages, including FHA and conventional loans. First-time and repeat buyers may qualify. We'll review the assistance amount, repayment terms, and current requirements for the option available to you. Explore the official GSFA Platinum guide.
Dream For All
Dream For All is a separate CalHFA program paired with its conventional first mortgage. It has first-time and first-generation buyer requirements, and assistance is repaid with a share of the home's appreciation. Funding and application windows affect availability. Learn about Dream For All.
For a closer look at the trade-offs, read Dream For All vs. CalHFA down payment assistance. If Dream For All is not available to you, explore a Plan B for Roseville and Sacramento homebuyers.
 Look beyond the down paymentIs Dream For All worth it for you?Explore shared appreciation, your timeline, and the long-term trade-offs for buyers around Roseville and Sacramento.Explore the trade-offs →
Let's Find the Option That Fits Your Family
From our Roseville office, Amy and our team help buyers across Greater Sacramento and Placer County compare their options. Bring your questions, your approximate purchase range, and a sense of the monthly payment and upfront amount you feel comfortable with.
- We listen first. Tell us where you want to buy, your timeline, and whether you've owned a home before.
- We review your eligibility. We look at your income, credit, available funds, property, and the requirements for each program.
- We explain the full picture. You'll see the assistance, any repayment obligation, your estimated monthly payment, and what you still need to bring.
- We help you move forward. Our team guides the application, documents, education requirements, and coordination with your agent.
Questions You May Be Asking
Is all assistance a grant?
No. A grant, a repayable second mortgage, and a forgivable second mortgage have different terms. We'll explain whether repayment is required, when it could be due, and what must happen for forgiveness.
Can AccessOne be added to my FHA loan?
No. The AccessOne program described here uses conventional HomeReady financing. AccessZero and Arcasa Solar Zero are FHA-compatible options. We'll compare them as separate financing choices.
Will solar assistance increase my mortgage?
The financed solar project and eligible improvements are added to the first mortgage. We'll show you that cost alongside the assistance and payment, so you can decide whether the whole arrangement makes sense for you.
Can I combine several assistance programs?
Only when the first mortgage and every assistance program allow the combination. We'll confirm compatibility before including multiple sources in your homebuying plan.
Does assistance mean I won't need any savings?
Not necessarily. You may still need money for part of the down payment, closing costs, inspections, an appraisal, reserves, and moving. We'll help you plan for the costs that assistance doesn't cover.
Program availability and terms can change. Your loan, property, and assistance must meet current requirements. Amy and our team will confirm the details for your application.