
Pay it off sooner
Want to Pay Your Mortgage Off Faster?
There is more than one way to shorten the road to a mortgage-free home. Refinancing into a shorter loan term may be one option, but sometimes simply paying additional principal toward your existing mortgage can accomplish the same goal without refinancing.
How it works if you want to pay the house off faster
A 30-year loan, a 20-year loan, and a 15-year loan are different monthly commitments. Shorter terms generally have higher required payments. They also tend to build equity faster and can reduce the interest paid over the life of the loan, when you actually keep the loan and make the payment.
That last part matters. A 15-year refinance that you later stretch back out, or a refinance whose closing costs eat the first year of interest savings, can look worse than the loan you already have. I will put the cost of refinancing next to the interest you hope to save.
You can also keep a loan you like and add extra principal each month. That path has no refinance closing cost. It only works if you will actually send the extra money, and if the servicer applies it to principal the way you intend. I will show you how to ask for that on the statement you already have.
If the real goal is a lower monthly payment, not a faster payoff, go to could refinancing lower your monthly payment. Those two goals often fight each other.
Some homeowners split the difference: they keep the 30-year loan for flexibility and send extra principal only in months the business or bonus can carry it. That is less rigid than a 15-year required payment, and it is less tidy than a refinance that forces the calendar. I will ask which kind of discipline you actually have, not which one sounds virtuous.
Biweekly payments, recasts, and extra principal are not the same tool. A biweekly plan only helps if the servicer applies the extra half-payment to principal instead of holding it. Ask before you set it up.
A recast after a large principal payment can drop the required payment on the loan you already have. That is the opposite of a 15-year refinance, which raises the required payment. If you want a lower required payment and a faster payoff at the same time, those two tools do not both win. I will pick the one that matches the month you can actually live with.
Pros and cons of a shorter term
A shorter term raises the required payment. That can crowd out savings, repairs, or the next house. A longer term lowers the required payment and usually costs more interest if you keep the loan to the end.
Keeping a great existing mortgage can be smarter than refinancing into a shorter term, especially if your current rate is one you would not want to give up. Extra principal on that loan can still move the payoff date.
This is not a promise that extra payments or a 15-year loan is right for you. It is the comparison I want on the table before anyone replaces the first mortgage. The full menu of refinance reasons is on refinance options.
An educational payoff comparison
Not a quote. Not your balance. Three pictures of the same goal.
| Path | What changes | What to watch |
|---|---|---|
| Keep the 30-year loan you have | Nothing required. Payoff date stays on the original calendar unless you add extra principal. | Lowest required payment. Slowest scheduled payoff. |
| Refinance into a 15-year loan | Required payment usually rises. Scheduled payoff shortens. Closing costs apply. | Only worth it if you can carry the new payment and will keep the loan long enough to matter. |
| Keep the existing mortgage and add $500 a month toward principal | Payoff date and total interest can improve without a new loan. | Works only if the extra $500 is real, consistent, and applied to principal. |
Educational illustration. I will run your remaining balance, term, and actual extra-payment habit. No rate or APR on this page.
The mortgage calculator can show how additional principal changes a payoff date, total interest, and years saved in a sketch. Treat that as a chalkboard, then send the statement.
Which payoff strategy fits your goals?
I can compare refinancing with simply accelerating your existing mortgage. She needs the current statement, whether you can comfortably raise the required payment, and whether you would rather keep flexibility.
If retirement timing is the real chapter, also read retirement equity. If the payment itself is the problem, do not force a shorter term.
Who a faster payoff fits
Bring the statement, the remaining term, and an honest extra-principal number you could send for a year, not a month. If the extra $500 only exists in January, do not refinance into a payment that assumes it forever.
If the house is going on the market, do not pay to shorten a loan you are about to pay off at sale. If retirement is twelve months away and the required 15-year payment would stress the new income, keep flexibility.
Texas homestead cash-out and California purchase-money rules are different conversations. Paying the loan you have off sooner is not the same as taking cash out. Cash belongs on the refinance hub.
If you are self-employed, extra principal in a strong quarter and a higher required payment in a thin quarter are not the same risk. I will look at the business cash, not only the house, before she cheers for a 15-year loan. Start on self-employed loans if income documentation is the hard part. A 20-year refinance sits between 15 and 30 for households that want a shorter calendar without the 15-year payment.
FAQ: faster payoff
Is a 15-year refinance always the fastest way to pay off a house?
No. Extra principal on a loan you already like can beat a refinance that costs money to close, especially if you might move before the new loan's savings show up.
Why do shorter terms have higher payments?
You are spreading the remaining balance over fewer required months. The payment has to be larger to finish on that calendar. That is the trade for faster equity and, often, less total interest if you keep the loan.
Can I recast instead of refinance?
Sometimes a servicer will recast after a large principal payment. That is a servicer conversation, not a new loan. I will tell you when a recast, extra payments, or a refinance is the cleaner tool.
What should I bring to compare options?
The current statement, a honest number for extra principal you could send every month, and how long you plan to keep the house. Book time or start on Amy's loanDepot apply page when you want a written loan estimate.
Complimentary guide · 4-page PDF
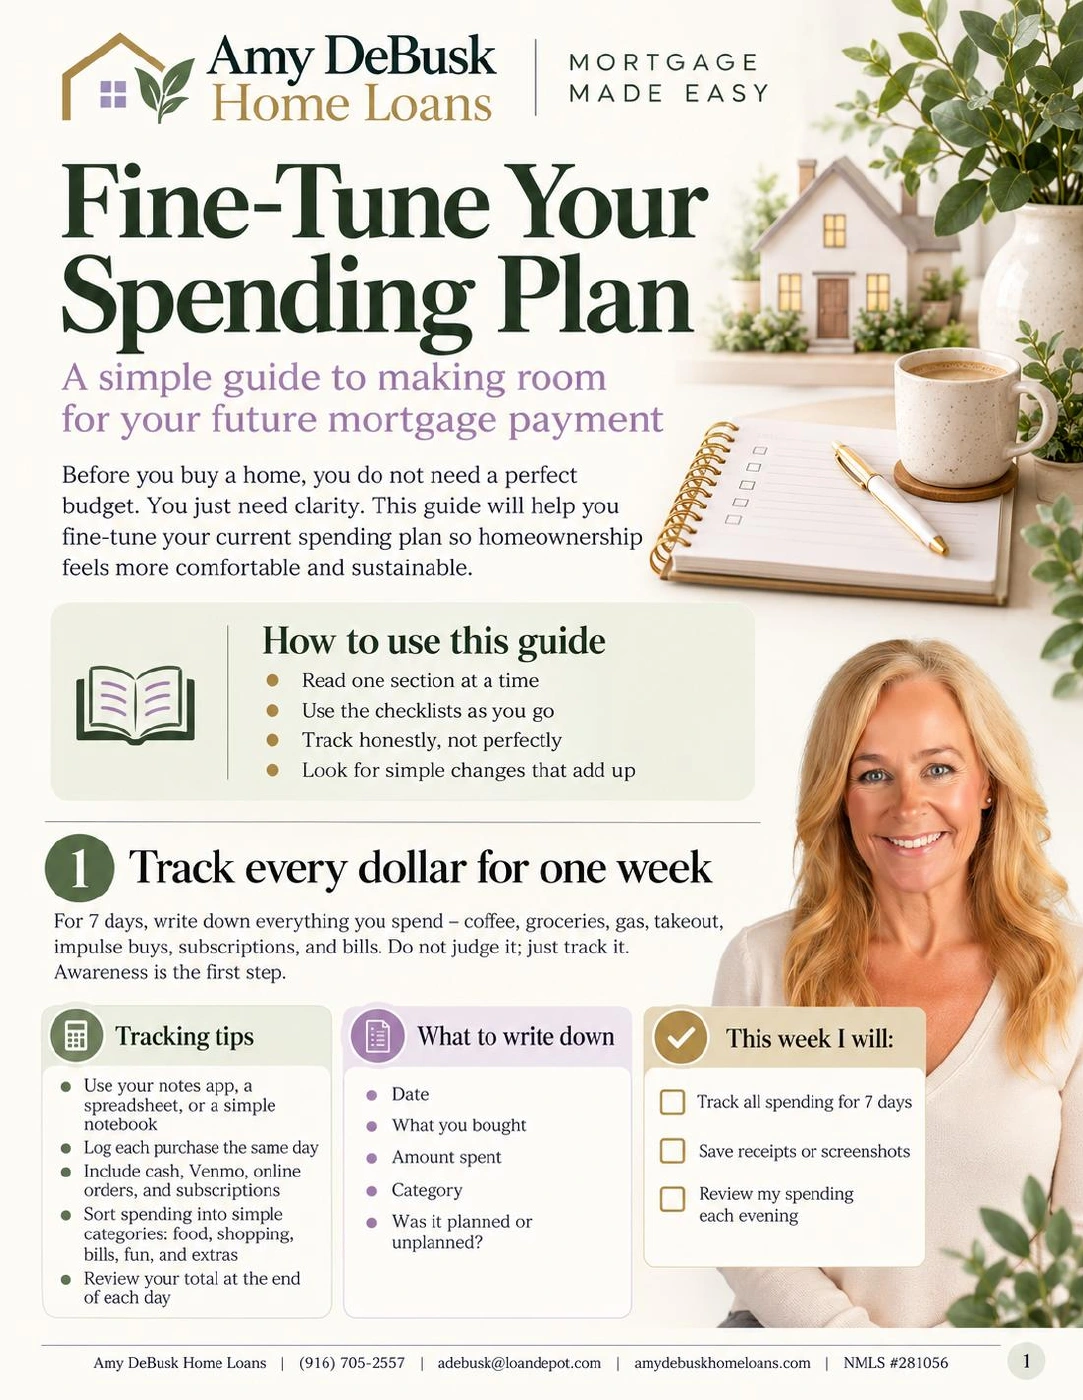
Fine-Tune Your Spending Plan
When you are taking a fresh look at your mortgage, it is a wonderful time to look at your everyday spending, too. I want to help you create more breathing room for your family, your goals and the moments that make home special.
My guide gives you simple action items to spot spending patterns, revisit recurring costs and choose changes that feel manageable. You can use it whether you decide to refinance or keep the mortgage you have.
- Track one week of spending and review the last 90 days for patterns.
- Decide which subscriptions and services to keep, pause or cancel.
- Try practical ways to slow down impulse purchases.
- Review household bills and write down your next steps.
Start with one small change. The goal is a spending plan that supports the life you want to live.
Download My Complimentary GuidePreview the PDF · Explore the interactive spending-plan tool
Ready for the next chapter?
You may be ready to begin or simply wondering what is possible. Tell me what home means to you, and we can find a useful next step together.