
Lower the payment
Could Refinancing Lower Your Monthly Mortgage Payment?
A refinance can sometimes create more room in your monthly spending plan, but a lower payment can come from several different strategies. The important question is not simply whether a new loan has a lower payment. It is whether the new loan makes sense for your overall financial picture.
How it works when a refinance lowers a payment
Start with what you want to accomplish. If the goal is more room in the monthly spending plan, I will look at more than one path. A lower interest rate is only one of them. You can also change the remaining term, remove mortgage insurance when you are eligible, move from one loan program to another, move from an adjustable-rate mortgage to a different structure, or use lender credits to reduce what you pay upfront.
Those choices do not all feel the same in year five. Stretching a loan back out to 30 years can drop the payment and raise the total interest. Removing mortgage insurance can drop the payment without changing the rate at all. Keeping a strong first mortgage and leaving it alone can also be the right answer. That is why this page is not a generic conventional loans pitch.
If you already know you want cash out, or you are choosing among a refinance, a home equity loan, and a HELOC, start on the refinance hub and then come back here for the payment question.
In Roseville and Greater Sacramento, taxes, insurance, and HOA dues can move even when principal and interest drop. I will not treat a lower P&I line as a lower housing payment until those other pieces are on the same page. A Folsom or Granite Bay insurance renewal can erase a refinance that looked good on principal and interest alone.
Property taxes in Placer County and Sacramento County are not the same bill, even when two houses look similar from the street. Bring the current tax and insurance amounts on the statement so a cheaper principal and interest line is not mistaken for a cheaper housing payment.
A lower payment is only part of the equation
A cheaper month is not automatically a better loan. Before anyone celebrates a lower principal and interest number, look at closing costs, the break-even period, how many years are left on the loan you have, the new loan term, total interest over time, and how long you expect to keep the house.
If you plan to sell in two years, a refinance that takes 40 months to break even is usually the wrong tool. If you will stay, and the new loan also drops mortgage insurance, the math can look very different. I will put both pictures on the table.
Paying the home off faster is a different goal. That conversation lives on pay your mortgage off faster. Getting rid of mortgage insurance lives on remove mortgage insurance.
Closing costs and the break-even
Bring a current mortgage statement. I will compare the loan you have with a possible new loan. The Roseville mortgage calculator can sketch a payment and a break-even. It is an estimate. It is not a quote, a lock, or a loan estimate from loanDepot.
A simple break-even illustration
This is teaching math, not your loan. If a refinance cost $4,800 to close and the monthly principal and interest dropped $120, break-even would be about 40 months. Stay longer than that, and the lower payment has time to matter. Move or refinance again before that, and you may never recover the cost.
Your closing costs, your payment change, and your timeline decide the real number. I will not publish a rate or APR on this page to make the example look official.
| What we look at | Loan you have now | Possible new loan |
|---|---|---|
| Monthly principal and interest | From your statement | From a loan estimate, not this page |
| Mortgage insurance, if any | PMI or FHA MIP on the current loan | May stay, drop, or change with the new structure |
| Monthly difference | Current total housing payment versus the new one | |
| Annual difference | Monthly difference times 12, before taxes or insurance changes | |
| Estimated closing costs | None, if you keep the loan | Third-party costs, prepaid items, and any points or credits |
| Approximate break-even | Closing costs divided by the monthly savings, when there is savings | |
Illustration of the conversation. Not a rate, approval, or offer to lend. Qualification required.
Want to know if refinancing could actually save you money?
Send Amy your current mortgage statement and she can help you compare the numbers. She will also ask whether a move from an adjustable rate to a fixed rate is the real reason the payment feels unstable.
What she needs: the statement, a sense of how long you will keep the house, and whether the goal is only a lower payment or also cash, a remodel, or a shorter term.
Who qualifies, and who should keep the loan they have
If you are trying to pull cash for a remodel, a second property, or a debt reset, a rate-and-term refinance that only drops the payment may leave the real job undone. Use the refinance hub and name the cash purpose first.
If you are already missing payments, this page is not a hardship program. Call the servicer and Amy the same week. A refinance still needs qualification. It is not a stall button.
If you bought last year and the loan has almost no equity, closing costs can wipe the savings. Waiting, making extra principal, or leaving the loan alone can be the grown-up answer. I will say that out loud.
A loan estimate from loanDepot is the document that makes this real. Until that paper exists, every number on a website is a sketch. Book time, send the statement, and she will tell you whether to apply or keep the loan you have. Mobile (916) 705-2557.
FAQ: lower-payment refinance
Is a lower payment always worth refinancing?
No. If closing costs take years to recover, or if the new term adds interest you did not mean to pay, keeping the loan you have can be smarter. I will say so.
Can lender credits lower what I pay to refinance?
Sometimes. A credit can reduce upfront cost and may come with a different rate than a no-credit loan. That trade-off belongs on a loan estimate, not in a website promise.
What if my payment is high because of mortgage insurance?
Then the first question is whether you can remove it on the loan you already have. Read remove mortgage insurance before you replace a first mortgage you like.
Where do I sketch the math before I call?
Use the mortgage calculator or the equity planner as a sketch. Then send the statement so I can use your real numbers.
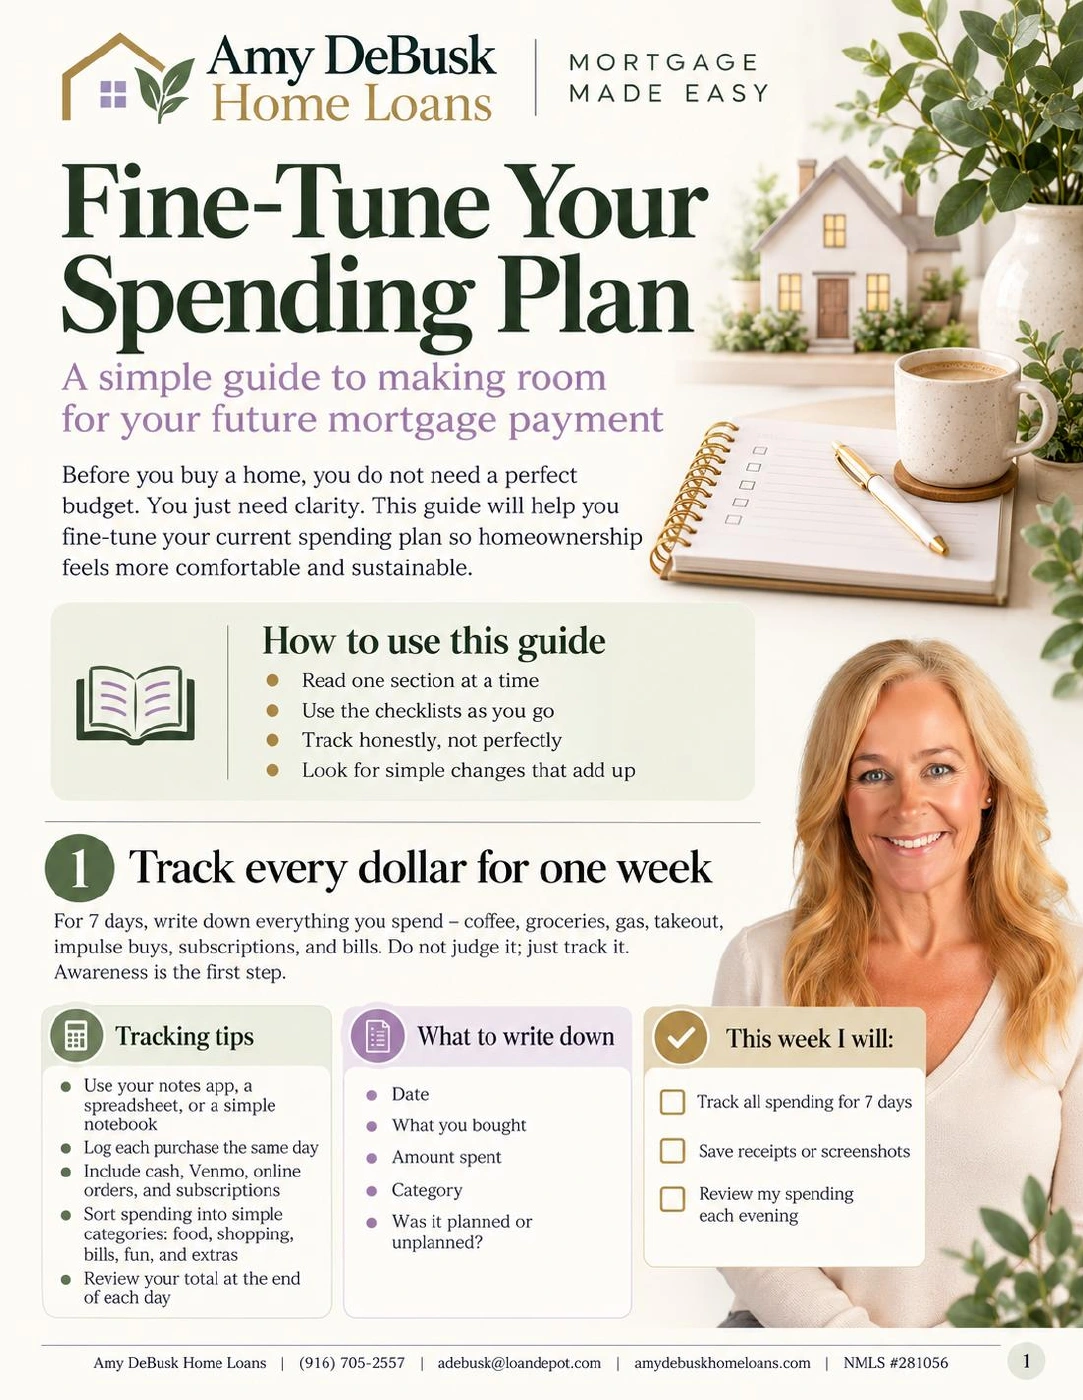
Complimentary guide · 4-page PDF
Fine-Tune Your Spending Plan
When you are taking a fresh look at your mortgage, it is a wonderful time to look at your everyday spending, too. I want to help you create more breathing room for your family, your goals and the moments that make home special.
My guide gives you simple action items to spot spending patterns, revisit recurring costs and choose changes that feel manageable. You can use it whether you decide to refinance or keep the mortgage you have.
- Track one week of spending and review the last 90 days for patterns.
- Decide which subscriptions and services to keep, pause or cancel.
- Try practical ways to slow down impulse purchases.
- Review household bills and write down your next steps.
Start with one small change. The goal is a spending plan that supports the life you want to live.
Download My Complimentary GuidePreview the PDF · Explore the interactive spending-plan tool
Ready for the next chapter?
You may be ready to begin or simply wondering what is possible. Tell me what home means to you, and we can find a useful next step together.