
Mortgage insurance
Can You Remove Mortgage Insurance From Your Payment?
Mortgage insurance can add hundreds of dollars to a monthly housing payment. Whether it can be removed, and whether refinancing is necessary to remove it, depends on the type of mortgage you currently have.
How it works: conventional PMI and FHA MIP
People mix them because both show up as a monthly line. They do not cancel the same way. If you are still choosing a purchase program, start with FHA versus conventional. If you already have the loan, stay here. This is not a promise that refinancing is required.
Conventional PMI
A homeowner may not have to refinance at all. Depending on the loan and your current equity position, you may be able to request cancellation through your current mortgage servicer.
That conversation usually looks at original value, current balance, current estimated value, payment history, the servicer's written requirements, and whether an appraisal or another valuation is required. I will not promise a cancellation date. The servicer owns that decision on the loan you already have.
FHA mortgage insurance
FHA MIP rules are different. Whether MIP remains for a certain period or for the life of the loan depends on the mortgage's origination date, term, and original loan-to-value.
Some homeowners later explore refinancing from FHA into conventional financing once they have sufficient equity and qualifications. That can remove FHA MIP when the new loan does not need it. It is not always required, and it is not always beneficial. Closing costs, the new rate, and how long you will keep the house still have to win.
Read FHA loans if you are still deciding a purchase. This page is for a loan you already have.
Lender-paid mortgage insurance is a third shape. If you never see a monthly PMI line, the insurance cost may already be inside the rate. Canceling that is not a servicer letter. It is a refinance conversation, and only if the new loan is cheaper after you count the rate you would give up.
A VA funding fee and a USDA annual fee are not PMI. If the loan is VA or USDA, do not treat this as a cancellation letter. Start with me on the program you actually have, then decide whether a refinance is even the tool.
Who can cancel PMI, and who still refinances
Current loan balance. Home value. Current rate on the loan you have, from your statement, not from this website. Existing mortgage insurance. Current total payment. A potential new payment on a loan estimate. Closing costs. Break-even period.
If the only reason to refinance is to drop insurance, and the servicer can cancel PMI on the current loan, replacing the first mortgage may be the expensive way. If MIP cannot come off the FHA loan you have, a conventional refinance may be the tool, when you qualify.
A lower payment from insurance coming off is still a payment conversation. Pair this page with could refinancing lower your monthly payment when both are true.
Costs of canceling versus refinancing
The useful sketch is simple: today's total principal, interest, and mortgage insurance versus a possible payment that no longer includes that insurance line. Then subtract the cost of getting there.
| Question | Keep the current loan | Refinance |
|---|---|---|
| Can insurance come off? | Sometimes, through the servicer, on conventional PMI | Sometimes, if the new loan does not require it |
| FHA MIP | Follows FHA rules for that origination, term, and original loan-to-value | May end if you leave FHA and the new loan qualifies without MIP |
| Cost to try | Often a letter, and sometimes an appraisal the servicer requires | Closing costs and a new loan |
| When it is the wrong move | You request cancellation too early and pay for a value the servicer will not use | You replace a strong first mortgage only to drop a small insurance line |
Education, not a cancellation promise. Qualification required. No rate or APR on this page.
The equity planner and the calculator can hold example numbers. I will replace them with your statement and a current value conversation. A Homebot home value report is an automated estimate, not the appraisal a servicer or a new loan may require.
Let's find out whether you still need mortgage insurance
Send the statement and tell me whether the loan is conventional or FHA. If you have an old appraisal or a Homebot snapshot, bring that too. I will explain when to write the servicer, when to refinance, and when to leave the loan alone.
More refinance reasons live on refinance options.
What to bring, and what we will not promise
Bring the statement that shows the insurance line, or the FHA case number if you have it. If you have a recent appraisal, bring that. If you only have a Homebot snapshot, say so. I will not treat an automated value as the servicer's number.
I cannot cancel PMI for you. Only the current servicer can do that on the loan you have. She will not promise that a conventional refinance drops insurance. Equity, occupancy, and credit still have to work.
If the insurance line is actually a flood policy or an HOA master policy, that is not PMI or MIP. Do not refinance to drop insurance when the line is property insurance. I will separate those on the first call.
Roseville and Sacramento values move. A cancellation request that was early last year can be timely now, or the reverse. That is why I want a current statement and a current value conversation, not a screenshot from the year you closed. If you are also comparing a HELOC, keep the first mortgage conversation on this page and the second-lien conversation on the HELOAN versus HELOC guide.
FAQ: mortgage insurance
Do I have to refinance to drop conventional PMI?
Often no. Many conventional loans allow a cancellation request once equity and the servicer's rules line up. I will not treat refinance as the first move when a letter to the servicer might be enough.
Can I cancel FHA MIP the same way?
Usually not. FHA MIP follows its own rules. Some loans keep MIP for the life of the loan. Others have a time-based path. Origination date, term, and original loan-to-value decide that, not a website chart.
If I refinance from FHA to conventional, is MIP gone?
The FHA MIP ends when that FHA loan is paid off. The new loan may have PMI, or it may not, depending on equity and the product. That is the comparison, not a guarantee of a cheaper month.
What does Amy need to review my insurance?
The current statement, whether the loan is FHA or conventional, and a sense of value. Then book time or apply when you want a written loan estimate.
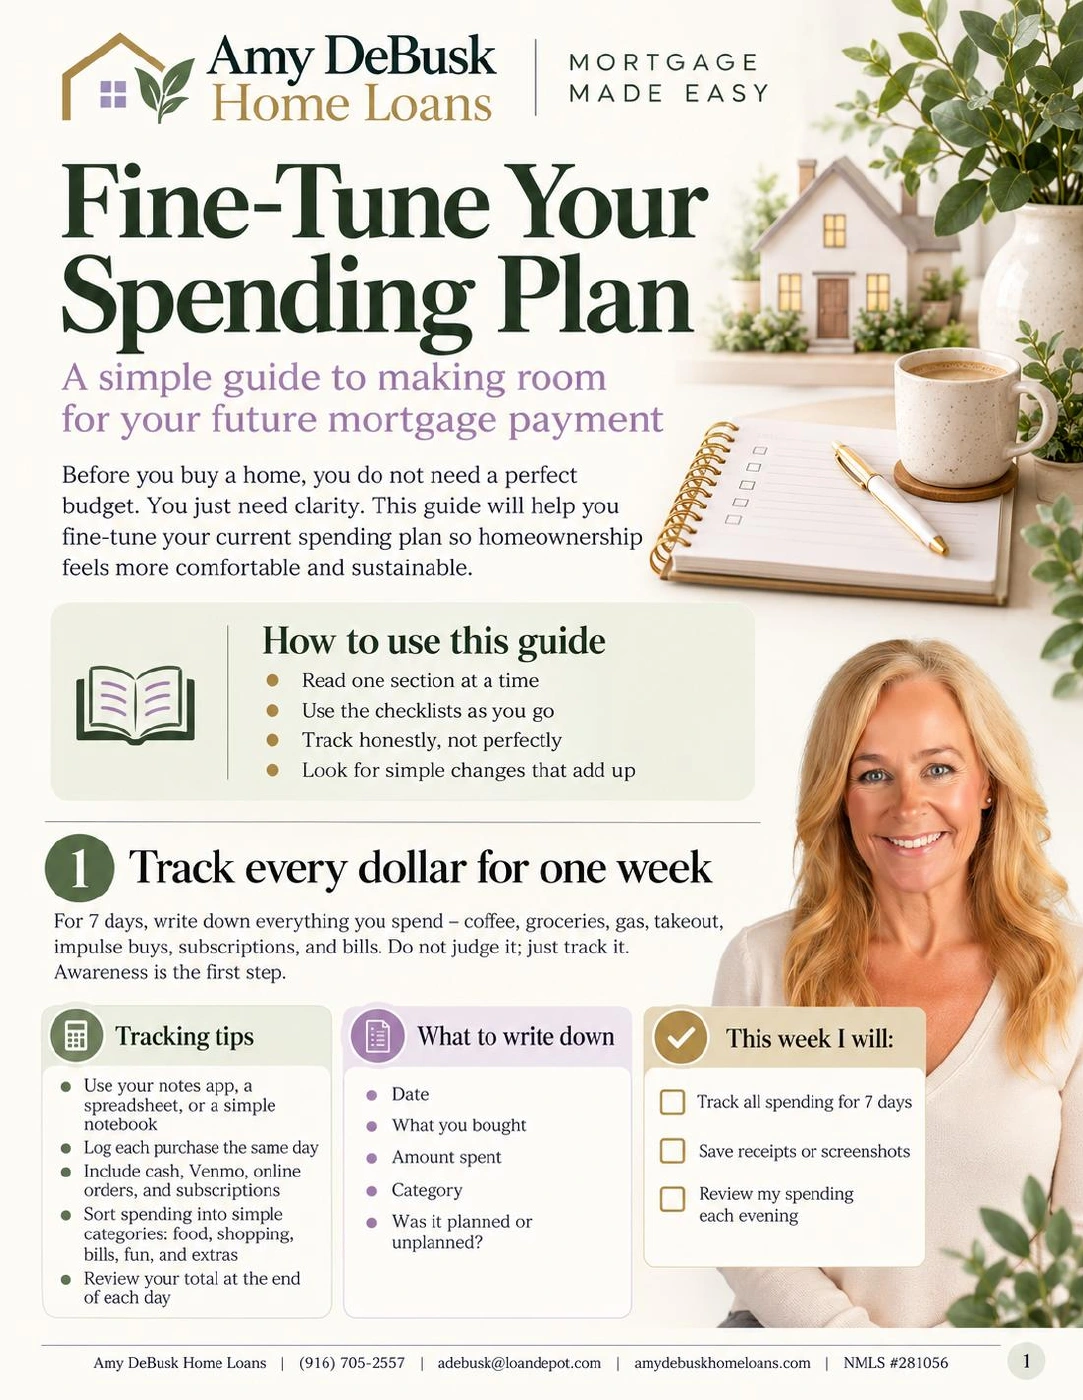
Complimentary guide · 4-page PDF
Fine-Tune Your Spending Plan
When you are taking a fresh look at your mortgage, it is a wonderful time to look at your everyday spending, too. I want to help you create more breathing room for your family, your goals and the moments that make home special.
My guide gives you simple action items to spot spending patterns, revisit recurring costs and choose changes that feel manageable. You can use it whether you decide to refinance or keep the mortgage you have.
- Track one week of spending and review the last 90 days for patterns.
- Decide which subscriptions and services to keep, pause or cancel.
- Try practical ways to slow down impulse purchases.
- Review household bills and write down your next steps.
Start with one small change. The goal is a spending plan that supports the life you want to live.
Download My Complimentary GuidePreview the PDF · Explore the interactive spending-plan tool
Ready for the next chapter?
You may be ready to begin or simply wondering what is possible. Tell me what home means to you, and we can find a useful next step together.