
Adjustable to fixed
Is It Time to Move From an Adjustable Rate to a Fixed Rate?
If you have an adjustable-rate mortgage, your decision should not be based on fear of an adjustment. Start by understanding exactly how your current ARM works, when it adjusts, and what your alternatives look like.
How it works on the ARM you already have
An ARM is a living contract, not a generic conventional loan. Before anyone talks you into a fixed-rate refinance, we need the facts on the loan you have.
Find these on your note, your closing disclosure, or the current statement, then send them to me:
- Current ARM rate
- Initial fixed period
- Next adjustment date
- Index
- Margin
- Adjustment caps
- Lifetime cap
- Current loan balance
If you cannot find the index, margin, or caps, that is normal. Those details are often in the original closing package, not on the monthly coupon. I can help you locate them. Do not guess from a social-media chart.
Interest-only ARMs need their own read. If you are only paying interest right now, the payment can jump when principal starts, even if the rate does not move that month. That is not the same problem as a fully amortizing ARM hitting its first adjustment. Tell me which one you have. The note will say.
A 5/6 ARM, a 7/6 ARM, and a 10/6 ARM are named for the first fixed years and how often the rate can adjust after that. Your loan may use a different schedule. The label on a blog post is not your note. Bring the document.
If you bought in a year when adjustable rates were used to stretch buying power in Roseville or Rocklin, the first adjustment date may still be years out. Refinancing now to "get safe" can spend closing costs to buy a fixed payment you do not need yet. Waiting until the last year of the fixed period, then comparing, is often the calmer sequence. I will put the date on a calendar with you.
VA and FHA adjustable loans, when someone actually has one, have their own refinance paths. Do not assume a conventional fixed refinance is the only door. If the current loan is VA, start by asking whether an IRRRL or a cash-out VA refinance is even in play. That is a different page: VA IRRRL.
Who should consider a fixed-rate refinance
A fixed-rate loan can make the principal and interest payment more predictable. That can help long-term household budgeting and can protect you from future rate increases after the ARM's next adjustment.
Those are real reasons. They are not the same as "adjustable rates are always dangerous." Fear is a poor underwriter.
Why you might keep your ARM
Your current ARM may still have several fixed years remaining. The current ARM rate may be better than available fixed rates. You may plan to sell before the next adjustment. Refinancing costs may outweigh the benefit.
If the payment itself is the problem, also read could refinancing lower your monthly payment. If you want the house paid off sooner, read pay your mortgage off faster.
Costs of moving from an ARM to a fixed rate
Look at the note and the first adjustment letter from the servicer. The index is the published number the loan follows. The margin is the amount added to that index. Caps limit how far the rate can move at the first adjustment, at later adjustments, and over the life of the loan.
Invite Amy to review the statement or the closing documents. Do not screenshot a friend's ARM and assume yours matches. Two 5/6 ARMs from different years can behave differently.
A new fixed-rate loan might be conventional, or it might be a different program if you qualify. The product name comes after the ARM math, not before. The broader refinance menu is on refinance options.
What we compare
Current rate and payment. Next adjustment date. Worst-case payment inside the caps. Available fixed-rate payment on a loan estimate. Closing costs. How long you expect to keep the house. Whether you would rather keep the ARM through the next fixed years.
This site will not publish an ARM or fixed rate. The calculator can hold numbers you type. I will replace those with your statement.
Not sure what your ARM will do next?
I can help you understand your existing mortgage and compare it with available fixed-rate options. Send the statement, the note if you have it, and how long you plan to stay.
What to send Amy this week
A clear photo of the current statement. The note or ARM rider if you still have the closing packet. The last adjustment letter, if one has already arrived. How long you plan to keep the house. Whether anyone else is on the loan who will not be on the next one.
If a divorce or a co-signer removal is the real reason the ARM feels unstable, say that first. The rate type is then a second question. Those situations start on the refinance hub under life changes, not on this page alone.
If you are still inside a prepayment-penalty period, rare on many modern loans but not impossible on older or non-QM notes, the cost of leaving early can erase the comfort of a fixed payment. I will look for that before anyone spends appraisal money.
After you have the dates, the next step is a written comparison, not a guess. Book time, send the note, and ask for a loan estimate only if the calendar and the costs still justify replacing the ARM. Call (916) 705-2557 if you would rather talk through the dates first.
FAQ: ARM to fixed
Should I refinance before the first adjustment out of fear?
Not automatically. If several fixed years remain, or if the caps and your timeline make the next adjustment livable, keeping the ARM can be the calmer choice. I will show the dates before anyone spends closing costs.
Where do I find the index and margin?
Usually on the note or an ARM rider in the closing package, and sometimes on an annual adjustment notice. If you cannot find them, send Amy the statement and what you still have from closing.
Is a fixed-rate refinance always conventional?
No. Conventional is common. VA, FHA, or another structure can apply if you qualify. The ARM you have now decides part of the story. The new product is a later sentence.
What if I also want cash out?
Then we are comparing a rate-and-term refinance with a cash-out refinance or a second lien. Start on the refinance hub so the cash goal does not hide inside an ARM conversation.
Complimentary guide · 4-page PDF
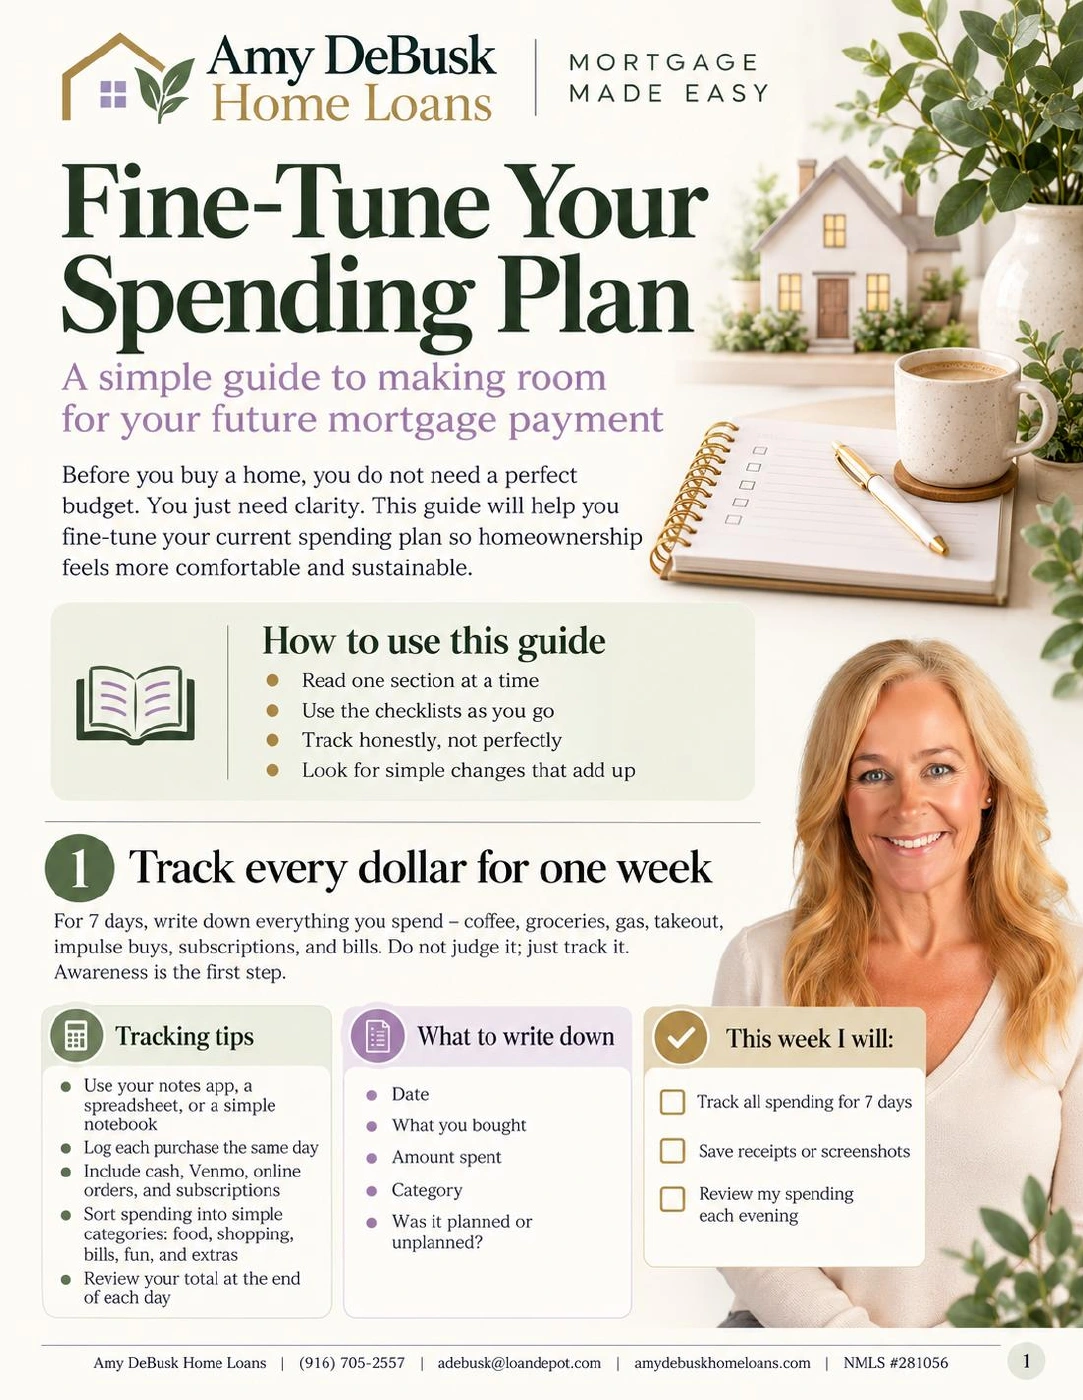
Fine-Tune Your Spending Plan
When you are taking a fresh look at your mortgage, it is a wonderful time to look at your everyday spending, too. I want to help you create more breathing room for your family, your goals and the moments that make home special.
My guide gives you simple action items to spot spending patterns, revisit recurring costs and choose changes that feel manageable. You can use it whether you decide to refinance or keep the mortgage you have.
- Track one week of spending and review the last 90 days for patterns.
- Decide which subscriptions and services to keep, pause or cancel.
- Try practical ways to slow down impulse purchases.
- Review household bills and write down your next steps.
Start with one small change. The goal is a spending plan that supports the life you want to live.
Download My Complimentary GuidePreview the PDF · Explore the interactive spending-plan tool
Ready for the next chapter?
You may be ready to begin or simply wondering what is possible. Tell me what home means to you, and we can find a useful next step together.