“Amy, I want to buy a home. But the mortgage is going to cost more than my rent. How am I supposed to make that work?”
I hear this question from first-time buyers throughout Roseville and the Sacramento area. They can picture the backyard, the family dinners, or the freedom to make a home their own. Then we look at the monthly payment.
For some buyers I work with, the proposed housing payment is $1,000 to $1,200 more than their current rent. That is a meaningful difference. It deserves a thoughtful plan.
But the payment difference is only the beginning of the comparison. We also need to understand potential income-tax savings, the part of a mortgage payment that reduces your loan balance, and what owning a home could mean for your financial position over time.
Let’s look at what you would pay each month, what you might save in taxes, and what could change over five years.
Is buying worth a higher monthly payment?
It can be, if the full housing cost fits your spending plan and you expect to stay long enough for the benefits to outweigh the costs. Potential tax savings, mortgage paydown, and appreciation belong in the comparison. So do maintenance, closing costs, selling costs, and what you could save and invest while renting.
In the Roseville example below, the estimated housing cost is $3,845 per month, plus a $250 maintenance reserve. The four households have different potential tax savings. Those savings do not reduce the mortgage bill, and appreciation is not guaranteed.
Why a mortgage payment can be higher than rent
The home you are considering may be different from the one you rent. You may be buying more space, a different location, or a property that better fits the next chapter of your life. Interest rates, your down payment, taxes, and insurance also shape the payment.
Start by comparing the full cost of living in each home. For the purchase, include principal and interest, property taxes, homeowners insurance, mortgage insurance when required, and any HOA dues. Then make room for utilities, maintenance, and repairs. If taxes and insurance are already included in the payment estimate, do not count them twice.
A fixed-rate mortgage keeps scheduled principal and interest predictable. Your total housing expense can still change as taxes, insurance, HOA dues, and upkeep change.
Our Mortgage Payment Calculator can help you explore the loan-payment side. Our How to Afford Your Home page helps you connect those numbers to everyday life.
You may need a different spending plan. Let’s be honest about that.
Yes, buying a home may mean being more intentional with your money. You might revisit subscriptions, plan restaurant spending, pause a purchase, or give extra earnings a clear purpose.
The goal is a plan you can sustain while continuing to save, handle surprises, and enjoy the things that matter to you. A home should support the life you are building.
I like to begin with a simple exercise: practice the new payment before you buy. If the estimated increase in your total housing expense is $1,100, try moving that amount into a separate savings account each month. Add the maintenance reserve your plan calls for. See how the adjustment feels over several months.
If it works comfortably, you have practiced the change and built more savings. If it feels too tight, we have useful information before you make a commitment. We can revisit the price range, your timing, or another part of the plan.
Watch & learn with Amy
Let’s talk through the decision together.
Watch Amy’s short video: Rent vs. Buy: Is Buying Your First Home Worth It? The video introduces the bigger picture; the dated Molino Circle calculations below are the article’s separate illustration.
How much could buying a home save you in income taxes?
Eligible mortgage interest and property taxes may reduce your income taxes when you itemize deductions. The expanded federal state and local tax deduction, often called SALT, may make that conversation especially relevant for some California households.
For tax year 2026, the general federal SALT cap is $40,400, or $20,200 for married taxpayers filing separately. Income-based reductions and other rules apply. A higher deduction limit creates room for eligible deductions; it does not mean everyone receives that amount in tax savings.
What matters is the difference between your estimated taxes as a renter and your estimated taxes as a homeowner. We need to account for the standard deduction or deductions you already claim, along with your filing status, qualifying interest, state and local taxes, and other relevant details. Last year’s tax return is a useful starting point, and your tax professional can confirm the current-year comparison.
For an individual household, the annual benefit could be substantial. It could also be much smaller than expected, or there may be no added federal benefit. That is why a personalized comparison is so useful.
A real Roseville listing · An illustrative buyer plan
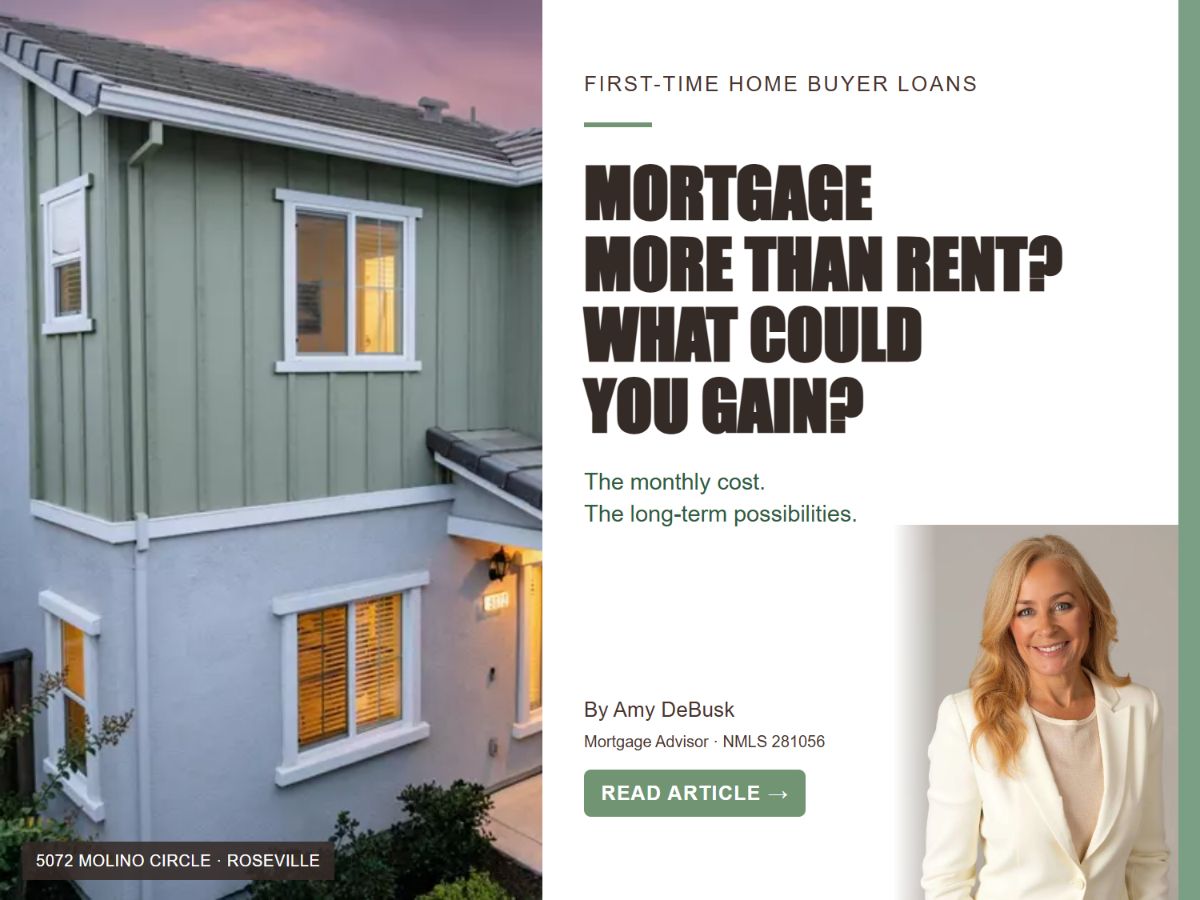
Let’s put the numbers around 5072 Molino Circle.
This Roseville home was listed at $439,900 when checked November 14, 2026: three bedrooms, two bathrooms, approximately 1,387 square feet, and a two-car garage. The listing reports HOA dues of $103 per month and a solar lease of $38 per month. View the property details and photos →
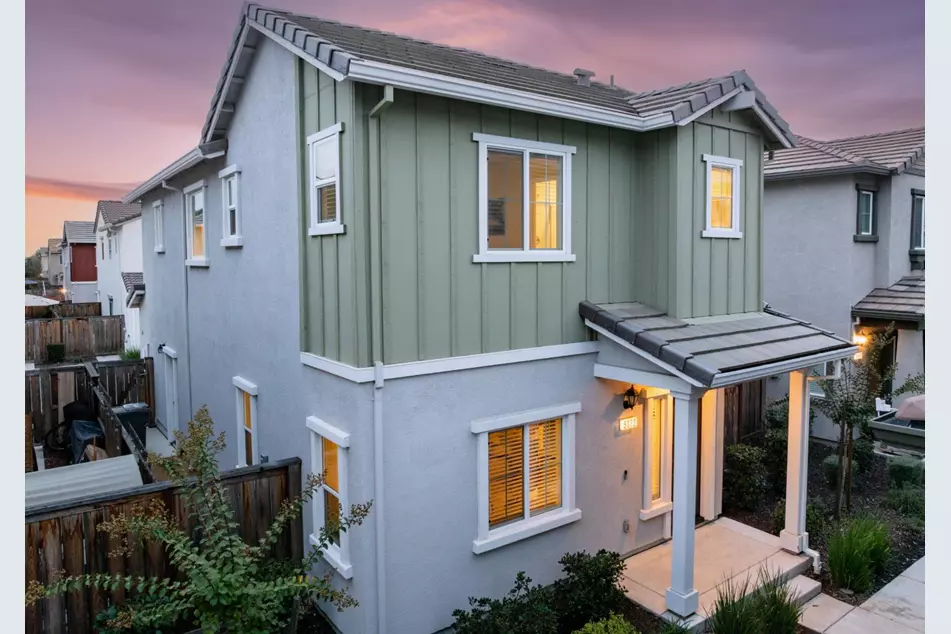
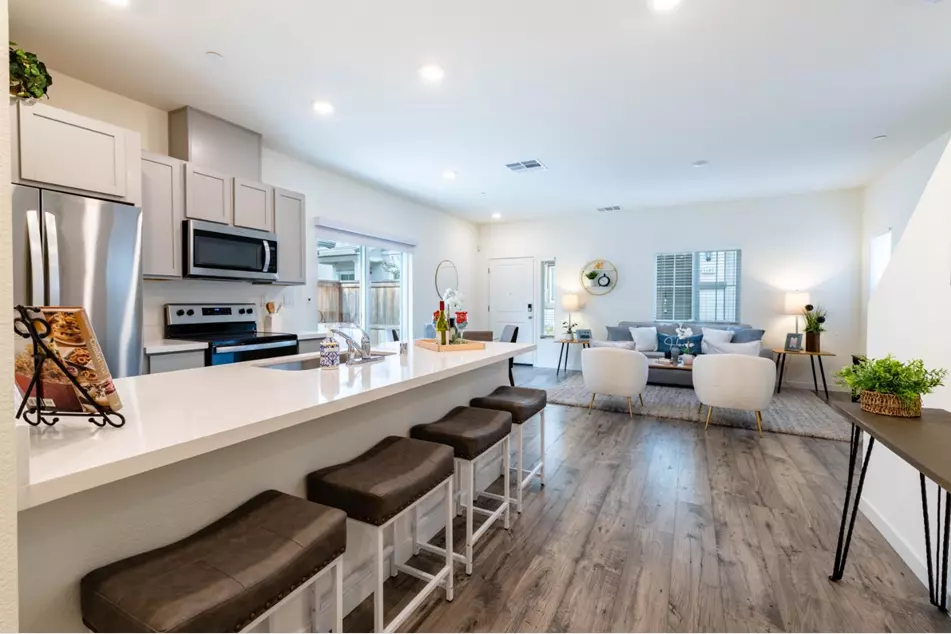
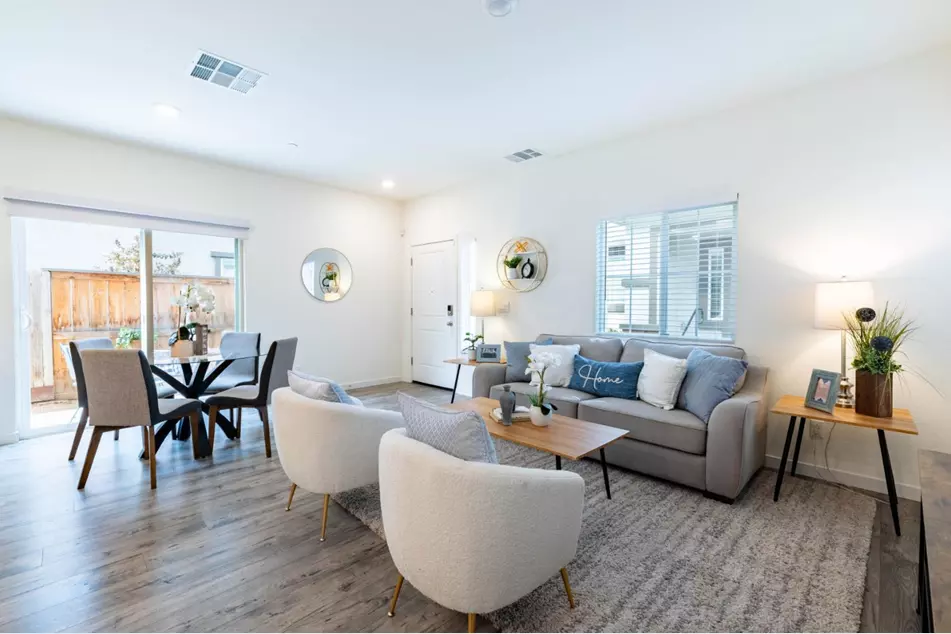
Listing photographs: MetroList MLS #226134908, listed by NextHome Navigate, displayed from the Coldwell Banker listing. Tap a photo for a larger view. Listing photographs are separate from the lifestyle illustrations elsewhere in this article.
For this example, we will use a CalHFA FHA first mortgage with MyHome down payment assistance. This illustration uses a 6.750% note rate for Friday, November 13, 2026, supplied by Amy DeBusk. Rates can change, and borrower and program requirements apply. This is a dated planning example, rather than a current rate quote or an approval for this home.
Property taxes, insurance, and HOA: here is the breakdown.
We checked Placer County’s 2026-2027 bill for parcel 492-540-010-000. The existing bill totals $7,498.52 on a $464,265 taxable value. For this purchase example, we recalculated the value-based taxes at $439,900 and kept the bill’s direct charges unchanged.
| Tax or assessment | Annual | Monthly equivalent |
|---|---|---|
| Base property tax, 1% × $439,900 | $4,399.00 | $366.58 |
| Voter-approved school and college bonds, combined 0.077045% | $338.80 | $28.23 |
| Placer Mosquito & Vector Control | $36.98 | $3.08 |
| Roseville Municipal Services CFD #3 | $595.64 | $49.64 |
| Fiddyment Ranch CFD #2 | $389.48 | $32.46 |
| Fiddyment Ranch CFD #5 | $1,476.24 | $123.02 |
| Total estimated property taxes and assessments | $7,236.14 | $603.01 |
The three CFD charges are Mello-Roos special taxes. These direct charges are not reduced in proportion to the purchase price and can change in future years. Bond levies follow the county bill’s half-year rounding method. Totals use unrounded monthly equivalents. This is a full-year estimate before any homeowners exemption; the assessor and taxing agencies determine the final bill. Supplemental assessments or refunds and escrow adjustments are separate.
See where the monthly housing dollars go.
- Principal & interest$2,802
- Property taxes & assessments$603
- Homeowners insurance$105
- FHA mortgage insurance$195
- HOA dues$103
- Solar lease$38
See the detailed monthly payment breakdown
What could the monthly housing expense look like?
| First-mortgage principal and interest | $2,801.50 |
|---|---|
| FHA mortgage insurance, approximate initial amount | $194.56 |
| Property taxes and assessments, recalculated estimate | $603.01 |
| Homeowners insurance, estimated | $105.00 |
| Reported HOA dues | $103.00 |
| Reported solar lease | $38.00 |
| Estimated monthly housing total | $3,845.08 |
| Additional maintenance savings allowance | $250.00 |
| Planning total including maintenance savings | $4,095.08 |
Totals use unrounded calculations. Utilities, repairs above the reserve, moving, and cash needed at closing are additional. Taxes, assessments, insurance, and solar-transfer terms require property-specific confirmation. Annual FHA mortgage insurance changes as the loan amortizes.
How MyHome could help with the down payment
Assuming the home appraises for at least the purchase price and the borrower qualifies, MyHome could provide $15,396.50 toward the required down payment. This is a separate, deferred-payment second loan. It is repayable assistance, rather than a grant. Closing costs, prepaid expenses, inspections, and other funds may still be needed.
At the published 1.000% simple-interest MyHome rate, there is no scheduled monthly MyHome payment in this example. Interest accrues: after five full years with no payments, the assistance balance would be approximately $16,166.33. Repayment is generally due upon sale, refinance, first-mortgage payoff, or another triggering event.
Same home. Different households. Different potential tax savings.
These examples compare estimated taxes while renting with estimated taxes while owning. They apply progressive 2026 federal and California tax schedules, rather than multiplying every deduction by one bracket. The income shown is adjusted gross income (AGI), which may be lower than your salary after certain retirement contributions or other adjustments.
Same home. A different tax picture for each household.
Estimated annual tax reduction divided by 12
See the annual federal and California tax figures
| Household | Federal per year | California per year | Combined monthly equivalent |
|---|---|---|---|
| Single$100,000 annual AGI | $4,852 | $2,434 | $607/mo$7,286 per year combined |
| Single$120,000 annual AGI | $5,259 | $2,544 | $650/mo$7,803 per year combined |
| Married filing jointly$125,000 annual AGI | $540 | $1,287 | $152/mo$1,828 per year combined |
| Married filing jointly$150,000 annual AGI | $1,398 | $1,671 | $256/mo$3,069 per year combined |
The housing total remains about $3,845 each month for every household shown. Tax savings do not reduce the mortgage bill. They may affect take-home pay after an appropriate withholding adjustment, or be realized when filing. A monthly equivalent is the annual estimate divided by 12, rather than a promised monthly payment or refund.
For example, the single buyer at $100,000 AGI shows a potential annualized benefit of about $607 per month. The married household at $125,000 AGI shows about $152. The difference is a useful reminder to build the tax picture around your own household.
See the payment assumptions, tax assumptions, and sources
- Mortgage: $424,503.50 base first mortgage, plus $7,428.81 in financed FHA upfront mortgage insurance (1.75%), for a total first loan of $431,932.31. Term: 360 monthly payments at the dated 6.750% note rate. Annual MIP is estimated at 0.55% of the base loan initially. APR, lender fees, and cash to close have not been calculated; obtain an official Loan Estimate.
- Property costs: Estimated property taxes and assessments are $7,236.14 per year at the example price, using the county bill’s rates and direct charges. Value-based taxes of $4,737.80 are included in the income-tax illustration; $2,498.34 in direct charges is excluded. No homeowners exemption is assumed. Homeowners insurance is estimated at $105 per month ($1,260 per year), subject to an insurance quote. HOA dues are $103 per month, separate from property taxes and insurance.
- Timing: Tax figures annualize the first 12 scheduled mortgage payments using 2026 law for comparison. They are not the deduction for a late-2026 purchase. Actual deductions depend on amounts paid in the calendar year; 2027 thresholds differ.
- Interest: Estimated first-12-payment interest is $29,015. A conservative $28,516 is included as acquisition-debt interest, excluding the portion attributable to financed upfront MIP. No deduction for upfront or recurring mortgage insurance, loan points, or unpaid MyHome interest is included.
- Households: Full-year California residents under 65, with no dependents, other itemized deductions, AMT, or income adjustments beyond the stated AGI. Federal standard deductions: $16,100 single / $32,200 joint. California standard deductions: $5,900 single / $11,800 joint. Personal credits assumed unchanged; no renter’s credit is assumed at these incomes.
- State income taxes paid: Assumed $4,900 for the $100,000 single buyer; $6,750 for the $120,000 single buyer; $3,450 for the $125,000 joint household; and $5,300 for the $150,000 joint household. These are illustrative payment assumptions, not calculated state withholding. They are included in federal SALT deductions for owners and renters, subject to the same $40,400 cap. California does not deduct California income tax. A tax professional must replace these assumptions with the household’s actual amounts and review refunds or withholding changes.
- Eligibility: CalHFA income limits, education, credit, underwriting, appraisal, solar-lease transfer, and property requirements still apply. This example uses the existing solar lease and does not combine CalHFA with the separate Solar + Assistance program below.
Sources: CalHFA live rates; MyHome program; HUD mortgage insurance tables; IRS 2026 tables; FTB 2026 indexed amounts and schedules.
Would you like to see your own version? Bring your current housing expense and savings goals, and we can compare a payment plan with your tax professional’s estimate.
What could owning a home mean five years from now?
Each principal payment reduces what you owe. If your home also increases in value, that appreciation can add to your equity. These are two different ways your ownership position can grow.
Appreciation applies to the home’s value, rather than only to the amount you put down. If the value grows by a percentage each year, the next year’s growth applies to that new value. This is compounded appreciation.
Here is a simple illustration using the $439,900 Molino Circle asking price as a purchase-price assumption. These are assumed annual growth rates, not forecasts for a California city or a specific property.
Five years. Four possible paths.
Illustrative home values starting at $439,900
- 4% annual growth
- 3% annual growth
- No price change
- 2% annual decline
See the five-year values and gains in a table
| Annual value change | Home value | Value gained or lost |
|---|---|---|
| −2% | $397,635 | −$42,265 |
| 0% | $439,900 | $0 |
| 3% | $509,965 | +$70,065 |
| 4% | $535,206 | +$95,306 |
Calculated as $439,900 × (1 + annual rate)5, rounded to the nearest dollar. Figures show property-value changes only. They exclude loan payments, financing costs, maintenance, purchase and selling costs, and taxes.
The growth scenarios show why time can matter. They also show why assumptions matter. Home values can fall, and leverage magnifies both gains and losses relative to your down payment. An early sale can leave you with less than expected after expenses.
Your equity is your home’s current value minus the debt secured by it. Your down payment starts that equity position, principal payments may increase it, and price changes can move it in either direction. Equity is also different from money available in your checking account. Accessing it generally requires selling, refinancing, or borrowing, with costs and eligibility considerations.
Can renting still be the right choice?
Yes. Renting may fit a short timeline, a likely relocation, or a period when you need more flexibility. Renters can also build wealth by saving and investing.
A useful five-year comparison includes what you might save and invest while renting, the upfront cash needed to buy, the full cost of owning, and the cost of eventually selling. The result depends on your numbers and assumptions. Five years is a useful planning period, not an automatic break-even point.
My job is to help you understand the choices well enough to make a decision you feel good about. If buying supports your goals and the monthly plan works, we can build your path forward. If you need more time, we can make that time useful.
You do not have to build the plan on your own.
I created our How to Afford Your Home page to help you turn a big question into manageable steps. Start with your spending plan, compare your complete housing expenses, explore ways to bridge the gap, and practice the change before you move.
Fine-Tune Your Spending Plan
Track your spending, review recurring expenses, and create an action plan that leaves room for your priorities.
Download the free guide · PDF →
11 Ways First-Time Homebuyers Can Bridge the Gap
Explore payment planning, cash-flow ideas, shared housing possibilities, and a worksheet for our conversation.
Download the free guide · PDF →
Bridge the Gap Between Rent & Your New Mortgage Payment
Find more ideas for reviewing expenses and preparing for the payment you are working toward.
Download the free guide · PDF →
60 Ideas to Build Your Home Fund
Explore extra-income possibilities that fit your skills and time. Money saved and income used to qualify are separate considerations.
Download the free guide · PDF →The guides offer educational ideas and illustrative examples. We will review what fits your circumstances, and your tax professional can confirm any tax assumptions.
Your first home · Your financing options
First-time homebuyer loans: let’s explore your options.
You do not have to choose a loan before we talk. We will compare the upfront funds, the complete monthly payment, and how each option fits your income, savings, and plans.
FHA Loans
Explore a smaller-down-payment option with flexible qualifying guidelines. We will explain mortgage insurance and compare the full cost with other choices.
Explore FHA loans →
Conventional Loans
Learn about conventional financing for your first home, including eligible low-down-payment options and how mortgage insurance works.
Explore conventional loans →
Solar + Assistance
Explore a path to 100% purchase financing and grant options up to 5% toward down payment and closing costs for eligible buyers.
Assistance may be a grant or forgivable second loan. Solar costs are financed into your mortgage. Property and program requirements apply.
Explore Solar + Assistance →Need help with the upfront costs? Visit our Down Payment Assistance page. Assistance works alongside an eligible mortgage and has its own qualifications and repayment terms.
Eligible veterans and service members can also explore VA home loans. For the bigger picture, start with our First-Time Homebuyer Hub.
Common questions about buying versus renting in California
Do all first-time buyers get the same tax savings?
No. Your filing status, adjusted gross income, eligible deductions, and taxes already paid affect the result. Compare the tax you would owe as a renter with the tax you would owe as a homeowner. A larger mortgage-interest deduction does not create an equal-sized refund. Start with our Homeowner Tax Savings Calculator, then review the assumptions with your tax professional.
Does a lower purchase price reduce all the property taxes?
No. Value-based taxes are tied to assessed value, while Mello-Roos special taxes and other direct charges follow their own rules. In the Molino Circle example, we recalculated the value-based taxes at $439,900 and kept the county bill’s direct charges unchanged. See the property-tax breakdown for the full estimate.
Will a home definitely build wealth over five years?
No. Mortgage principal payments reduce your loan balance, but the home’s value can rise or fall. Your equity is the home’s value minus debts secured by it, including repayable down payment assistance. To estimate what you might keep after a sale, also account for selling costs. The five-year graph shows assumptions, not a forecast or guaranteed profit.
Sources and planning notes
- IRS: Should I itemize?
- 26 U.S.C. § 164: State and local tax deduction limits
- IRS: Tax Withholding Estimator FAQs
- CFPB: Financial considerations of buying a home
- Zillow Research: Rent-versus-buy comparison methodology
Educational information, not personalized tax, legal, or investment advice. No appreciation or tax outcome is guaranteed. Loan terms and approval depend on the complete application, property, and underwriting. Amy DeBusk, NMLS 281056. loanDepot.com, LLC, NMLS 174457. Equal Housing Opportunity.