
Chapter 9 of 12
How Family Wealth and Past Losses Shape Homebuying
Consider family resources, mortgage distress, and the experiences that influence ownership decisions.
Jump to a page on the report 1-59 + 37A-37C
The online edition groups several PDF pages into each chapter. Select a page to open its place in the web edition. Pages 1 and 2 correspond to the cover and contents on the research home page. The revised PDF adds Chapter 7 pages 37A-37C while retaining the original page numbers.
Past Losses Can Affect Both Savings and Confidence
 Select the figure for a larger view
 Select the figure for a larger view
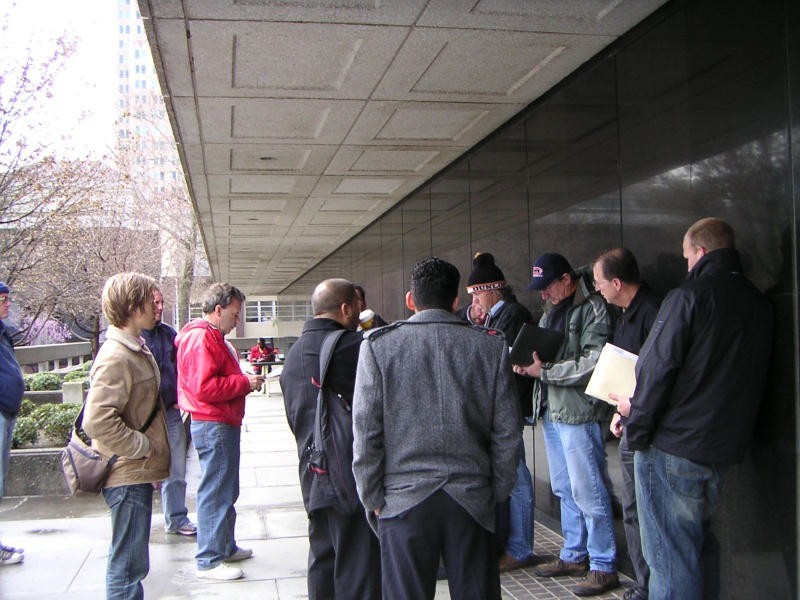
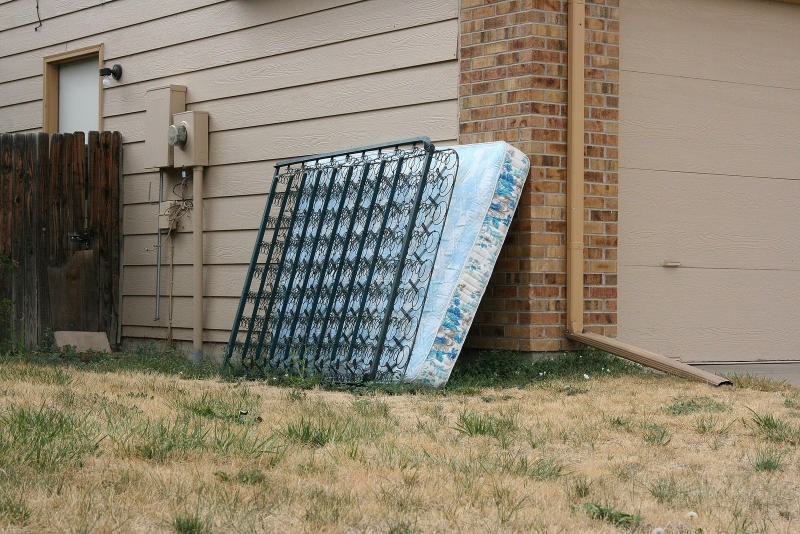
Figures 29 and 30. Left: A deserted house during the foreclosure crisis, August 2008. Right: Bidders at a foreclosure auction, February 2007.
A family foreclosure can remove assets, damage credit, disrupt schooling or employment, and reduce the ability to help the next generation with a down payment. It can also change what children believe about debt, lenders, and housing security. Those channels may reinforce one another, but they are not interchangeable.
Nicholas Fritsch and Rawley Heimer’s Cleveland Fed study follows 53,040 children linked to adult guardians through credit records. By age 30, approximately 50% of children from households without parental mortgage distress had purchased a home, compared with 37% from households with mild distress. The 13-percentage-point gap is descriptive evidence in that sample. Purchases are inferred from mortgage borrowing, which does not measure cash purchases in the same way.
[84]
The study cannot fully distinguish changes in beliefs from family wealth, transfers, credit access, or children’s incomes. Its participants entered the sample at ages 19 to 22 during 1999 through 2004. They are not a direct survey of today’s entire first-time-buyer population. The result establishes a relevant intergenerational association, not a national estimate of fear caused by the 2008 crisis.
Boston Fed research by Anat Bracha and Julian Jamison provides complementary evidence on attitudes. Using 2011 survey responses, it found that personal or close secondhand real-estate losses were associated with lower confidence in homeownership among younger respondents, while the pattern differed for older respondents. Some of the age-split estimates were only marginally statistically significant. The study does not establish that information has no value or that all younger adults learned the same lesson. [13]
The Same Housing Crisis Can Lead People to Different Choices
Malmendier and Wellsjo’s published work on inflation experience finds that people with greater lived inflation exposure are more likely to own, particularly where fixed-rate mortgages are common. The result supports an experience-based explanation of housing choices, but its direction is increased ownership demand and its exposure is inflation rather than foreclosure. [14]
Happel and coauthors’ study of wartime housing destruction in Germany finds lower ownership decades later among exposed cohorts, with evidence favoring changed housing attitudes over several alternative explanations. That historical setting offers a useful example of persistent experience effects. It cannot quantify the consequences of the U.S. foreclosure crisis. [15]
Together, these studies justify including beliefs in housing analysis while resisting a single generational story. Some adults become cautious after family distress; others become more determined to own. Some want to buy but cannot qualify. The same person can belong to more than one of those groups.
Start With What Is Actually Holding a Household Back
A financially blocked aspiring buyer needs help with the actual constraint: income, cash, credit, price, or suitable inventory. Neutral counseling may improve preparation but cannot substitute for an affordable home. A financially ready but hesitant buyer may benefit from transparent downside scenarios, a realistic maintenance budget, reserves, and a clear explanation of loan obligations. A renter who values mobility or prefers a different investment strategy may need no intervention at all.
These categories are practical distinctions rather than diagnoses. The evidence does not establish a prevalence of PTSD among prospective buyers or the number deterred by inherited fear. Calling every cautious renter traumatized would disregard rational risk assessment and the diversity of family experience.
The most informative evaluation would measure present financial readiness separately from stated intentions and childhood exposure. Even after matching on income and observed parental wealth, unobserved differences may remain. A remaining association is not automatically a pure psychological effect. Appendix B supplies a concrete measurement framework and the conditions required for a causal interpretation.
Prefer the original layout? Open this section in the PDF →